
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteiTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
A fintech app usually loses money when its payment events and its accounting records diverge—not because the arithmetic is difficult. A processor can approve a payment while the ledger write fails, a retry can post twice, or a fee, refund, reserve movement or foreign-exchange adjustment can arrive after the app has closed its books. The result is a balance that does not agree with the bank or processor statement.
Double-entry bookkeeping provides the control structure to find and contain those breaks: every event posts equal debits and credits, customer and processor subledgers roll into general-ledger control accounts, and scheduled reconciliations compare those controls with external records. It is not a guarantee of truth by itself. HM Revenue & Customs warns that balanced double-entry records can still be inaccurate, so exception ownership, evidence and review are essential.

Why does a fintech app balance differ from its bank or processor balance?
The difference is normally an unreconciled event, not a mysterious loss. Reconciliation compares statement lines with internal entries, confirms the account balance, captures charges and corrects recording errors. The IRS describes those purposes in Publication 583, while Microsoft calls regular bank reconciliation a practical way to discover missing payments and bookkeeping errors in its account-management guidance.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →For a fintech, the “bank balance” is only one external truth. You may need to agree a bank account, a card processor clearing account, a card-network statement, a wallet custodian statement and customer-funds obligations at the same time. A healthy control process labels legitimate timing differences and resolves genuine breaks instead of writing an unexplained adjustment to a convenient expense account.
#1 Best Overall

- Refined Financial Management: Our ledger books for bookkeeping can be used to track personal bills and budgets and serve as book keeping log for small business.Helps you keep track of your expenses and income for effective financial planning.
- Adequate Ledger Entries: Dimensions are 8.4 x 6.1 inches, making it easy for you to take anywhere. This accounting ledger comes with 3304 entry spaces (120 pages) so you can record all your financial information in one place, with easier access to track transaction types and dates.
- Elegant & Exquisite Design: Our ledger notebook adopts a classic waterproof material cover, which is not easy to wear. Gold double spiral binding makes flipping through easy. This bookkeeping book is also designed with practical inner pockets and bookmark elastic bands.
- Flexible & Thick Paper: Our accounting book is made of 100gsm non-bleeding paper, perfect for fountain pens, ballpoint pens and other pen types. Convenient to write on, so you no longer have to worry about bleeding ink.
- Perfect For Gift Giving: As you would expect, the cover of the book keeping book is beautifully designed with gold foil lettering and floral patterns. Perfect as a gift for parents and friends, or as a business ledger for small business.
Payment succeeded but the ledger write failed
A processor authorization or capture can succeed while an API timeout, queue outage or database error prevents the corresponding ledger entry. If the system later retries without an idempotency check, it can create the opposite failure: one real payment and two ledger postings. Persist the processor event identifier and make the posting operation idempotent so a replay produces the same result rather than another transaction.
Events arrived in the wrong order
Refunds, chargebacks and settlement notifications can arrive before the original capture in an asynchronous system. Posting them immediately to a final revenue account can create a temporary negative balance or a permanent misclassification. Store the event, preserve its source timestamp, and use a controlled pending or suspense state until the prerequisite event is present.
Timing differences were treated as losses
A deposit may appear in the bank one day after a processor closes its batch. A chargeback can be reported after the original sale, and a reserve release can cross a month-end cutoff. These are timing items when the underlying event is valid. Reconciliation should record the expected settlement date and age the item; it should not silently “plug” the difference.
Fees, reserves and foreign exchange were posted in aggregate
Processors may deduct network fees, assessment fees, reserve funding, reserve releases and foreign-exchange spreads from a settlement amount. If the app books only the net deposit, it cannot explain per-transaction economics or prove that the customer and merchant balances are correct. Import the detailed fee and reserve components, map them to explicit accounts, and retain the statement reference for each batch or line.
Deposits and images introduced operational errors
Deposit slips, encoded amounts and captured images can contain errors before an item reaches the ledger. Interagency guidance published by the FDIC identifies inaccurate deposit slips, encoding errors and poor image capture as causes of discrepancies, and says institutions should adopt policies designed to avoid or reconcile them. Read the FDIC guidance when designing deposit controls.
An electronic-transfer error was never investigated
Under Regulation E, an error can include an unauthorized or incorrect electronic transfer, an omitted transfer, or a computational or bookkeeping error. The CFPB definition is in 12 CFR 1005.11. A fintech should therefore preserve the customer complaint, source records, investigation steps and correction journal—not merely change the displayed balance.
What does double-entry bookkeeping change in a fintech ledger?
Double-entry makes the accounting effect of each business event explicit. At least one debit and one credit are posted for the same amount, and the transaction is accepted only when total debits equal total credits. That balancing test catches many incomplete writes, but it does not tell you whether the accounts chosen were correct or whether the event itself was genuine.
Rank #2

- PERFECT FOR RECORD KEEPING: The 2 Pack account ledger books are versatile and can be used to track finances, budgets, expenses, and other business or personal records. They are perfect for individuals, or small business owners who need a reliable and efficient way to keep track of their finances. With 100 pages, customers can record transactions over an extended period, making it a handy tool for bill planner, weekly budget planner, monthly budget planner.
- COMPACT AND LIGHTWEIGHT: The Budget Planner is compact and lightweight with each book weighing 7 ounces and measuring 8.5 x 6.25 inch, making them easy to carry around. You can take the budget notebook in a bag or briefcase, making them ideal for on-the-go use. This feature ensures that you can access your records at any time, whether you are at work or on the move.
- PREMIUM QUALITY: Elegant style with the words ''Account Tracker'' embossed in fancy Gold Foils. Water-proof and scratch resistant hard cover. Coil ring binding is a practical design feature that enhances the functionality of the account ledger books. It allows pages to turn smoothly and easily, making it effortless to flip through the book while keeping pages in place. The ring binding also ensures that pages won't fall out, preventing the loss of vital information.
- DURABLE WATER-PROOF COVER WITH GOLD FOIL LETTERS: The words ''Account Tracker'' embossed in shiny Gold Foil letters gives it a professional and fancy look that can fit in any setting. Additionally, the durable cover is scratch resistant, It provides a durable layer of protection that can withstand daily wear and tear, making it suitable for long-term use.
Start with a chart of accounts that reflects the payment flow
A useful fintech chart of accounts separates assets, obligations, income and costs rather than collapsing everything into “cash” and “fees.” Typical control accounts include:
- Bank cash and restricted cash.
- Processor and card-network clearing.
- Customer-funds or merchant-funds payable.
- Transaction revenue and other operating revenue.
- Processor, network and banking fees.
- Refunds, chargebacks and chargeback recoveries.
- Foreign-exchange gains and losses.
- Reserves held and reserves released.
- Suspense for items that cannot yet be classified.
The exact names depend on your legal entities, products and reporting framework. The important design decision is that every account has an owner, a normal balance, an allowed posting source and a reconciliation source.
Post an event to balanced accounts
Consider this explicitly labelled illustrative case: a customer pays 100 monetary units, the processor withholds a 2-unit fee and sends 98 to the bank. The customer’s stored-value obligation must still be 100 until your product rules say otherwise. One possible journal is:
| Account | Debit | Credit | Purpose |
|---|---|---|---|
| Processor clearing | 100 | Recognizes the processor claim for the captured payment | |
| Customer funds payable | 100 | Records the amount owed to the customer or merchant | |
| Bank cash | 98 | Records the net settlement received | |
| Processor fees | 2 | Records the withheld cost | |
| Processor clearing | 100 | Clears the processor claim |
Every line should carry an immutable event ID, source system, source timestamp, legal entity, currency and exchange-rate reference where applicable. If the processor later reports a refund, post a reversing or refund-specific journal linked to the original event rather than editing history.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minuteUse subsidiary ledgers and control accounts
A general ledger can prove that totals balance while hiding which customer, merchant or processor is wrong. Maintain subsidiary ledgers for customers, merchants, wallets, card programs and processors. Their totals should roll up to general-ledger control accounts such as customer funds payable and processor clearing. A reconciliation then has two tests: the subledger total agrees with the control account, and the control account agrees with the external statement.
Keep history immutable and corrections explicit
Do not overwrite a posted journal to fix a mistake. Record a reversal, a corrected journal and the reason, with the original event ID and approving user. This preserves an audit trail, allows a replay of the ledger from source events and prevents a later investigation from having to guess what changed.
How should a fintech design its reconciliation process?
Reconciliation is an operating control performed at a frequency appropriate to transaction risk. A high-volume wallet may need intraday checks, while a low-volume corporate account may be checked daily or at another documented interval. The procedure below keeps timing items visible and forces every exception to an owner.
- Define the population. List every bank account, processor, network, custodian, wallet and legal entity that must be reconciled. Specify the statement format, currency, cutoff time and responsible owner.
- Ingest source records safely. Load statement lines and webhook or API events with their original identifiers, timestamps, amounts, currencies and references. Reject malformed records, but retain the rejected payload and reason for later repair.
- Normalize without losing evidence. Convert formats and time zones for matching while preserving the original value, source file, hash or message ID. Never discard a processor’s batch number because it is inconvenient to use.
- Match deterministically first. Use an exact event ID or settlement reference where available. Then apply controlled rules for amount, currency, date window, account and batch; record which rule produced each match.
- Post or adjust through approved journals. Create ledger entries for valid events and fees. A timing item remains identified as timing, while a true error receives a reversal or correction journal with evidence and approval.
- Send the rest to an exception queue. Each unmatched item needs an owner, reason code, age, source evidence, expected next action and escalation date. Prohibit a generic “miscellaneous” reason that conceals the cause.
- Reconcile both directions. Check that every external line has a ledger explanation and that every ledger posting appears in an external source or in a documented pending state. A one-way match can miss duplicate internal entries.
- Certify and retain. A reviewer signs off the control totals, unresolved balance, aging and corrective journals. Retain the statement, matching output, evidence and approval according to your legal and regulatory retention policy.
Choose a cadence that follows risk
| Control area | Possible cadence | What the check should detect |
|---|---|---|
| Customer-money and high-volume payment accounts | Intraday or daily, based on volume and exposure | Missing captures, duplicate postings, abnormal net settlement and stale exceptions |
| Processor and card-network clearing | Daily settlement cycle, with batch-level detail | Fees, reserves, chargebacks and settlement timing differences |
| Bank operating accounts | Daily or another documented schedule matched to risk | Unrecorded transfers, bank charges and deposit errors |
| Low-volume or dormant accounts | Periodic schedule with documented rationale | Unexpected activity, stale balances and access-control failures |
The cadence is a control decision, not a universal accounting rule. Document why the interval is sufficient for the maximum customer and liquidity exposure, and shorten it when volume, product risk or unresolved exceptions increase.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Which reconciliation implementation approach fits a fintech?
Implementation choices differ mainly in coverage, matching detail and control maturity. A bank-only, month-end spreadsheet may be adequate for a small operation with no customer-money obligations, but it cannot provide transaction-level evidence for a multi-processor wallet.
| Approach | Coverage and latency | Strengths | Risks and limits |
|---|---|---|---|
| Bank-only, periodic batch | Bank statements; usually daily or month-end; aggregate matching | Simple scope and low initial complexity | Misses processor, network and wallet breaks; timing and fees can be hidden in net deposits |
| Bank plus processor batch | Bank and settlement files; typically daily; batch-level matching | Explains deposits, fees and reserves better than bank-only controls | May not identify which customer or transaction created a discrepancy |
| Transaction-level matching | Bank, processor, network and subledger data; near-real-time or daily | Traceable customer impact, duplicate detection and detailed exception evidence | Requires clean identifiers, currency handling, idempotent ingestion and more operational ownership |
| Continuous control with automated monitoring | Multiple sources; intraday or event-driven | Fast detection, replayable processing, aging alerts and trend analysis | Automation can amplify bad source data or permissions unless reviews, approvals and audit logs remain in place |
Evaluate an option against coverage, granularity, latency, role separation, approval workflow, immutable history, reversal handling, exception aging, evidence attachment, retention, multi-currency support, multi-entity support, retries and replay. These are control requirements, not merely feature preferences.
What should the ledger and data pipeline require?
Reliable reconciliation begins before the accounting entry. The following requirements reduce ambiguity and make a failure recoverable.
Idempotent ingestion and replay
Give every source event a durable unique key, such as a processor event ID plus source account and version. A retry with the same key must not create a second journal. Store raw messages so an operator can replay a failed transformation after repairing a mapping.
Explicit currency and entity context
Never match amounts across currencies without an exchange-rate record and valuation date. Include legal entity, product, customer or merchant, wallet and settlement account on the event. Intercompany transfers should have paired entries and their own reconciliation, rather than appearing as unexplained cash movement.
Permission and approval separation
The person who changes a chart-of-accounts mapping should not be able to approve the resulting manual journal without review. Restrict direct database updates, require dual approval for material corrections and log access to customer-money accounts.
Rank #4
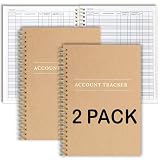
- PERFECT FOR RECORD KEEPING: The 2 Pack account ledger books are versatile and can be used to track finances, budgets, expenses, and other business or personal records. They are perfect for individuals, entrepreneurs, or small business owners who need a reliable and efficient way to keep track of their finances. With 100 pages, customers can record transactions over an extended period, making it a handy tool for financial planning and organization.
- COMPACT AND LIGHTWEIGHT: The account ledger books are compact and lightweight with each book weighing 7 ounces and measuring 8.5 x 6.25 inch, making them easy to carry around. You can take them with them in a bag or briefcase, making them ideal for on-the-go use. This feature ensures that you can access your records at any time, whether you are at work or on the move.
- DURABLE KRAFT COVER: The kraft cover is a distinguishing feature of these account ledger books. It provides a durable layer of protection that can withstand daily wear and tear, making it suitable for long-term use. Additionally, the classic, rustic appearance of the cover gives it a timeless and professional look that can fit in any setting.
- PREMIUM QUALITY: Elegant style with the words ''Account Tracker'' embossed in fancy Gold Foils. The gold coil ring binding is a practical design feature that enhances the functionality of the account ledger books. It allows pages to turn smoothly and easily, making it effortless to flip through the book while keeping pages in place. The ring binding also ensures that pages won't fall out, preventing the loss of vital information.
Reversal and late-arrival handling
Design states for pending, posted, reversed, refunded, charged back and disputed events. A late statement line should attach to the original event or a documented timing item; it should not overwrite a prior close.
Operational metrics
Track exception count and value by reason, oldest unresolved item, suspense balance, duplicate-event attempts, manual-journal volume, reversal rate and time to resolution. Trends reveal a failing integration or process before a periodic close exposes a large unexplained difference.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →Why are balanced books still capable of being wrong?
Balance is a necessary arithmetic condition, not proof that the right accounts were used or that every economic event was recorded. HMRC states: “The fact that an accounting system is double-entry and every transaction is recorded twice as a debit and a credit in the records, does not necessarily guarantee its accuracy.” The warning appears in Enquiry Manual EM2853, updated September 17, 2026.
For example, a developer could debit “cash” and credit “revenue” for an event that was actually a customer liability. The journal balances, yet customer funds, revenue recognition and regulatory reporting are wrong. Independent source reconciliation, subledger roll-ups, account-level permissions and review of unusual journals are what test economic accuracy.
How can reconciliation protect customers and satisfy investigations?
A customer-facing balance correction should be explainable from the original event through the ledger, settlement statement and corrective journal. Preserve the complaint or dispute, authorization records, transfer details, investigation notes and communication. This is especially important when the issue may be an unauthorized, incorrect or omitted electronic transfer under Regulation E’s error framework.
Deposit controls deserve the same attention. Verify deposit preparation, encoding, image quality, dual review and statement agreement. The FDIC’s 2016 interagency guidance says institutions should use deposit-reconciliation policies and practices designed to avoid or reconcile discrepancies; that principle applies directly to a fintech’s bank and custody interfaces.
Recommended Free Tools
What is a practical rollout plan for fixing leakage?
Implement the control in stages so the team can reduce exposure without waiting for a perfect accounting platform.
Best Value

- Quality and Stylish Accounting Solution: the ledger binder is meticulously crafted with excellent quality paper and a sleek PU leather cover in an elegant blue color; The stylish yet professional design serves as an effective tool which is ideal for financial record keeping; The 6 ring ledger books for bookkeeping allow flexibility to add or remove sheets as per requirement, making this a staple for your accounts payable and accounts receivable needs
- Innovative and Efficient Design: the white ledger sheets are specifically designed to promote quick and easy accounting; With designated sections for debit, credit, and balance columns, this business checkbook binder aids in making each task is efficiently accounted for; The intuitive design coupled with the 0.79 inch/ 2 cm width makes it does not occupy much space on your desk
- Compact and Versatile Size: the ledger books, measuring approximately 10.23 x 6 inches/ 26 x 15 cm and the ledger sheets of about 8.5 x 5 inches/ 21.6 x 12.7 cm, are optimized to be perfectly suitable for all your accounting needs. The slim width adds to its compactness without compromising its functionality, thereby making it a must have in your office setup
- Comprehensive Package to Organize Accounting: the package includes 1 accounting ledger with 200 white ledger sheets and 2 sets of index tabs; These small index tabs assist in quickly locating the right portfolio, making your accounting process smoother and more organized
- Reliable and Durable: constructed from quality PU leather, the ledger notebook is notably reliable and durable. What's more, the 6 ring design of the binder makes excellent holding capability; The paper quality of the sheets supports long term use making it not just a purchase, but a smart investment for your accounting and budgeting tasks
- Map every money movement. Draw the path from authorization to capture, clearing, settlement, refund, chargeback, reserve and payout. Mark the system that is authoritative at each stage.
- Freeze uncontrolled plugs. Require a reason, evidence and approval for suspense releases and manual journals. Existing unexplained balances should be aged and assigned rather than hidden.
- Define accounts and ownership. Create the chart of accounts, subledgers, control accounts, normal balances, source systems and reconciliation owners.
- Add event identity. Make source IDs, idempotency keys, timestamps, currency, entity and batch references mandatory fields. Reject or quarantine records that lack them.
- Build two-way matching. Start with exact references, then add documented amount/date/batch rules. Produce an exception queue with aging and evidence links.
- Automate safe actions. Automate ingestion, duplicate detection, standard fee journals and alerts only after mappings and permissions are reviewed. Keep approval for corrections that alter customer or regulatory balances.
- Test failure paths. Simulate timeouts, duplicate webhooks, out-of-order refunds, partial settlements, currency mismatches, late chargebacks and replayed files. Confirm that each case is reversible and visible.
- Review and tune. Examine exception trends and stale suspense weekly or at a risk-appropriate interval. Change rules when a source system, processor format or product flow changes.
How do you troubleshoot a ledger-to-statement mismatch?
Begin with the smallest control account and a bounded statement period. Do not start by changing the displayed balance; first identify whether the break is missing, duplicated, mistimed, misclassified or genuinely unauthorized.
| Symptom | Likely cause | Investigation and correction |
|---|---|---|
| Processor total exceeds the ledger | Missing ledger write or rejected event | Search by processor event ID, inspect ingestion failures, replay once with idempotency and post a linked correction if needed |
| Ledger total exceeds the processor | Duplicate retry, test event or wrong account | Find duplicate IDs and source status, reverse the extra journal with approval, and correct the mapping |
| Bank deposit differs by the fee amount | Net settlement booked as gross cash | Split the settlement into cash, fee and clearing entries using the processor statement reference |
| Difference appears only at period-end | Settlement cutoff, reserve or late chargeback | Compare source timestamps and settlement dates; classify a valid timing item and clear it when the external event arrives |
| Customer subledger differs from the control account | Manual journal bypassed the subledger or an event failed to allocate | Reconcile subledger-to-control first, prohibit direct control-account postings and allocate through a reviewed journal |
| Unexplained suspense grows | Missing identifiers, broken mapping or inadequate ownership | Age by reason and source, assign an owner and escalation date, then repair the upstream data rather than repeatedly clearing suspense |
Can automation prevent fintech money leakage?
Automation can apply the same matching rules at high volume, alert on duplicate IDs, calculate control totals and route exceptions faster than manual spreadsheets. It cannot decide whether a source record is economically true, whether a mapping reflects a new product or whether a user has permission to approve a correction.
Australian auditing guidance emphasizes that automated controls still depend on reliable source data, appropriate access and review. Use automation for repeatability and detection, but retain human approval for mappings, customer-impacting corrections, material journals and unusual exception patterns. Measure whether the automation reduces unresolved age and improves traceability; a high automatic-match rate is not success if the rules are matching the wrong fields.
Free tools Windows power users keep installed
One-click scans. No signup required.
What should a fintech team do first?
Start by reconciling one customer-money or processor control account end to end. Capture every source identifier, separate timing items from errors, and assign every unmatched line an owner and deadline. Then expand the same pattern to other entities, currencies and payment rails.
The durable fix is not simply “use double-entry.” It is a connected control system: balanced journals, subsidiary ledgers, two-way external reconciliation, immutable evidence, controlled corrections and regular review of exceptions. That combination turns an unexplained balance difference into a traceable operational issue before it becomes customer harm, an accounting restatement or regulatory work.
Frequently Asked Questions
How often should a fintech reconcile payment accounts?
There is no single interval that fits every product. Set the schedule from transaction volume, customer-funds exposure, settlement timing and the maximum loss an unresolved error could create; document the rationale and shorten it when exceptions or exposure rise.
Should a fintech use a suspense account for unmatched transactions?
Yes, as a temporary, explicitly controlled holding account—not as a permanent plug. Require a reason code, evidence, owner, age and escalation date, and block routine clearing entries that lack a traceable source event.
What audit evidence should a reconciliation retain?
Keep the original statement or source file, raw event payload, normalized record, matching rule, control totals, exception history, approvals and reversal or correction journals. Linking those artifacts by immutable IDs lets another reviewer reproduce the result.
How should multi-currency payments be reconciled?
Match the original transaction in its source currency, then record the settlement currency, exchange-rate source and valuation date separately. Reconcile both the foreign-currency units and the resulting base-currency valuation so FX movements are not mistaken for missing cash.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

