
To diversify a bond portfolio, spread exposure across different maturities, issuers, and bond categories rather than simply holding more bonds. The right mix depends on your time horizon, risk tolerance, income needs, and tax situation; diversification can reduce concentration, but it cannot make bonds risk-free or prevent losses.
What bond diversification can—and cannot—do
Diversification aims to avoid having too much of a portfolio depend on one borrower, maturity range, or type of bond. If one issuer runs into trouble, for example, a portfolio with other issuers may be less exposed than one concentrated in that borrower. This is a way to manage exposure, not a guarantee against loss. The SEC does not prescribe one bond allocation for every investor.


Count the risks represented by the holdings, not just the number of line items. Several bonds from similar issuers, sectors, and maturity ranges may still leave a portfolio concentrated in much the same way. The SEC recommends considering different bond types and maturities when diversifying; the concentration test is a practical way to apply that guidance. SEC guidance on bond categories and risk.
Which risks should a diversified bond portfolio address?
Interest-rate risk
Market interest rates and the prices of existing fixed-rate bonds generally move in opposite directions. When rates rise, an older bond paying a lower fixed rate may become less attractive, so its market price can fall. You may receive the stated principal at maturity if the issuer pays as promised, but a sale before maturity may bring less than you paid. U.S. government backing relates to payment of principal and interest at maturity, not the price available on an early sale. The SEC illustrates the relationship with a hypothetical Treasury paying 3% with nine years remaining: at a comparable market rate of 4%, its example price is $925. That is a teaching example, not a current quote or forecast. SEC bulletin on fixed-income investments and interest rates.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problems#1 Best Overall
Maturity and coupon affect sensitivity. Longer-maturity bonds generally have greater interest-rate risk than otherwise similar shorter-maturity bonds; all else equal, lower-coupon bonds can also be more sensitive to rate changes.
Credit and default risk
An issuer may fail to pay interest or principal. Spreading holdings among borrowers can reduce dependence on a single issuer, but it does not eliminate the possibility of default. Credit ratings estimate relative credit risk; they are not guarantees, and they can change. High-yield corporate bonds pay higher rates in compensation for greater default risk. A weaker economy can pressure riskier issuers and lead investors to favor higher-quality bonds, weighing on high-yield prices. SEC overview of corporate bonds and SEC overview of high-yield corporate bonds.
Inflation, liquidity, and early repayment
Inflation can reduce what fixed payments buy over time. Liquidity risk means you may not be able to sell quickly at a price that reflects the bond’s expected value, particularly for bonds that trade less often. Some bonds can be called, or repaid before their stated maturity; that may leave you needing to reinvest when yields are less favorable. Funds holding mortgage-related securities can face prepayment risk when borrowers repay loans earlier than expected. SEC discussion of corporate-bond risks.
How to spread exposure across bonds
Vary maturities and interest-rate sensitivity
Consider whether holdings are concentrated in short-, intermediate-, or long-term bonds. Longer exposure generally brings greater sensitivity to rate changes, while shorter maturities can mean cash is returned sooner and may need to be reinvested at then-current rates. For bond funds, duration is a useful measure of sensitivity to interest-rate changes, but it does not capture every risk. Check a fund’s duration and maturity profile rather than relying on its name alone.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Rank #3
Vary issuer types and credit quality
Compare exposure to U.S. Treasury, municipal, and corporate bonds, and consider whether corporate holdings cluster in one issuer, sector, or credit tier. These categories carry different credit exposures. High-yield debt should not be treated as interchangeable with investment-grade debt: its higher rates come with greater default risk. Ratings can help compare credit quality, but they cannot promise an issuer will pay.
Account for tax treatment
Municipal bonds have tax considerations that depend on the investor’s circumstances. The SEC notes that tax-exempt municipal yields are usually lower than yields on comparable taxable fixed-income securities, all else equal. Compare the after-tax implications for your situation rather than judging a bond only by its stated yield. SEC bulletin on municipal bonds, allocation, diversification, and risk.
Check liquidity and call terms
Before buying an individual bond, review whether it can be sold readily and whether the issuer can repay it early. A call can change the timing of cash flows and the opportunity to reinvest. These features matter alongside maturity and issuer type when comparing otherwise similar holdings.
Individual bonds and bond funds behave differently
An individual bond has a stated maturity date and payment terms. If held to maturity, the investor is due the stated principal at maturity, subject to the issuer making the payment; its market value can still move before then. A bond fund holds a changing portfolio and has a market value that fluctuates. It is not risk-free simply because it owns bonds, and a fund may be exposed to credit, interest-rate, and prepayment risk.
Best Value
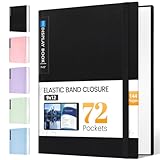
- 72-Pocket Large Capacity Portfolio: The art binder includes 72 bound (non-refillable) top-loading clear sheet protectors, displaying up to144 pages. Fits 9”x12" letter size or smaller. Measures 12 7/8" (L) x 9 11/16" (W) x 1 1/2" (G).
- Elastic Band for Secure Protection:For total peace of mind, a sturdy elastic band keeps your portfolio securely fastened. Your important papers stay put, organized, and protected from damage.
- High Transparency & Tailor-Made Spine Title: Our presentation book with crystal clear PP sheet protectors offers complete transparency for checking through and organizing. You can label and identify your watercolors, sketches, scrapbook, art pieces, sheet music, certificates, and other projects by customizing the reversible spine insert.
- Archival Grade & Heavy Duty Cover: Made from robust yet light weight, polypropylene which is archival quality, acid-free and non-glare, and water-proof. Thickened and sturdy cover won’t easy to crack and keeps your clear sleeves from being damaged.
- Multi-Function: Not only suitable for long-term storage but also for displaying your paintings, photos, artwork, drawing, stencils. Great gift for students, teachers, office workers, secretaries, musicians, painters, etc.
For a fund, review its current holdings, duration, maturity profile, and prospectus risk disclosures. A label such as “short-term” or “ultra-short” does not by itself establish that the fund has no meaningful risk. SEC overview of bond funds and income funds and SEC bulletin on ultra-short bond funds.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.A practical way to review your bond mix
- Set the purpose. Identify when you may need the money, how much income you need, and how much market-value fluctuation you can tolerate.
- Map the exposures. Group holdings by maturity range, issuer, bond category, and credit quality. Look for dependence on a single borrower, sector, or type.
- Compare rate sensitivity. For individual bonds, consider maturity and coupon; for funds, check duration and maturity profile along with the prospectus.
- Review cash-flow terms. Check call provisions, prepayment exposure, and liquidity so you understand when you might receive cash and the conditions under which you could sell.
- Consider taxes. For municipal bonds, compare the potential tax treatment and yield in light of your own circumstances.
- Recheck changing details. Yields, prices, fund holdings, credit conditions, and tax rules can change. Consult current bond disclosures, fund prospectuses, and applicable tax guidance before making a specific investment decision.
There is no universally best percentage mix or maturity structure established by the SEC guidance. A ladder or another maturity pattern may distribute cash-flow dates, but it also involves reinvestment and interest-rate tradeoffs; it should not be treated as protection from loss.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

