
Recommended Free Tools
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
Keep cash you may need at short notice in a savings account; consider a Treasury bill for money you can leave invested until a known maturity date. A savings account is designed for withdrawals under the bank’s rules, while a bill pays its face value at maturity. Selling a bill early requires a bank, broker, or dealer—and if you buy through TreasuryDirect, you generally must wait 45 days before transferring or selling it.
Neither option is automatically the better deal. Compare the current bill auction rate with the actual account APY and terms, then account for access, taxes, and protection. Savings APYs can change; a bill’s auction rate is fixed for its term.
How do Treasury bills and high-yield savings accounts differ?
| Factor | Treasury bills | High-yield savings accounts |
|---|---|---|
| How earnings work | Bills are generally bought at a discount or at par. The difference between the purchase price and face value is interest, paid at maturity. The rate is fixed at auction for that bill’s term. | The account earns interest under its terms. A variable rate and APY may change during the time you hold the deposit. |
| Access to cash | The Treasury pays the face value at maturity. To get cash sooner, arrange a secondary-market sale through a bank, broker, or dealer; resale price and proceeds depend on the market and arrangements. TreasuryDirect imposes a 45-day hold before a security can be transferred or sold. | Designed for withdrawals, subject to the bank’s transfer process, limits, fees, and other account rules. Check those terms rather than assuming access is instant or unrestricted. |
| Taxes | Interest is subject to federal income tax but exempt from state and local income taxes. | Interest is generally taxable income. State and local treatment depends on applicable rules and your circumstances. |
| Protection | Not FDIC-insured; a bill is direct U.S. government debt. | Qualifying deposits at an FDIC-insured bank are covered up to the applicable limit and ownership-category rules. |
| Ongoing work | Choose a term and purchase channel, then plan for maturity or a possible sale. | Open and maintain the account, and monitor its rate and terms. |
Which is better for cash you may need soon?
Choose a savings account for uncertain or near-term needs
A deposit account is usually the more practical place for an emergency reserve, upcoming bills, or cash whose withdrawal date is unclear. You can request a withdrawal under the bank’s rules without arranging a market sale. Verify how transfers work, how long they take, and whether limits, minimums, or fees apply.
Consider a bill when the date is predictable
A Treasury bill can fit money you do not expect to need before a known date. TreasuryDirect lists bill terms of 4, 6, 8, 13, 17, 26, and 52 weeks; its minimum purchase is $100, in $100 increments. Those terms make it possible to align a maturity with a planned expense, but do not make early access equivalent to a bank withdrawal. See TreasuryDirect’s Treasury Bills information for current product details.
#1 Best Overall
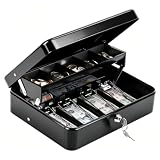
- 【 Built for Vendors: 1mm Thick Steel Security & Portability】Designed specifically for small business owners and market vendors, this cash box is crafted from 1mm thick heavy-gauge steel to resist drops, impacts, and forced entry during busy flea markets or yard sales. The robust 1mm metal build ensures your earnings stay secure, while the smooth key lock system and widened handle make it easy and safe to transport between your car and booth. Includes 2 keys for backup convenience
- 【 Smart Organization: Auto-Pop Tray & Hidden Compartment】Maximize efficiency with a cantilever coin tray that lifts automatically to reveal organized slots for coins. Crucially, it features a hidden rear compartment perfect for storing $50/$100 bills, receipts, or USB drives separately from daily change. This "cash drawer" style design keeps high-value items out of sight and secures your most important assets during transactions
- 【Windproof Bill Clips: Secure Cash Management Outdoors】Say goodbye to scattered cash. Our 4 strong spring clips are calibrated to hold bills ($1-$20) firmly in place, acting as a windproof solution for outdoor events like farmers markets and food trucks. While the grip is secure to prevent loss in the wind, the clips are smooth enough for quick access, allowing you to make change rapidly even when lines are long
- 【Perfect Fit for Mobile Business & Home Use】Measuring 11.8" x 9.45" x 3.54", this portable money box strikes the ideal balance between capacity and portability. It fits neatly into market crates, under vendor crates, or in desk drawers. Whether you are running a school fundraiser, managing a food truck, or organizing household savings, it provides ample space without taking up valuable room
- 【Professional Finish & Durable 1mm Construction】Finished with a sleek, scratch-resistant black coating, this 1mm thick metal cash box maintains a professional look even after repeated use. It is a reliable, long-lasting investment for anyone needing a secure cash handling solution. Backed by superior material thickness and quality construction, it withstands the rigors of daily commerce, keeping your financial operations organized and professional
If you might need the money before maturity, an early sale is possible through a bank, broker, or dealer, but the price and timing are subject to the resale process and market conditions. TreasuryDirect says a newly purchased marketable security must be held for 45 days before it can be transferred or sold there. That restriction means a four-week bill bought through TreasuryDirect cannot be sold through that system before it matures. Review TreasuryDirect’s selling guidance for the rules and available routes.
How predictable is the return?
A bill locks its auction rate for its term
TreasuryDirect states that a bill’s rate is fixed at auction for the length of that bill. If you hold it to maturity, the purchase price and face value determine the interest earned. The quoted auction rate is not a savings-account APY, so compare figures over equivalent time periods and on a consistent basis.
Rank #2

- 【1mm Reinforced Body & Secure Key Lock】Engineered with a heavy-duty steel core and finished with a durable powder-coated layer, this cash box achieves a solid 1mm total reinforced thickness—delivering a noticeably sturdier feel than the flimsy 0.5mm bodies found on standard models. The smooth key lock keeps your cash, checks, and valuables secure, while the wide-grip handle makes it effortless to carry to garage sales, yard sales, farmers markets, or food truck setups. Comes with 2 keys so you'll always have a backup.
- 【Auto-Pop Coin Tray with Spill-Proof 1.8cm Foam Liner】Say goodbye to rattling coins and messy spills. The 5-compartment tray automatically pops open when unlocked, and the 1.8cm deep foam lining gently cushions coins in place—effectively silencing noise during transport and preventing coins from popping out, even on bumpy rides. The quiet operation also makes it ideal for home use as a budgeting envelope system without disturbing others.
- 【Finger-Safe Bill Clips with Calibrated Tension - Upgraded Springs】Four spring-loaded clips hold 1/5/10/20 bills firmly against the wind on blustery outdoor days. We re-engineered the clip tension to strike the perfect balance: bills stay put when you need them to, but release smoothly without the painful snap-back that can pinch your fingers—a thoughtful upgrade for busy market days, bake sales, and ticket booths.
- 【Hidden Storage Under the Cantilever Tray】Lift the cantilever-style coin tray to reveal a concealed rear compartment. Stash 50/100 bills, receipts, or small valuables separately from daily transaction cash, keeping large denominations discreet and organized. This dual-level layout keeps everything visible and within reach, helping you make change fast when the line starts to grow at your church fundraiser or carnival booth.
- 【Versatile Size That Fits Your Hustle】Measuring 11.8 x 9.5 x 3.54 inches, this compact cash drawer slides neatly into desk drawers for office petty cash management, tucks into market crates, and sits stably on vendor event tables without hogging space. Ideal for small businesses, pop-up shops, school fundraisers, charity bake sales, or even as a cash gift box—wherever cash flows, it's ready to go.
A savings APY can change
A savings account’s current APY describes its rate at that time, not a promise that the same rate will apply for the full period you keep cash there. The FDIC’s Truth in Savings guidance allows variable-rate account rates to change, subject to account terms and applicable notice rules. Check the bank’s current disclosures and do not project today’s APY across a future period as guaranteed.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteCompare current offers, not old headlines
Rates move. A sound comparison uses the latest available Treasury bill auction result and the live APY and terms offered by the specific bank. No current yield leader is established here. Include any fees, minimums, access conditions, and the length of time you can leave the money untouched.
Rank #3
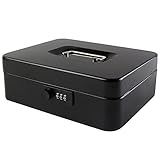
- DURABLE AND UNBREAKABLE: The cash box is unbreakable in our daily life due to strong metal material. Besides, the inner removable money tray is so sturdy built that you have no reason to worry about the security of your items.
- ADVANCED COMBINATION LOCK: The locking device consists of a 3-number combination lock ,which contributes to protect your valuables.It is unnecessary for you to be afraid of losing your keys results from the well-designed code system, which can be simply set or changed.
- REMOVABLE MONEY TRAY: The inner cash tray of the storage box is made up with five compartments, so your cash, coins and keys are able to be accepted separately. Besides, there is huge space for you to take care of checks, receipts and valuables at the bottom of the box.
- WIDE MULTIPURPOSE APPLICATION: The locking cash box is capable of varied occasions. No matter where you are, for instance, school, office, factory, supermarket and anywhere else, the lock box could actually breathe new life into your lifestyle.
- SIZE AND COLOR: The size of the cash boxes is 9.84"x 7.87"x 3.54" (250*200*90mm), and the color is black, a very classic color.
How do taxes affect the comparison?
IRS guidance says Treasury bill interest is subject to federal income tax and exempt from state and local income taxes. Bank interest is generally taxable when it is available for withdrawal without penalty. Treasury bill interest is generally reported for the year the bill matures. See IRS Publication 550 and IRS Topic 403.
The state and local tax exemption may improve a bill’s after-tax result for some taxpayers, but the difference depends on your tax situation and jurisdiction. Compare after-tax returns using your own circumstances; this article does not calculate a personalized break-even rate or provide tax advice.
Rank #4

- 【Leave Cash Securely When You're Not There】Ideal for farm stands, porch pickup orders, roadside stands, and small self-service setups. Customers can easily drop cash, notes, or payments even when no one is on site, helping you collect payments without staying around all day.
- 【Locked Design with 2 Keys for Controlled Access】Built-in lock system keeps collected cash protected. Comes with 2 keys for owner or manager use, making it suitable for unattended payment collection where access needs to stay controlled.
- 【Built for Farm Stands, Porch Pickup & Local Collections】Works well in real daily use cases like farm stands, egg stands, produce stalls, porch pickup payments, donation boxes, rent collection, and small office cash handling. Suitable for indoor setups and semi-sheltered outdoor locations such as porches and entryways with overhead cover.
- 【Compact Slot Helps Prevent Fishing Attempts】Measuring 10.24"H x 5.7"W x 2.95"D inches (Drop Slot: 3.15"L x 0.3937"W). Designed for folded bills, receipts, and small payment notes. The narrow opening also helps reduce the risk of reaching inside with tools or hooks, making it more secure for unattended setups.
- 【Wall Mount Setup Saves Space & Stays Stable】Mount it on walls, wooden posts, porches, kiosks, or counters to create a fixed payment point. Pre-drilled holes make installation simple, and all necessary mounting hardware is included for quick setup. Helps keep surfaces clear while ensuring the box stays securely in place, suitable for indoor use and covered outdoor environments.
What protection applies to each option?
Savings deposits: FDIC coverage rules
FDIC insurance covers qualifying deposits up to $250,000 per depositor, per insured bank, per ownership category. Deposits in the same ownership category at the same bank are combined when determining coverage. The limit is not necessarily a separate allowance for every account. If your total is near or above the limit, review the FDIC’s deposit insurance guidance and your full ownership structure.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchTreasury bills: government obligation, not deposit insurance
Treasury bills are not FDIC-insured. They are direct U.S. government debt, which is a different form of backing from federal deposit insurance. The FDIC explicitly excludes U.S. Treasury securities from insured deposits; do not treat a bill as an insured bank balance.
Best Value

- 【Resettable 3-Digit Combination Lock】: Open the box with the factory code 000. With the dials centered on the current code, move the internal lever from A to B, choose a new combination, then return the lever to A. Center every digit precisely so an adjacent number is not recorded by mistake
- 【Removable Tray for Organized Storage】: The removable coin tray separates loose change and compact items, while the lower compartment provides space for folded bills, receipts and other small essentials. Lift out the tray whenever you need access to the storage area below
- 【Compact Size with Carry Handle】: Measuring 7.87 x 6.30 x 3.35 inches, this small cash box fits neatly on counters, shelves or inside many drawers. The built-in handle makes it convenient to carry between home, work and temporary selling events
- 【Cash & Medication Storage】: Organize coins, folded bills, receipts, photos and appropriately sized medication in one compact lock box. The combination lock supports controlled access at home or in shared spaces. Use certified child-resistant storage whenever that level of protection is required
- 【Cold-Rolled Steel for Everyday Use】: The metal body and black finish suit routine use at home, in offices, at garage sales, school events and vendor tables. The box provides everyday organization and basic access control; use a high-security safe for large amounts of cash or irreplaceable valuables
A practical way to decide
- Set the access requirement. Keep the portion you could need at an uncertain time in a deposit account whose withdrawal and transfer rules work for you.
- Match a bill term to a known date. If some cash can remain invested, consider a term that ends before the planned expense. TreasuryDirect lists 4-, 6-, 8-, 13-, 17-, 26-, and 52-week bills; its minimum is $100 in $100 increments.
- Compare current rates and terms. Check the latest bill auction result and the bank’s current APY, then account for how long each rate applies, plus fees, minimums, and withdrawal or transfer rules.
- Adjust for taxes and coverage. Consider the bill’s state and local tax exemption alongside federal tax, and confirm that bank deposits fit within FDIC limits for your ownership categories.
- Plan for maturity or early sale. If buying through TreasuryDirect, account for its 45-day hold. If you may need to sell elsewhere before maturity, understand the intermediary’s process and the possibility that resale proceeds depend on market conditions.
This is a general framework, not individualized financial or tax advice. For money needed on demand, liquidity is often more important than a small rate difference; for money with a firm horizon, a bill’s fixed term and rate may be useful.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

