
Free tools Windows power users keep installed
One-click scans. No signup required.
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
You can apply for a business credit card as a sole proprietor or freelancer—even if you have not incorporated—but the issuer will decide eligibility and may review your personal credit. Before you apply, gather accurate business and personal details, compare the card’s terms, and read its personal-guarantee language. An EIN by itself does not guarantee approval or remove personal responsibility for the debt.
1. Confirm who is applying
A business credit card application may ask for both the business’s details and the owner’s personal information. Your application should reflect the business and legal structure you actually have; do not invent a company name or business activity to fit a form.
Sole proprietors and freelancers
You may have a business for application purposes without forming a corporation or LLC. Chase says some sole proprietors and freelancers can apply for its business cards. For the applications it discusses, applicants without an EIN can use an SSN, and someone without a separate business name may use their own name. These are Chase-specific explanations, not a promise that every issuer’s forms or eligibility rules work the same way. See Chase’s guidance for sole proprietors and its EIN application guidance.
Recommended Free Tools
Applicants with an EIN
An EIN identifies a business for tax purposes, but supplying one does not establish that the issuer will approve the application, skip a personal-credit review, or waive a personal guarantee. Chase’s explanation of applying with an EIN describes how an identifier may be used; it should not be read as an EIN-only approval route that avoids personal underwriting.
#1 Best Overall

- Premium Materials: This business card holder for purse is crafted from premium leather and polished high quality stainless steel accents. The leather surface is scratch-resistant and durable, while the metal parts add sturdiness and a sleek look. Designed to hold 15–25 standard-sized business cards(according to the thickness of your cards), pocket bustness card holder wallet keeps your cards well-organized and protected.
- Easy to Use: portable business card holder case slim compact design easily fits in your pocket, purse or briefcase without extra bulk. The sturdy leather and metal shell shields your cards from bending, scratches and damage. The smooth metal closure keeps the case with Magnetic Shut,while allowing quick access to your cards when needed.
- Compact Design: The business card case for men or women is classic leather with polished metal trim creates a refined, professional appearance. Perfect for business meetings, networking events, office use and daily carry. It helps you present your business cards in a neat and impressive way during professional interactions.
- RFID Blocking Technology: PU leather business card holders Meet more people's needs, equipped with advanced rfid blocking secure technology, which can perfectly block unwanted rfid scanners. The inner compartment is designed to fit most standard-sized business cards, credit cards and ID cards. The smooth leather lining prevents cards from sticking or getting scratched when you take them out. The polished metal edges avoid sharp corners, ensuring safe and easy handling.
2. Gather the information the application may request
Have your identification and business information ready before starting. The exact fields depend on the issuer and card, so check the live application rather than relying on a generic checklist. Chase’s application guide discusses the following details:
- Your personal identifying information and SSN or other requested tax identification information.
- Your business’s legal or operating name; if you do not have a separate formal business name, Chase says its application guidance allows an applicant to use their own name.
- Your business tax identification information, such as an EIN if you have one.
Use the names and identifiers that match your records, and answer each field truthfully. For the issuer-specific overview, see Chase’s business-card application guide. The SBA also lists general banking documents to prepare when launching a business at Launch your business.
Rank #2

- ✅ How much is YOUR Identity worth? Choose TYVEK Credit Card Protector Sleeves. Best in class materials. FIPS 201 APPROVED: Government approved to ensure total RFID blocking security..
- ✅ ArmorShield Your Identity: Protect your tap-to-pay cards and magnetic strips. RFID 13.56 mHz Blocking - ArmorShield is a proprietary interior coating that protects against unauthorized scanning and identity theft.
- ✅ Keep YOUR identity safe: Skimmers and scammers use RFID technology to grab data from your credit cards while still in your wallet!! Now you can guard yourself against with DUPONT TYVEK Credit Card Sleeves.
- ✅ SAFE HOLIDAY TRAVELS: Home and abroad with scan protector RFID Blocking Credit Card Protector Sleeves for your wallet or purse. Keep your personal identity that is on credit cards, debit cards, bank cards, licenses and other cards from Identity theft skimmers.
- ✅ 100% Made In USA. Only available from Aspira Distributors International. For more of our products, Search For: Semper Paratus Gear Gifts for men
3. Understand the credit review and who owes the balance
Many small-business cards involve a review of the owner’s personal credit and a personal guarantee. A guarantee can make the owner personally responsible for covered debt if the business does not pay. Terms vary, so review the actual application, guarantee, and account agreement before submitting or accepting an account. Do not assume that an LLC, an EIN, or a particular credit score guarantees approval or shields you from liability.
The SBA’s general discussion of secured business cards explains that personal credit and guarantees can matter: Is a secured business credit card right for you? This is a broad article dated December 10, 2018, not a statement of any issuer’s current underwriting rules.
Rank #3
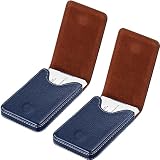
- Package Quantity: you will receive 2 pieces business card holder, both are blue, nice quality for long time to use
- Good material: this business card holder is made of of PU leather with vertical version design, built-in magnetic closure provides quality magnetic force, convenient to use
- Delicate Design: the frame of this business card holder case stitched with threads, which ensures it doesn't fray of edges, which is endowed with fine texture and comfortable tactile impression
- Large Capacity: leather business card holder holds about 20-25 business cards (according to the thickness of your cards) or other universal cards
- Valentines Gift:featuring an attractive and cute appearance, this leather card holder is a practical and warm gift choice for the holiday season; It serves as an ideal Valentines gift for colleagues, friends, family, or as a thoughtful company souvenir to spread festive cheer
4. Compare cards against the business’s needs
Before applying, compare the specific products you are considering. A card’s rewards are useful only if they fit the business’s spending and do not distract from costs or repayment terms.
- Fees: Check the annual fee and any other fees in the current terms.
- Cost of borrowing: Review the APR and how interest applies, or confirm whether the product requires payment in full on a schedule.
- Rewards: Match categories and redemption rules to expenses the business actually has.
- Employee cards and controls: If additional users are needed, check whether cards are available and what spending controls the issuer offers.
- Liability and guarantee: Read who is responsible for balances and whether the owner must provide a personal guarantee.
- Credit reporting: Ask which bureaus, if any, receive account activity and whether that differs for positive and negative information.
Verify these details on the issuer’s current product page and in the agreement. There is no universal reporting practice: opening or using a business card does not automatically build business credit, and separating expenses on a card does not itself create legal separation between you and the business. The SBA discusses ways businesses may establish credit at 5 Ways to Get Credit for Your Business, published May 11, 2017; confirm current reporting with the issuer of the card you choose.
Rank #4

- SLIM & COMPACT DESIGN: Holds 15–25 business cards (depending on card thickness) or a small number of standard-sized cards. Lightweight and slim profile fits easily in your pocket, briefcase, or bag—ideal for everyday business carry.
- PREMIUM PU LEATHER & STAINLESS STEEL: Crafted with a high-quality PU leather exterior and a durable stainless steel interior, offering a professional appearance with enhanced protection and long-lasting use.
- SECURE MAGNETIC CLOSURE: Built-in magnetic flip closure keeps your cards securely stored while allowing quick and easy access during meetings, presentations, or networking events.
- RFID BLOCKING PROTECTION: Integrated RFID blocking technology helps reduce the risk of unwanted wireless scanning for RFID-enabled cards, providing added peace of mind during daily professional use.
- IDEAL GIFT FOR PROFESSIONALS: A practical and stylish choice for business owners, entrepreneurs, sales professionals, and corporate staff—perfect for work, networking, or professional gifting.
5. Submit the application and keep records
- Choose a card only after checking its current application requirements, fees, repayment terms, guarantee, and reporting practices.
- Complete the issuer’s current online or other application using accurate personal and business details. Field names and required documents differ by issuer.
- Review the disclosures and any guarantee before accepting the account. Save the agreement and application confirmation with your business records.
- Use the card for business expenses you can track and repay. Keep receipts and statements so you can reconcile charges and avoid mixing business and personal spending in your records.
6. If an issuer declines your application
Check the issuer’s notice or contact the issuer to understand the stated reason before applying elsewhere. If an unsecured card is not available, a secured business card may be an option for some applicants: it generally involves a deposit, and fees or high interest may apply. The SBA’s December 2018 article discusses secured cards as a possible route, but it does not establish current deposit amounts, availability, fees, or approval standards. Verify the present terms directly with an issuer before committing.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Quick Recap
Best Value

- FREE FOREVER, NO SUBSCRIPTION: Other NFC business cards charge you a monthly fee to keep sharing. Blinq doesn't. Share your digital card and manage unlimited contacts with context, at no ongoing cost, on any iPhone or Android.
- YOUR BRAND, YOUR CARD: Add your logo, links, colors, and photos, and make the card unmistakably yours. Update your details anytime in the Blinq app, so you'll never need to reprint when something changes.
- TAP TO SHARE INSTANTLY: Tap your card or scan the QR code, and your profile lands on any iPhone or Android in seconds. Ask for theirs back and Blinq saves it automatically, with context, no typing required.
- NO APP NEEDED FOR THEM TO RECEIVE YOUR CARD: Whoever you meet, they don't need the Blinq app or a Blinq card of their own. A tap or a scan, and your details are on their phone, every time.
- MORE THAN A DIGITAL CARD: Scan a paper card, use the AI notetaker to summarize your conversation, and let Blinq enrich the contact so nothing about that meeting slips away. This is the AI contacts app for people who meet people, free from day one.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

