
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
To file an uninsured motorist (UM) claim, report the crash to your own insurer promptly, tell the adjuster the other driver appears uninsured or cannot be identified, and follow the notice, proof-of-loss, and evidence requirements in your policy. UM coverage is part of your own auto policy; what it pays—and what you must do to qualify—depends on the policy and state law. For a hit-and-run, report the crash to police promptly and keep the report number.
What an uninsured motorist claim can cover
UM coverage is first-party coverage under your auto policy. It may respond when an at-fault driver has no liability insurance. Depending on state law and policy terms, UM may also apply when a driver’s liability insurer denies coverage or is insolvent, or in some hit-and-run situations. The National Association of Insurance Commissioners (NAIC) describes these potential situations in its uninsured motorist overview.
Uninsured motorist bodily injury (UMBI) and uninsured motorist property damage (UMPD) are separate coverage categories. Having one does not necessarily mean you have the other. Whether damage to your car is covered, what deductible applies, and whether a hit-and-run qualifies depend on your policy and state. Maryland’s insurance regulator likewise advises consumers to check their policy for coverage amounts and deductibles: Maryland’s uninsured motorist coverage guidance.
Do not assume UM automatically pays for vehicle repairs. Check your declarations page and UM endorsement for the coverage you bought, applicable limits and deductibles, exclusions, and duties after a loss. If you also have collision coverage, ask the adjuster which coverage may apply and how using it could affect your claim; the answer depends on your contract and state rules.
#1 Best Overall

- The Road Guardian- The portable roadside assistance kit is designed and hand picked by a group of experienced veterans and experts to provide every essential tools you need in roadside emergencies. The automotive safety bag contains accessories such as repair cable ties, bungee cords, electrical tape, space blanket, rain poncho, reflective warning triangle, glass breaker, seatbelt cutter, safety gloves, tow rope and more to get your vehicle back on the road and continue your travel.
- Top-Notch Digital Auto Tire Inflator- lightweight and compact air compressor can inflate your standard vehicles tire in seconds. With auto shutoff function, simply plug it into the 12v power outlet and attach the stem to the tire valve, preset the tire pressure and press the power button. The compressor starts the inflating process and stop once your tire reaches at your preset level. This cool gadget also has led light for winter nighttime and three extra nozzles for inflammable bed, others
- Copper-Clad Aluminum 12 Feet 8 Gauge Jumper Cable- A durable battery starter cable is a must-have for your trip. Unlike other kits on the market, our jumper cable has reasonable length to get your cars connected. 8 gauge wires and 300 amp output is more than enough to get your standard vehicle started. UL listed heavy-duty battery jumper cables make you physically and environmentally safer and more reliable.
- Completed 108 Pieces First Aid Kit- By having a completed first aid kit, provide you and your family proper basic wound/hygiene treatment before it possibly get worsened during your road trip. Our kit includes alcohol pads, bandages, cotton tips, knuckle bandages, butterfly bandages, wound pad, sting relief pads, gloves, tape, dressing, PBT bandage, CPR mask, tweezer, safety pins, soap wipe, disinfect wipe, adhesive wound pad, triangular bandage, finger bandage.
- Veteran Owned Company 5-Star Customer Support- Everlit is committed into providing the most comprehensive customer service. We proudly offer the exclusive 60-days hassle-free return among all products. We stand behind the quality of our inventory; all original Everlit products are covered with a 1-year satisfaction warranty.
What to do after a crash with an uninsured or unidentified driver
1. Take care of safety and report the crash
Get emergency medical help if needed, remain at the scene, and follow police instructions. If it is safe, record the other driver’s name, vehicle and insurance details, and contact information for witnesses. Photograph the vehicles, damage, and scene when safe to do so.
If the other driver leaves or cannot be identified, contact law enforcement promptly and ask how to get a copy of the report. Keep the report number. Reporting rules are not uniform: Washington’s insurance regulator describes a 72-hour reporting rule for phantom-vehicle accidents in Washington, not as a nationwide deadline. Its crash guidance also advises drivers not to leave the scene and to gather details and take photos when safe. Illinois warns that a company could deny a hit-and-run vehicle-damage claim without a police report in its auto insurance guidance.
2. Notify your insurer and identify the claim as a UM loss
Use the claims number on your insurance card or the insurer’s official claim channel. Explain that the other driver appears uninsured or is unidentified and ask the company to evaluate the loss under your UM coverage. Report it promptly: Illinois’ Department of Insurance advises immediate notice and review of the policy’s conditions.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Rank #2

- 2-in-1 emergency-escape tool provides a window hammer and seat-belt cutter; 2-pack
- Tungsten double-head hammer: 1800HV hardness, 3 times stronger than common carbon steel – for instant car-door window breakage
- Sharp blade for easily cutting through a seat belt; bright-orange plastic handle provides a secure grip
- Designed to help escape from a sinking, over-turned, crashed, or burning car
- Protective bracket included for safe storage; store in center console or driver-side door pocket
Ask the insurer to confirm these details in writing:
- Your claim number and the assigned adjuster’s contact information.
- Which coverage sections are being considered, including UMBI, UMPD, or any other potentially relevant coverage.
- Which forms and records the insurer needs from you.
- Every notice, proof-of-loss, inspection, and other deadline that applies to your claim.
3. Check your policy and calendar its deadlines
Review your declarations page, UM endorsement, and the policy section often titled “Duties After a Loss” or something similar. Note any requirements to give notice, cooperate with an investigation, submit a proof-of-loss form, or meet other conditions. An insurer may set a deadline for a required proof-of-loss form; Illinois’ regulator warns that failing to meet a policy deadline could lead to denial.
There is no single filing deadline that applies to every UM claim nationwide. Policy notice terms, proof-of-loss dates, hit-and-run reporting conditions, statutes of limitation, and arbitration or lawsuit requirements may differ by state and policy. Ask your adjuster for all applicable dates in writing. If a deadline may have passed, or the dispute could affect your legal rights, contact your state insurance department or a qualified local attorney promptly.
Rank #3

- 【Things you may need】: This roadside assistance packages is a perfect gift.Contain the necessary roadside kits, snow shovel, flashing lights, reflective triangle warning signs, advanced jumpers (8.2 foot), powerful towing rope, safety hammer and seat belt cutters, life blankets, raincoats, compasses and more!
- 【Safe and durable】: UL certified jumper cables are safer and more reliable than other non-UL certified cables. Four huge alligator clips provide excellent grip. The grip of the clip is covered with an insulating rubber sleeve. The surface of the reinforced cable is made of high-quality PVC, which has the characteristics of anti-freezing, anti-cracking, and anti-tangling.
- 【Car repairs tool box】: Small and compact, suitable for any place, the tools are neat and orderly. Including hammer, pliers, utility knife, tape measure, PVC tape, digital display test pen, 3 screwdrivers. Each kit has a separate location. Clean, safe, convenient, light and strong plastic shell can withstand pressure
- 【Upgrade kit】: Our hammer head is made of high-quality high-carbon steel, with a pointed and flat hammer. It helps to use any side of the car escape tool to quickly break the window in an emergency. We provide raincoats and reflective safety clothing, which can be safer to wear when you repair a broken down car.
- 【Emergency car kit】: This emergency kit car, It’s lightweight, compact. that can fit anywhere in your backseat, trunk or even in your spare tire compartment, can handle unexpected things,it also includes preparedness survival tools for outdoor activities like camping, hiking, hunting, act. perfect for family use at home.
State laws can set specific reporting requirements for particular claims. For example, a North Carolina statute addressing certain bodily-injury claims involving an unidentified vehicle calls for reporting the collision to an appropriate official within 24 hours or as soon as practicable, and separately addresses notice to the insurer. That rule applies in its statutory context; it is not a general deadline for all UM claims or other states. See North Carolina General Statute § 20-279.21.
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Repair Windows errors before they cause bigger problems3Fix the driver behind crashes, sound loss and screen glitchesWhat documents and evidence to keep
Keep a dated file and copies of everything you send or receive. The exact documents depend on the loss and the insurer’s reasonable requests, but useful records may include:
- The police report or report number, plus scene and damage photos or video.
- Witness names and contact information, and the other vehicle’s and driver’s details if known.
- Any available information about the other driver’s insurance status.
- For an injury claim, medical visit and treatment records, bills, and documentation of lost wages.
- For vehicle damage, repair estimates, inspection records, invoices, and receipts.
- Claim forms, emails, letters, and a call log with dates, names, and what was discussed.
Keep the original files where possible and note when and how you provided records. The NAIC’s UM guidance, Washington’s crash guidance, and Illinois’ auto insurance guidance support gathering details, keeping photos, cooperating with the investigation, and providing required proof of loss; they do not establish one universal document list.
Rank #4

- Portable & Compact: The car safety kit is designed to fit neatly into an organizer bag, allowing for easy storage in either the backseat or trunk of your vehicle. This ensures that all essential safety items are kept together and easily accessible in case of an emergency. By keeping the kit organized and readily available, you can be better prepared for unexpected situations while on the road
- Fully Prepared: This kit should include essential tools and supplies to help you in case of an emergency. By being prepared, you can feel more secure while driving and have the necessary resources to handle unexpected situations
- Multi-Purpose Emergency Kit: This emergency kit contains everything you need for emergencies. It's suitable for different occasions such as winter weather, commuting and road trips
- Premium Material: The cable surface is covered by PVC material and the interior is made of premium copper wire. The use of premium materials can significantly enhance the overall quality and value of a product. This universal cable is suitable for small vehicles
- Wonderful Car Safety Kit: This kit is ideal for family and friends, especially for teenagers who are about to own their first car. It's a thoughtful and practical present that will undoubtedly be appreciated by the recipient
How to work with the adjuster and protect your records
Respond to reasonable requests, attend an inspection if asked, and keep copies of submitted materials. Ask the adjuster to explain in writing which coverage and policy terms are under review. If your car is damaged, Illinois’ regulator advises showing it to the insurer before repairs and protecting it from further damage. Where practicable, confirm inspection and repair authorization with the adjuster before proceeding.
Keep a simple claim log: the date of each call or message, who contacted whom, what was requested or promised, and the next due date. If a phone conversation changes what you need to do, follow up in writing so you have a record.
Recommended Free Tools
What to do if the insurer delays or denies the claim
First ask the insurer to identify the specific policy wording and facts behind a delay, denial, or settlement decision. Request the explanation in writing and preserve the denial letter, forms, and full communication history. If you cannot resolve the issue through the claims process, you can contact your state insurance department for consumer assistance. The NAIC’s state insurance department directory identifies the regulator for each state; NAIC notes that claim delays and denials are among common complaint reasons.
Best Value
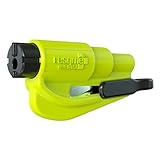
- The original 2-in-1 lifesaving compact emergency car safety tool: this emergency keychain hammer provides peace of mind to yourself and your family on the road in case of car entrapment. Can be used in various situations such as rollover, electrical system failure, car fire, floods, sinking car accident.
- Jammed seatbelt cutter: the razor-sharp, stainless-steel blade allows to cut a jammed seat belt in no time. Slice the seat belt diagonally for a quick and clean cut. Can be used multiple times.
- Tempered glass window breaker: the solid, heavy-duty, stainless-steel spike easily breaks tempered glass car side windows. Hit preferably one of the corners of the window for better result. The resqme is equipped with a spring-loaded mechanism and resets after each use. The resqme is reusable multiple times.
- Easily Accessible, No Installation Required
A regulator complaint is a way to seek assistance with claim handling. It does not itself establish coverage, and it does not replace any applicable policy, arbitration, or lawsuit deadline.
Why prompt reporting matters
Uninsured drivers remain a meaningful risk, but the national estimate is not a prediction about any particular crash. The NAIC reports that 15.4% of motorists—about one in seven—were uninsured in 2023, attributing the figure to an Insurance Research Council study published in 2025. Its state estimates for 2023 ranged from 5.7% in Maine to 28.2% in Mississippi: NAIC’s 2025 summary of uninsured-motorist estimates.
Those figures do not determine whether your own loss qualifies. The practical next step is to notify your insurer, follow your policy’s conditions, preserve evidence, and confirm your claim’s deadlines rather than relying on a general rule.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

