
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
To estimate the federal tax effect of buying business equipment, first calculate the equipment’s eligible business-use basis, then estimate the depreciation deduction available for the tax year it is placed in service. A deduction reduces taxable income; it is not a dollar-for-dollar tax credit. Your actual tax savings depend on whether you can use the deduction and on your overall tax situation.
What you need to estimate the tax effect
A purchase price alone is not enough to calculate a reliable figure. Gather these details before comparing depreciation options:
- The equipment type, purchase cost, and any other costs included in its tax basis.
- The share of its use that is for business, especially if it also has personal use.
- When it was acquired and, more importantly, when it was placed in service—ready and available for business use.
- Your business structure, taxable income, and other relevant tax circumstances.
- The tax year you are estimating and the depreciation treatment the property may qualify for.
The IRS describes depreciation as an annual income-tax deduction that lets a taxpayer recover the cost or other basis of certain property over the time it is used (IRS Publication 946). The applicable year and the property’s eligibility determine how much of that basis may be deducted and when.
Free tools Windows power users keep installed
One-click scans. No signup required.
Calculate the business-use basis
Start with the equipment’s tax basis and identify the portion attributable to business use. Do not automatically treat the entire purchase price as business basis if the equipment also serves personal purposes. For example, if qualifying equipment costs $10,000 and is used 80% for business, the starting business-use basis for a simplified estimate is $8,000. Actual basis and depreciation calculations can depend on other facts and tax rules.
#1 Best Overall
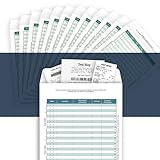
- [Multiple Purpose Business Organizer] Record business expenses on one ledger; Store receipts inside the envelope; Track auto mileage log on the back
- [Match Receipts to Expenses, Find Fast] Record an expense on a line (1-30); Mark the receipt with the line number; Find the receipt fast with the number
- [Receipts Organizer with Expense Ledger] Track your business expenses, prepare for an expense reimbursement or a tax deduction
- [Auto Mileage Log] Track business vehicle mileage; capture valuable business mileage deductions and save on your taxes
- [Perfect Size, Durable Paper Material] Heavy 100 lb paper, easy to write and no ink bleed. This business receipts organizer envelope measures 9.5×6.5 inches, large enough to comfortably fill out while being small enough to fit in a glove compartment, center console or work bag.
Some assets, including certain vehicles and entertainment or recreation equipment, may be treated as listed property. The IRS generally requires more than 50% qualified business use for listed property to qualify for Section 179 or the special depreciation allowance; additional vehicle limits and substantiation rules may apply. Keep records that support the business-use percentage.
Compare the available depreciation methods
Section 179, special first-year depreciation (often called bonus depreciation), and regular MACRS depreciation are not interchangeable labels for the same deduction. They have different eligibility rules and limits, and accelerated deductions affect how much basis remains for later years.
Rank #2

- Great way to organize and store vital tax records
- Instruction sheet/checklist and preprinted labels included
- 12 pockets plus one large pocket in back provides ample storage
- Protective flap and elastic cord closure
- Contains 10% recycled content, 10% post-consumer material
| Method | What it does | Key limits or trade-off |
|---|---|---|
| Section 179 | May allow eligible business property to be expensed in the year it is placed in service. | Subject to an annual dollar ceiling, a phaseout tied to qualifying property cost, a business-income limit, and other restrictions. An amount that cannot be used currently may not produce an immediate tax benefit. |
| Special first-year depreciation | May allow a first-year deduction for a percentage of the basis of qualified property. | Eligibility depends on property and acquisition timing. An election to use a different allowance or elect out may be relevant; do not assume every purchase qualifies. |
| MACRS depreciation | Recovers eligible basis over the applicable recovery period under the depreciation rules. | Generally spreads deductions across years rather than automatically deducting the entire cost immediately. The remaining basis after other depreciation provisions may be subject to MACRS. |
Use the limits for the correct tax year
For tax years beginning in 2026, the IRS Publication 946 (2025 edition) lists a maximum Section 179 deduction of $2,560,000. That ceiling is reduced by qualifying Section 179 property cost exceeding $4,090,000. Certain SUVs have a separate $32,000 maximum for tax years beginning in 2026. These are deduction limits—not amounts of tax saved—and other restrictions, including the business-income limit and vehicle rules, may apply. See the IRS’s Publication 946, “What’s New for 2026”.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
For certain qualified property acquired and placed in service after January 19, 2025, Publication 946 describes a 100% special depreciation allowance. Qualification and elections matter, so this is not an automatic write-off for every equipment purchase. The publication also describes a 40% allowance election for certain qualified property in the first tax year ending after January 19, 2025, and a different 60% provision for long-production-period property and certain aircraft. Apply those alternatives only when the taxpayer’s facts make them relevant. See IRS Publication 946 and the IRS’s summary of depreciation changes.
Rank #3

- ✅ ALL-IN-ONE RECEIPT ORGANIZERS - Stop drowning in loose receipts! PocketCPA 3-in-1 Receipt Organizer Envelopes make tracking expenses & mileage completely effortless. 12 monthly envelopes = audit-proof records and tax prep all year long.
- ✅ RECEIPTS AT YOUR FINGERTIPS! - Our Smart Indexing System developed by PocketCPA matches every expense entry to its supporting receipt and provides instant access to receipts when needed.
- ✅ BUILT-IN EXPENSE LEDGER + AUTO MILEAGE LOG -Easily record business expenses and deductible business mileage right on your PocketCPA organizer. Ideal for documenting business expense deductions and travel reimbursements, whether needed for accounting, bookkeeping, finance, expense reimbursements or IRS or state tax audits.
- ✅ PERFECT FOR HOME, OFFICE & TRAVEL – Lightweight and portable, each 9.5" x 6.5" organizer can be easily stored or transported, helping you keep receipts and expense records organized wherever you work or travel.
- ✅ IRS AUDIT PROTECTION! - It's easy to locate any and all receipts if you need to produce them to IRS to support a tax deduction - because PocketCPA Organizers let you organize and locate your business receipts.
For comparison, the publication lists a $2,500,000 Section 179 maximum for 2025, with the phaseout beginning when qualifying property placed in service exceeds $4,000,000. Do not use those 2025 amounts for a 2026 estimate. The rules depend on the tax year and the property’s timing; check the IRS guidance for the year the equipment is placed in service.
Estimate the deduction, then estimate the tax savings
After determining the potentially available deduction, assess whether it can actually be used in the year you are estimating. Section 179’s business-income limit and other taxpayer-level rules can affect current use. Partnerships and their owners may face additional allocation and taxpayer-level rules. The deduction may also change other parts of the tax calculation.
Rank #4

- Comprehensive Tax Package Inclusions: The pack includes 1 all in one income tax organizer, 1 sheet of tax category pre printed label sticker, 1 common tax category list, 12 alphabet labels, giving you everything you need for tax preparation
- Build to last: Our tax record organizer is mainly made of plastic, waterproof, tear resistant, and resistant to deformation, while maintaining flexibility, secure button closure design facilitates access and placement of documents while ensuring safe placement of documents, and the closed bottom keeps the file in place
- Large capacity: This tax document organizer has 13 pockets, each holding about 40 sheets of paper, it can be flexibly expanded and shrunk as the number of files increases, holding a total of about 500 sheets of paper, ideal for organizing and protecting important documents, paperwork, bills, tax records, receipts, invoices and more
- Pre Printed Labels and Customizable labels: these pre printed label stickers have common tax categories, such as Medical Expenses, Employment Income, Rental Income, and more, we also included alphabet labels and customizable labels for your personal uses, please note that the customizable labels do not come with adhesive
- Broad uses: this expandable file folder organizer is proper for organizing various financial and tax related documents, with strippable labels and divider labels for sorting, making your tax preparation more systematic and managed, ideal for annual tax returns, document storage and filing, professional tax services, and tax agencies
- Find the eligible business-use basis. Adjust the equipment’s basis for business use and applicable eligibility rules.
- Identify the placed-in-service tax year. Use the rules and limits for that year, not simply the year you paid for or ordered the equipment.
- Estimate the deduction under each eligible method. Consider Section 179, special first-year depreciation, and MACRS, including any relevant elections and limits.
- Estimate the portion usable this year. Account for income limits and other restrictions before treating a potential deduction as a current-year tax benefit.
- Estimate the tax effect in context. Multiplying the currently usable deduction by a marginal tax rate is a rough illustration, not a complete tax-return calculation.
- Compare the timing. Consider deductions left for later years and the effect of the choice on your overall tax position.
Hypothetical illustration: Suppose qualifying equipment costs $10,000, is used 80% for business, is placed in service in 2026, qualifies for a chosen method, and the taxpayer can use the resulting deduction in full that year. The simplified business-use basis is $8,000. If the estimated currently usable deduction is $8,000 and an assumed marginal tax rate is 24%, multiplying them gives $1,920 as a rough illustration of the income-tax effect. This is not a guaranteed saving or a complete return calculation: the assumed rate, deduction, ability to use it, and other tax facts all matter.
Decide whether faster deductions fit your situation
The largest first-year deduction does not necessarily produce the best overall result for every taxpayer. Accelerating depreciation changes the timing of deductions and reduces basis available for future depreciation. Compare the options using the facts that determine both current use and later-year effects:
Best Value
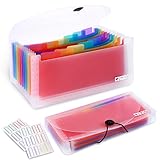
- 2 Pack 13 expanding pockets, colored tabs for easy subdivision and indexing, help to effectively classify documents
- Use high environmental quality and safety material, water and pressure resistant, not easily broken and deformed
- About 10.2 x 5.1 x 0.8 inches, available for receipts, coupons, tickets, vouchers, checks, notes, business cards and bills
- Buckle design, effectively protect the contents of documents and prevent documents from falling off
- Easy to use and easy to carry, suitable for daily archiving and storage, is a good helper for office, student and business travel
- Whether the equipment qualifies for each method.
- The deduction available for the current year and any annual or property-specific limits.
- Whether business income and taxpayer-level rules allow the deduction to be used now.
- The basis and deductions that remain for future years.
- How the choice affects the taxpayer’s overall federal tax position.
State tax treatment is a separate question. Federal rules do not establish whether a state follows the same depreciation treatment. This estimate also does not include sales tax, financing costs, tax credits, or an individual taxpayer’s final liability.
When to get individualized tax advice
A CPA or enrolled agent experienced with depreciation can help evaluate eligibility, elections, business-income limits, mixed use, vehicle restrictions, and the interaction between federal and state treatment. That advice is especially useful when the purchase is large, the equipment has personal use, or the business has multiple owners.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

