
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
There is no single credential holder across AP2, ACP, and x402: each protocol addresses a different part of an agentic payment. AP2 assigns a Credential Provider to supply and scope payment credentials; ACP describes checkout data and merchant processing, including delegated tokens; x402 prompts a client to pay for an HTTP request, with wallet custody determined by the implementation.
What does “holds the credential” mean?
The answer depends on which payment object you mean. An underlying card or wallet credential, a token delegated for a particular payment, an authorization mandate, and a wallet’s signing key are not interchangeable. A protocol may define who supplies or verifies one object without specifying who controls every other object in the flow.
That distinction matters here: AP2 makes credential authorization and transaction evidence explicit; ACP focuses on checkout and payment data passed to a merchant; x402 defines a request-level payment exchange.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minuteHow does AP2 handle credentials?
In the AP2 specification, version 0.2, the Credential Provider (CP) is the source of payment credentials for a purchase. It verifies that the agent is authorized to access a credential appropriately scoped to the payment. This is a protocol role, not a claim that a particular wallet or company must fill it.
#1 Best Overall

- Generous Quantity and Standard Size: The package contains 40 pcs NTAG215 NFC cards, the card size is 85x54x0.8MM, same as credit card. Easy to take along like NFC tags, convenience for smart office and smart home
- High-Quality Material and Durability: NTAG215 Chip and brand-new PVC, the chip has 504 bytes usable storage, it's steady to write and read, safe to store the data, long timelife (100,000 times). The new PVC are non-toxic, lead-free material. The cards are tough, durable and waterproof
- Wide Range of Applications: The NFC card are widely used for now days life. Such as: access Control cards for smart lock, control cards for smart home/office appliance, points cards for loyalty program, value cards, gift cards, electric Business card, or Gaming cards (the cards are compatible with Amiibo and Tagmo)
- Simple Programming and Reading: With the NFC relative apps of nfc functional smart phones or other devices, the card can be written or read when hovering close to the device
- Customizable Printable Surface: These cards have shiny surface by full coating a layer oil, they can be printed by ribbon cards printer. Also can be written by mark pen. It's easy to make your custom designed access card, business card or gaming card
Mandates authorize the payment
AP2 distinguishes the credential from the authorization to use it. A Payment Mandate authorizes payment against a specific payment instrument and is shared with the Credential Provider, payment networks, and the merchant’s payment processor. The Credential Provider checks the agent’s authorization and credential scope. The merchant checks the checkout, while its payment processor checks whether the credential is authorized for that checkout.
AP2 also links checkout and payment mandates and receipts to provide verifiable transaction evidence. The mandate is therefore evidence of authorization, not the payment credential itself.
Rank #2

- 13.56MHz PROTECTION FOR CARDHOLDERS – Magriffin RFID blocking card helps interfere with unwanted contactless scans of compatible credit cards, debit cards and e-passports. Designed for people who want added protection inside the wallet or passport holder they already carry
- VERIFY RFID BLOCKING WITH AN EASY SELF-TEST – Turn invisible protection into something you can check. At a compatible tap-to-pay terminal, confirm your payment card reads alone, tap again with the blocker directly against it, then remove the blocker and confirm normal reading returns
- CLEAR PLACEMENT FOR MORE RELIABLE PROTECTION – Position one credit card scan blocker close to the contactless cards you want to protect. Because distance, card position and wallet layout can affect RFID blocking performance, repeat the self-test after moving the blocker or rearranging your cards
- 0.029-IN ULTRA-SLIM WALLET FIT – At only 0.029 in (0.74 mm), these RFID cards for wallet use are slightly thinner than a standard credit card. Each passive RFID blocking card fits into a regular wallet without batteries, charging or switches and has been durability-tested for more than three years
- PROTECTION FOR DAILY CARRY, TRAVEL AND CROWDED PLACES—3 PACK – Place the three RFID blocking cards in different wallets or card groups, or share them with family. They help protect credit cards from scanners while commuting, shopping or traveling and are backed by a Magriffin lifetime warranty
How does ACP handle checkout payment data?
ACP describes a merchant checkout interaction. Its checkout payment data includes a payment token and a provider, and the merchant processes the payment through its existing payment service provider (PSP). Its payment-handler RFC describes delegated credential flows, including Shared Payment Tokens.
A delegated token should not be confused with the underlying card or wallet credential. The token may be the payment data passed for a checkout, while the underlying instrument remains a separate object. ACP’s documented focus is how the checkout and payment handoff work; the available description does not establish a universal rule about who custody-controls every underlying credential.
Rank #3

- FREE FOREVER, NO SUBSCRIPTION: Other NFC business cards charge you a monthly fee to keep sharing. Blinq doesn't. Share your digital card and manage unlimited contacts with context, at no ongoing cost, on any iPhone or Android.
- YOUR BRAND, YOUR CARD: Add your logo, links, colors, and photos, and make the card unmistakably yours. Update your details anytime in the Blinq app, so you'll never need to reprint when something changes.
- TAP TO SHARE INSTANTLY: Tap your card or scan the QR code, and your profile lands on any iPhone or Android in seconds. Ask for theirs back and Blinq saves it automatically, with context, no typing required.
- NO APP NEEDED FOR THEM TO RECEIVE YOUR CARD: Whoever you meet, they don't need the Blinq app or a Blinq card of their own. A tap or a scan, and your details are on their phone, every time.
- MORE THAN A DIGITAL CARD: Scan a paper card, use the AI notetaker to summarize your conversation, and let Blinq enrich the contact so nothing about that meeting slips away. This is the AI contacts app for people who meet people, free from day one.
How does x402 handle payment?
x402 centers on an HTTP request. When a request arrives without payment, the server responds with HTTP 402; the client pays and retries the request. The payment challenge is tied to access to that request or resource, rather than to an AP2-style mandate structure.
x402 is wallet-based, but the protocol does not establish one universal wallet custodian or key-management arrangement. Those details depend on the wallet and implementation. A payment request or challenge is not itself proof that the server holds the client’s wallet credential.
Rank #4

- [NTAG 215 Chip] Black NFC tags card are equipped with a high-quality NTAG215 chips, providing 504 bytes of available NDEF memory.Business card provides ample storage space for quickly writing and storing the information you desire. The NFC cards also feature a read-write lock function,allowing you to choose between repeated editing or setting them as read-only tags.Once set as read-only, the information cannot be edited or reset, ensuring data security.
- [Quality Materials] 20pcs NFC Tags NTAG215 NFC Cards are made of high-quality PVC material.The waterproof PVC material can perfectly protect the internal chip. The surface is smooth and shiny,while also providing a printable surface for your personalization, the sturdy material prevents wear and tear,ensuring a professional appearance and long-lasting performance.
- [Proper Sizes] The size of 20pcs pvc cards is 3.36 x 2.12 x 0.03 inches / 85.5*54*0.86mm,blank nfc cards is the right size for various card printing applications, 20 pieces can be used and backed up for quite a long time.Our NFC Tags Cards are the ultimate solution for simplifying your daily routines.
- [Easy to operate] NFC tags card is fit for most printing heat transfer machines,making it easy for even non printing experts to operate. The simple process ensures that you can easily produce professional grade cards.Tip:Not suitable for inkjet printers.
- [Boost productivity] Unlock a world full of possibilities with our NFC Tags. The potential is limitless,from creating personalized shortcuts for your favorite applications to triggering specific actions on smart devices.Use rewritable NFC tags to improve your work efficiency and automate repetitive tasks.
How do the three approaches compare?
| Protocol | Primary payment object or flow | Credential-related role | Merchant or server role |
|---|---|---|---|
| AP2 | Mandate-based authorization linked with checkout and payment evidence | Credential Provider supplies credentials and verifies agent authorization and scope | Merchant checks checkout; payment processor checks credential authorization for that checkout |
| ACP | Merchant checkout with payment data, including a token and provider | Payment-handler RFC describes delegated credentials, including Shared Payment Tokens | Merchant processes payment through its existing PSP |
| x402 | HTTP 402 payment challenge followed by payment and request retry | Wallet custody and key management depend on implementation | Server requests payment for a request or resource |
Can AP2, ACP, and x402 be combined?
They are not necessarily competing alternatives. AP2 addresses authorization and evidence, ACP describes commerce checkout interactions, and x402 handles payment exchange at the HTTP request level. AP2 documentation includes an autonomous x402 payment example, showing that AP2 and x402 can be composed. That example does not establish that every ACP, AP2, or x402 deployment interoperates automatically.
What should developers verify before choosing a flow?
- Identify the object: Specify whether the design concerns an underlying instrument, a delegated token, an AP2 mandate, or a wallet key.
- Set authorization boundaries: Determine how agent permission, credential scope, and any spending limits are represented and checked.
- Map each handoff: Record what the agent, credential provider or wallet, merchant or server, and payment processor each receive and verify.
- Choose the interaction shape: Use the protocol whose documented flow matches the task: mandate-linked authorization, merchant checkout, or payment for an HTTP request.
- Check the implementation and version: AP2’s cited specification identifies v0.2; ACP checkout and payment-handler materials are evolving documentation, and the x402 site surfaced a V2 announcement. Confirm current interfaces and integration details in the relevant protocol documentation.
Official documentation establishes these protocols’ design roles and sample implementation surfaces, not market-wide adoption, transaction volumes, or comparative real-world security performance. It also does not establish universal merchant or network availability by geography.
Quick Recap
Best Value
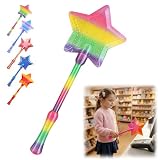
- Magical Credit Card Wand: Insert your contactless credit/debit/gift card into the hidden slot. Wave this magic fairy wand credit card holder with star tip over payment terminals for instant payments, no wallet‑digging needed.
- Tap to Pay Wand: This credit card wand tap to pay features a cute star‑wand design, ergonomic 14‑inch 3D‑printed handle with fade‑resistant gradient. Lightweight, sturdy, it securely hides and protects your cards for long‑term use.
- Easy‑use Wand Credit Card Holder: This star‑shaped wand for credit card has a hidden anti‑slip slot for one contactless card. Kids & adults wave it for tap‑to‑pay, adding fun to daily shopping.
- Versatile Wand for Credit Card Tap: This fun twinkle wand credit card builds kids’ money awareness and sparks imagination. Turn payments into magical adventures, great for all‑ages star wand credit card holder.
- Convenient Magical Experience: This debit card wand works for contactless payment. Use this fairy wand tap at self‑checkouts, shops or terminals for fun tap‑to‑pay, blending finance and fantasy.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

