
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
First identify whether the problem is KYC, a rejected transfer, a debit without credit, or a return: the right fix and deadline depend on the bank, account, currency, and payment rail. Record the exact error, date and time, amount, debit status, and transaction reference. For KYC, ask the account-holding bank for the specific deficiency and accepted remedy; for a payment, ask the sending bank to trace the reference and confirm where the funds are.
Identify what failed before taking action
“GIFT City account” does not identify one bank, one account type, or one payment route. The relevant institution may be the sending bank, the receiving GIFT City International Banking Unit (IBU), or—on a cross-border wire—an intermediary bank as well. Start with the actual failure stage, not an assumed cause.
| What happened | Who to contact first | What to establish |
|---|---|---|
| You cannot add the beneficiary | The bank whose app or portal you are using | Whether the beneficiary details and selected transfer route match the receiving bank’s official instructions. |
| The instruction was rejected before debit | The sending bank | The exact rejection reason and whether a new instruction can safely be made. |
| Your account was debited but the beneficiary was not credited | The sending bank | Whether payment was sent, is under review, rejected, or returned, and which bank currently holds the funds. |
| The transfer shows as returned | The sending bank | When the return reached it and when it will reverse the debit. |
| The payment is pending or under compliance review | The bank showing the pending status | What review is outstanding and whether the payment is still in flight. Do not send it again until the bank confirms the first instruction’s status. |
| Account operations are restricted while KYC is outstanding | The account-holding bank | Whether the restriction is temporary, what must be supplied, and what steps restore operations. |
Keep the bank name, account type, currency, amount, date and time, exact error text, transaction reference or UTR, and whether the sending account was debited. Save confirmation screens and debit entries. Share account details only through the bank’s secure channel, not in public posts.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Scan for outdated or missing drivers - takes under a minute3Repair Windows errors before they cause bigger problemsIf your GIFT City account KYC verification failed
Get the precise deficiency and the right submission route
Contact the bank through its official secure channel, branch, or relationship-manager contact published for that IBU. Do not send identity documents to an email address or phone number from an unsolicited message. Ask whether this is initial onboarding, periodic re-KYC, or a restriction on an existing account, and request the rejected item, reason, accepted replacement or certification, file format, and submission channel in writing.
#1 Best Overall

- 【High Quality travel passport holder】This passport wallet and passport book holder is made of super strong and durable polyester fabric, waterproof and stain resistant, lightweight material for easy carrying, strong zinc alloy zipper makes it more durable; Rfid passport wallet looks very attractive design, can be a great passport holder wallet choice for men, women, friends and family.
- 【Rfid Blocking Protective passport bag】Family passport holder for 1 2 3 4 5 6 can effectively protect your card from being scanned, including 4+2 passport pockets, 1 boarding pocket sleeve, 1 transparent pocket, 1 quick access pocket, 1 pen holder, 2 zipper cash pockets, 6 Card slots, a coin mesh pocket and detachable key chain.
- 【Not easy to crack travel accessories】This passport wallet for women has an exterior zipped pocket where you can fit things like your phone or tickets. Every time you use your travel passport wallet, boarding pass, ID or other documents, the family passport holder is strong and won't rip easily. It's perfect for airports, crowded markets, buses, trains, sporting events and festivals
- 【Perfect travel pouch for passport and documents】Dimensions: (5 inches x 9 inches x 0.78 inches), The Family Travel Document Organizer Easy to Organize: Plenty of room for your travel essentials like passport, boarding pass, ticket, invoice , pen, checkbook, money, coins, keys and shipping documents.
- 【Document holder for traveling】Our travel document holders are not only travel organizers but also family travel document organizers and credit card clutches. This spacious letter-sized travel organizer, sleek and modern multiple passport holder is designed for travel and durable enough to carry essentials for short or long trips.
To help the bank diagnose the issue, ask whether it concerns the document type or expiry, a name or address mismatch, an unclear copy, missing certification, a signature or photograph/video check, tax-residency or FATCA-CRS information, or another bank-specific review. These are questions to investigate, not established causes of your particular rejection.
Check what certification the bank accepts
IFSCA’s KYC verification guidance describes offline identity verification by examining original documents or using certified true copies. For non-resident individuals, it lists possible certifiers including an authorized bank official in a FATF-compliant jurisdiction, a notary, court magistrate or judge, certified public or professional accountant, lawyer, or the relevant embassy or consulate. That does not mean every bank accepts every route for every account. Get the applicable route from your bank before paying for certification or resubmitting documents.
Rank #2
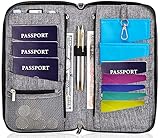
- DESIGNED BY TRAVELERS FOR TRAVELERS unique, Smartly designed, elegant high capacity document holder. Removable wristlet and cross body straps allow choosing the desired type of wearing and usage
- THE MOST SPACIOUS Letter Sized TRAVEL ORGANIZER EVER. Designed specifically for large families or groups of travelers. 6 passport pouches, 2 pockets for boarding passes for passengers flying with connection, 2 zippered big pockets for cash, 2 latter size stash pockets for documents, external zippered phone pocket… Totally 21 pockets and slots
- BE COOL YOUR DOCUMENTS ARE SAFE. Manufactured from 100% Premium RFID protected WATER RESISTANT material with tight lining will guaranty safety of your documents in any weather
- It is Not Just a Passport Wallet where you can put only few passports and cards. It’s real capacious letter sized travel organizer were all your travel necessities will be in one place
- NO DOUBTS - BUY IT NOW 1- year warranty, friendly customer support 24/7. 60 days money back guarantee
Ask whether a KYC issue has affected account access
Requirements and consequences vary by bank. HDFC Bank’s GIFT City account terms describe requests for identity, address, photograph, and other information, periodic document updates, and possible partial freezing for KYC non-compliance; the terms also allow for a freeze or account closure if requirements remain unmet. These are HDFC’s published terms, not a universal description of every IBU’s policy. Ask your own bank whether any restriction currently applies and what it requires to lift it.
Free tools Windows power users keep installed
One-click scans. No signup required.
One bank’s process should not be treated as another’s. For example, ICICI Bank’s GIFT City customer update form says a successful KYC verification updates re-KYC status at customer-ID level and regularizes account operations. It illustrates that institution’s workflow; it does not promise instant reinstatement at other banks.
Rank #3

- Fire Resistant: Our fireproof important document organizer protects your files. Fireproof accordian file organizer consists of three layers of fiberglass coated with silicone resin and can withstand temperatures up to 2000°F
- Water Resistant: Document storage folder is extremely waterproof, making it ideal for accidental spills or accidents(the zipper edges are not waterproof). Our fireproof file organizer will keep your files easily accessible and organized
- Humanized Handle: This accordion file folder organizer has a handheld design that is soft to the touch and can also hold heavier files as it has a wide handle strap to keep your hands safe and help you carry your files around with you
- Colorful Labels & Double Zipper: The labels help you to classify your files effectively . You can quickly find what you need.Simplify your work and save a lot of time.Document organizer folio has a double zipper for convenient opening and closing
- Enough Space: 14.1 “x11.4 ‘x2’. Our folio document organizer has 1 zippered pockets, 1 pen slots, 4 SD card slots, 13 label pockets(Fit Letter or A4), 6 card pockets, 4 medium mesh pockets and 1 main large pocket
If a GIFT City transfer failed, was delayed, or was debited without credit
Ask the sending bank to trace it
Use the bank-generated UTR or transaction reference and ask the remitting bank to confirm whether the instruction was accepted, sent, rejected, returned, or remains under review. If sent, ask whether the receiving bank has returned the money and when the originating bank will reverse the debit. Verify the beneficiary account number and applicable IFSC, SWIFT, IBAN, or other routing details against the receiving bank’s official instructions.
RBI has directed banks to provide a beneficiary-name lookup for RTGS and NEFT using account number and IFSC. If your bank’s interface offers it, compare the displayed name before initiating payment. Availability and display depend on the bank’s implementation, and a name match does not verify every other detail. See the RBI direction on beneficiary name look-up.
Rank #4

- Ultimate Fireproof & Water-Resistant Protection: Keep your valuables safe with our DocSafe Hard-Shell fireproof file organizer. It is made of thickened silicone coated fireproof heat insulated cotton material and hard-shell material which can stands up against fire and passed the UL94 -V0/5VA flame retardant test. Fireproof box is both fireproof and water-resistant, ensuring your documents stay protected during fires, floods, or wet weather. It may fit both letter and legal-size files
- Upgraded Hard-Shell Design Fireproof Box: Our fireproof document box combines hard-shell construction with fireproof materials, offering unmatched protection and durability. Unlike traditional soft case, our design withstands extreme conditions while maintaining a sleek, professional look. The Non-dusty material actively repels dust,hair and stains, keeping your box clean and tidy for years. It’s the ultimate solution for safeguarding your important documents, laptop, and valuables
- Large-capacity: Outside size: 15.5" x 11.5" x 3"(Thickness can be expanded up to 4"). Our Accordion fireproof document box adopts a multi-layer design that can meet all your storage needs. These include 13 accordion Pockets with labels,1 zipper pocket,4 pen slot,14 card slots,4 passport holder,4 small mesh bags,2 mesh bags,and 1 main pocket. It can store your important documents,money,passport,U Disk,cards,laptop,certificates in a safe and orderly way. Perfect for daily file filing and storage
- Fireproof File Organizer with Lock: Protect your valuables with the built-in high-quality combination lock (No keys required). Featuring a double metal zipper for convenient opening and closing. Design with a strong handle for carrying everything you needed easily. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place. Of course, giving it as a gift to your family is also a good choice
- Trusted after sales service: Nothing is completely foolproof, but added protection is always a good idea. In an emergency, our fireproof document organizer ensures your files stay intact, giving you time to save your important documents. It is lighter, easier to carry than fireproof safes and quick to grab and go. If there any quality problem, please feel free to let us know. We are committed to solving your problem immediately, your suggestion has a great impact on the upgrade of our products
Apply a deadline only after confirming the payment rail
Ask the bank which rail actually carried the payment. “GIFT City transfer” alone does not tell you whether RBI’s RTGS or NEFT deadlines apply; other payment systems and cross-border legs have different processes.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
| Confirmed rail | What RBI says when the beneficiary cannot be credited | What to ask the bank |
|---|---|---|
| RTGS | The receiving member bank should return funds to the originating bank within one hour of receipt at the payment interface or by the end of the RTGS business day, whichever is earlier. Once the originating bank receives the return, it must reverse the customer’s debit. Delayed return can attract compensation at the current repo rate plus 2%. | When did the receiving bank or payment interface receive it? Was it returned, and when did the originating bank receive the return? |
| NEFT | The receiving bank should return an uncreditable payment within two hours after settlement of the relevant batch. RBI’s FAQ describes penal interest for delayed credit or return at the current RBI LAF Repo Rate plus 2%. | Which batch settled the payment? Was it credited or returned within the stated window? |
| Another rail or a cross-border wire | Do not apply the RTGS or NEFT timing by analogy. Deadlines depend on the actual system and transaction category. | Which payment system and any intermediary banks were involved, and what rule or status applies? |
The RTGS and NEFT timings and rate formulas above are from RBI customer FAQs accessed in 2026; the pages do not show a clear publication date in the available search results. They apply only to the relevant confirmed rail. RBI’s failed-transactions circular includes T+1 reversal and ₹100 per day beyond the deadline for specified categories, including certain card-to-card and IMPS cases. Those figures are not a general deadline or compensation rule for every transfer. Confirm the exact transaction category and applicable current guidance with the bank.
Quick Recap
Escalate with a written record
- Complain to the bank responsible for the issue. For a debit without credit or transfer trace, start with the remitting bank. For rejected KYC, start with the account-holding bank.
- Request a complaint number and written status. Include the reference, relevant dates, and a concise account of what happened. Ask which team is handling it, what action is pending, and when you should expect an update or return.
- Use the bank’s grievance route if the first contact does not resolve it. Keep copies of the complaint and the bank’s replies.
- Check whether RBI’s Integrated Ombudsman Scheme applies. RBI’s RTGS and NEFT customer guidance describes escalation under RB-IOS when a grievance remains unresolved within 30 days. Eligibility depends on the entity and scheme requirements, so confirm that your case qualifies rather than assuming the scheme covers every institution or issue.
What to have ready when you contact the bank
- Bank and IBU name, account type, and currency.
- Exact error or status text, plus when and where it appeared.
- For a payment: amount, date and time, UTR or reference, beneficiary details entered, debit proof, and any return or status notice.
- For KYC: the bank’s message, the document or field it rejected, and whether this is onboarding or re-KYC.
- Your complaint number and copies of written replies.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

