
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
At Wednesday’s close in the October 9, 2026 snapshot, SpaceX was valued at about $2.27 trillion, roughly $800 billion more than Tesla’s $1.49 trillion. Yet SpaceX had about $23 billion in trailing-four-quarter revenue, compared with Tesla’s $104 billion. The gap is not a claim that SpaceX already sells more or earns more overall: it reflects what investors are paying for each company’s current sales and what they expect its businesses to become.
What the comparison measures—and what it does not
The figures compare market values at a specific Wednesday close with revenue over the latest four quarters cited by The Motley Fool. They are a dated market snapshot, not live prices: market capitalizations change as share prices move. In that snapshot, SpaceX’s value was about 99 times its trailing sales, while Tesla’s was about 14 times. These are price-to-sales comparisons, not earnings multiples, and they do not by themselves establish either company’s future performance. The Motley Fool’s October 2026 comparison provides the market and revenue figures.
The headline’s “$800 billion more” means SpaceX’s public-market value exceeded Tesla’s by roughly that amount. It is distinct from a widely reported 2025 proposed insider share sale that implied an approximately $800 billion valuation for SpaceX before its IPO. SpaceX priced its IPO at $135 per share in June 2026 and later reported about $85.7 billion in gross proceeds from the full issuance. Those are historical IPO figures, not the basis for the later market-cap comparison. Bloomberg’s 2025 report, SpaceX Investor Relations, and SpaceX’s 2026 SEC filing describe the earlier sale and IPO history.
Why investors may value SpaceX so highly
Investors price future possibilities as well as current sales. SpaceX combines launch services with Starlink connectivity and an AI business, giving investors several potential growth engines—but also different cost structures and execution risks. Its Q2 2026 filing reported $7.8 billion in quarterly revenue, up 91.9% year over year. SpaceX attributed the increase to AI infrastructure contracts, Connectivity growth as Starlink subscribers and enterprise and government customers expanded, and growth in its Space segment. The company reported a $541 million quarterly net loss. SpaceX’s Q2 2026 Form 10-Q and earnings materials provide the company’s reported results.
#1 Best Overall

- 1:200 Scale SpaceX Starship Model: This NikolaToy model offers a precise 1:200 scale replica of the SpaceX Starship, showcasing a realistic design for aviation and space enthusiasts.
- LED Lights & Misting Effect: Equipped with LED lights and a misting function, this model creates a dynamic and interactive experience, simulating rocket exhaust in a unique way.
- Durable PLA+ Construction: Made from PLA+, a strong and eco-friendly material, ensuring a sturdy, long-lasting model with fine detailing.
- Precision 3D Printing: Crafted with high-precision 3D printing technology to capture every detail of the SpaceX Starship, from its sleek body to the intricate features.
- Ideal Gift for Space Enthusiasts: A perfect gift for space lovers, engineers, or collectors, adding both a decorative touch and an engaging conversation piece to any home or office.
Connectivity: a growing business with substantial operating income
SpaceX’s Connectivity segment is primarily Starlink, serving consumer, government, aviation, maritime, and enterprise customers. The Motley Fool’s calculation puts its operating income at about $5.3 billion over the latest four quarters, compared with about $4.4 billion for all of Tesla over the same period. It also reports that Starlink’s subscriber count doubled to 12 million. These are segment-level and subscriber figures, not a claim that Connectivity’s operating income equals SpaceX’s consolidated profit. SpaceX’s filing provides the underlying segment and subscriber disclosures; the comparison and calculation are from The Motley Fool.
AI: large ambitions, but current operating losses
SpaceX describes its AI segment as including Grok and X subscriptions, as well as AI infrastructure and cloud services. The Motley Fool reports that the segment lost $3.7 billion from operations in the first half of 2026. That loss is important context for a high valuation: the market may be assigning value to future AI growth, but growth expectations are not current earnings. The size and timing of any improvement remain uncertain.
Rank #2

- Name:1:233 Falcon 9 Block 5 Material::Alloy+resin
- Size:Approximately 22x7cm (8.6*2.7inch) Function: Static desktop display
- For collection or display, Not suitable for children to play with Handmade, there may be minor flaws
- Model is a highly Simulated SpaceX Falcon9 Dragon+F9 Starship Heavy Falcon Falcon 9 Biock 5 rocket model. The main body of the first-stage rocket is precision aluminum alloy tube, and the rest of the rocket materials are made of high-quality imported resin-with excellent laser forming ability and long-lasting preservation
Space: launch and development services
SpaceX’s Space business covers launch and development services. It is a different kind of business from recurring satellite subscriptions or AI infrastructure contracts, so consolidated revenue growth alone does not show which activities are driving results or what their margins will be. The company’s segment definitions and Q2 disclosures are in its Form 10-Q.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Scan for outdated or missing drivers - takes under a minute3Clear out junk files and repair common Windows errorsWhy Tesla’s lower sales multiple does not mean the same thing as a lower-growth business
Tesla’s trailing revenue was much larger in the cited comparison, but investors may be valuing more than its current vehicle and energy sales. The Motley Fool frames Tesla’s valuation as reflecting expectations around autonomy and robotics. Those are expectations, not results guaranteed by the revenue figures. Tesla also faces reported margin pressure, so its larger sales base should not be confused with a guarantee of stronger future profits.
Rank #3
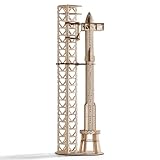
- HANDS-ON ENGINEERING EXPERIENCE: Build this detailed 3d puzzle for adults and explore the complex engineering of the legendary SpaceX Super Heavy booster. A truly immersive dive into aerospace technology
- IMPRESSIVE DISPLAY MODEL: Once completed, this highly detailed and cool-looking model makes a perfect decorative centerpiece for your office, study, or game room, showcasing your unique interests
- SATISFYING MENTAL CHALLENGE: Enjoy hours of focused, relaxing fun. This 3D puzzle provides the perfect level of difficulty, offering a great sense of accomplishment upon completion
- THE PERFECT GIFT IDEA: An unforgettable and inspiring gift for birthSpace-X Falcon Heavydays, holidays, or any occasion. Ideal for space enthusiasts, model kit fans, teens, and adults who love a good challenge
- PREMIUM & SAFE MATERIALS: Made from high-strength, eco-friendly materials with precisely cut pieces for a smooth build. The finished model is robust and durable, designed for long-term display
The companies are not financially unrelated. Tesla’s Q2 2026 filing says it invested $2 billion in SpaceX common stock in March 2026 for less than 1% ownership. Tesla also recognized $318 million of revenue and $242 million of cost of revenue from SpaceX Megapack purchases during Q2. These ties matter when considering the companies’ accounts, but they do not make the two businesses a single company. Tesla’s Q2 2026 Form 10-Q reports the investment and related sales.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.What the valuation gap asks investors to believe
A much higher price-to-sales multiple means the market is assigning greater value to each dollar of SpaceX’s current revenue. For that premium to be justified over time, investors would generally need to see some combination of continued rapid revenue growth, attractive future margins, and successful execution of the company’s plans. The cited results offer evidence of fast growth in Q2 and meaningful Connectivity operating income, but they also show a consolidated quarterly net loss and substantial AI operating losses. Neither growth nor an AI turnaround is assured.
Rank #4
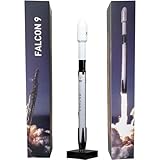
- Name:1:233 Falcon 9 Material::Alloy+resin
- Size:Approximately 28x2.4cm (11*1.5inch) Function: Static desktop display
- For collection or display, Not suitable for children to play with Handmade, there may be minor flaws
- Model is a highly Simulated SpaceX Falcon9 Dragon+F9 Starship Heavy Falcon Falcon 9 Biock 5 rocket model. The main body of the first-stage rocket is precision aluminum alloy tube, and the rest of the rocket materials are made of high-quality imported resin-with excellent laser forming ability and long-lasting preservation
The Motley Fool interpreted Elon Musk’s August 2026 Q2-results call as a sign that investors were underestimating Starlink, quoting him as saying, “I think people are really underestimating Starlink here.” That is Musk’s view as reported by the publication, not an independently checked transcript or a guarantee of future Starlink results. The same article interprets Tesla’s valuation as incorporating autonomy and robotics expectations; those, too, are uncertain. The Motley Fool article gives these interpretations and the attributed quote.
Quick Recap
Best Value
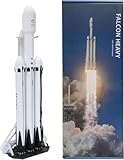
- Extremely exquisite Falcon Heavy rocket model (For collection or display, not a toy! Children should not buy it)
- This model is a highly simulated SpaceX Falcon Heavy rocket model. First-stage super heavy-duty booster is made of precise aluminum alloy tubes.Second-level starship is embedded with reinforced aluminum alloy tubes
- The proportional model:1:233
- Actual height: 32cm (the core diameter is 24mm, the real rocket is 9 meters in diameter) This ratio is the best choice for desktop placement
- Note: This model is not a toy model, it is not recommended to buy for children, please buy with caution to avoid unnecessary trouble for your shopping
How to read the headline without overreading it
- It is a valuation comparison: SpaceX’s market capitalization exceeded Tesla’s at one specified close; it is not a comparison of share prices or total company sales.
- It uses different-sized revenue bases: SpaceX’s roughly $23 billion and Tesla’s roughly $104 billion are trailing-four-quarter figures in the same cited snapshot.
- It is not a profit ranking: Connectivity’s reported operating income is one segment metric, while the companies’ consolidated and other segment results tell a broader story.
- It embeds expectations: Starlink growth, AI economics, autonomy, and robotics may affect investor views, but none should be treated as a guaranteed outcome.
- It can change: the market-value gap depends on share prices and should not be repeated later as though it were a current quote.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

