
Free tools Windows power users keep installed
One-click scans. No signup required.
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
Pakistan is promoting PayPak as a domestic alternative for local card payments, but the often-quoted $250 million annual outflow is an estimate attributed to a senator—not an audited figure showing how much PayPak could save. The policy debate is real; the size of the avoidable savings, the reach of PayPak acceptance and whether any proposed mandate will take effect remain separate questions.
What is PayPak?
PayPak is Pakistan’s domestic payment card scheme, owned and operated by 1LINK and launched under the auspices of the State Bank of Pakistan (SBP). Its stated aims include financial inclusion and digitising payments. PayPak cards are issued through banks; the scheme is not itself a bank account or a card that works everywhere simply because it is domestic.
The official PayPak website displayed 16.8 million cards in force on October 5, 2026. That is a live scheme figure for cards, not a count of active users or a measure of how often those cards are used. (PayPak)
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
What does the $250 million estimate actually say?
Dawn reported on April 27, 2026, that Senator Salim Mandviwalla cited roughly $250 million in annual payments to Visa and Mastercard at a Senate Standing Committee on Finance meeting. He argued that the payments involve dollar settlements even when the underlying domestic transactions are made in Pakistani rupees. The estimate is attributable to Mandviwalla; the report does not establish it as an independently verified or audited outflow. (Dawn’s report)
#1 Best Overall

- With Square Terminal, you can ring up sales, accept payments, and print receipts, all with one device. Use it at the counter or ring up customers anywhere in your store.
- Accept all major credit and debit cards and pay one low rate with no hidden fees and no long-term contracts.
- Process chip cards in just two seconds.
- Get your money as soon as the next business day.
- Use it cordlessly with the built-in battery, designed to last all day.
The figure should not be read as a proven annual saving available simply by switching cards to PayPak. The available accounts do not provide the estimate’s methodology or establish what portion could be avoided through PayPak. A separate 2026 figure from the Islamabad Policy Research Institute (IPRI) puts annual foreign-exchange losses at USD 250–350 million; IPRI also gives estimates of 11 million PayPak users and about 90 million Visa/Mastercard card users. These are IPRI’s figures and have not been reconciled with Mandviwalla’s estimate. (IPRI)
Why is Pakistan promoting PayPak?
The policy case is that domestic transactions on a domestic scheme can be processed and settled within Pakistan, reducing reliance on external payment networks for local spending. In December 2025, SBP described a Faysal Bank/Mastercard/PayPak co-badged card: domestic transactions would settle inside Pakistan, while the Mastercard capability would support international and e-commerce payments. (SBP statement, December 2, 2025)
Rank #2

- Use the, easy-to-use, and customizable POS to get started.
- Accept contactless payments, chip cards, Apple Pay, and Google Pay from anywhere, with improved connectivity, extended battery life, and enhanced security. Pay one low rate for every tap or dip.
- No long-term commitments or contracts, no monthly fees- and with offline payments, keep taking payments for up to 24 hours.
- Safely and securely accepts payments anywhere. Plus, get data security, 24/7 fraud prevention, and payment-dispute management at no extra cost.
- Use the, easy-to-use, and customizable POS to get started.
That distinction matters. A domestic payment scheme may help keep local processing and settlement domestic, but a card’s usefulness also depends on whether people can pay at the merchants and websites they use, and whether it supports cross-border purchases when needed. Promoting domestic settlement and preserving international functionality are related goals, not identical ones.
Why issuance has not translated into the same level of use
SBP reported in December 2025 that PayPak represented over 25% of Pakistan’s 53 million debit cards in circulation, while its usage share was 6%. These are SBP’s 2025 figures, not current 2026 totals. The gap shows why issuing more cards alone does not demonstrate that customers are using them regularly. (SBP statement, December 2, 2025)
Rank #3

- 【Universal Compatibility】 - The MDB Payment Device to PC Converter is designed to connect a variety of MDB devices such as acceptors, bill receivers, and card readers effortlessly. It offers seamless integration with any vending equipment compliant with MDB specifications, ensuring versatility in your payment solutions.
- 【User-Friendly Interface】 - This USB adapter features a straightforward setup process. Simply connect it to your computer, and the adapter transforms MDB protocols into RS-232 serial protocols. This allows for easy communication between your vending machine and your PC, simplifying operations while providing reliable performance.
- 【Enhanced Control】 - With capabilities to control up to eight MDB-compatible devices simultaneously, this converter enhances your management efficiency. Whether you’re handling dispensers or bill acceptors, experience effective monitoring and command over your vending machine operations like never before.
- 【Robust Functionality】 - The MDB-PC USB converter supports a variety of interfaces, including cash interfaces (10H and 60H) and USD interfaces (40H). This broad support mechanism ensures compatibility across multiple configurations, making it an ideal solution for complex setups.
- 【Comprehensive Package】 - Each converter comes complete with required cables, a user guide, and a user agreement, providing everything you need for successful installation. Designed for easy implementation, enjoy a plug-and-play experience with reliable support for all essential MDB functions.
In that statement, Governor Jameel Ahmad identified limited e-commerce and international acceptance, modest marketing and a perception of PayPak as a low-value card among the obstacles. A card that cannot handle a customer’s expected online or overseas payments may be less convenient even if it works for domestic purchases.
Will PayPak work internationally?
PayPak is a domestic scheme, so international use should not be assumed for every PayPak-only card. The documented approach is co-badging: an eligible card carries PayPak for domestic use alongside an international network capability. SBP’s December 2025 statement described the Faysal Bank/Mastercard/PayPak card as supporting international and e-commerce payments, with domestic transactions settling inside Pakistan. In July 2026, Governor Ahmad likewise described co-badged cards as a way to retain international functionality while making PayPak the preferred domestic debit issuance choice. Availability and functionality depend on the specific card issued by a bank. (SBP, December 2025; Associated Press of Pakistan, July 2026)
Rank #4

- Effortless payments and printing: Accept card payments and print payment receipts on the spot with the built-in 40 mm thermal printer.
- Faster sales processing: Use pre-set menus and catalogs to make transactions faster and smoother for you and your customers.
- Reliable and portable: Featuring a 6.5" HD touchscreen made from Corning Gorilla Glass and a powerful battery that lasts all day.
- Seamless connectivity: Stay connected with free mobile data and WiFi, ensuring uninterrupted transactions.
- Real-time payment tracking: Monitor payments and issue refunds right from your device, so you're always in control.
Is the government making PayPak mandatory?
Available 2026 reporting describes a proposal by 1LINK for mandatory PayPak cards for certain government-linked accounts and payments. It does not establish that the proposal became an enacted government mandate. SBP Governor Ahmad’s July 2026 position was that PayPak should become the preferred domestic debit issuance choice, with co-badged cards available for international needs; that statement is a policy preference, not evidence that every customer must use PayPak. (Associated Press of Pakistan, July 2026; Pakistan Today, August 2026)
Recommended Free Tools
What policymakers and customers should weigh
The choice is not simply domestic versus foreign. A practical assessment needs to account for the settlement benefits of local transactions alongside day-to-day acceptance and user needs.
Best Value
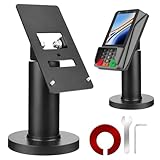
- Compatibility - This POS display stand is compatible for Pax A35, Pax S300. Note: Please carefully confirm the POS machine model before purchasing.
- Easy Installation - Installs quickly using the included type adhesive tape or can be permanently installed to any surface via a drilled hole and bolt mount. And can be removed by heating the area with a hairdryer and using string/thread to detach it if needed.
- Adjustable Card Terminal Mount - The 360-degree swivel allows cashiers to effortlessly turn the device left and right to assist customers without leaving their side, while the 65-degree tilt ensures the terminal is positioned at the optimal angle for various counter heights.
- Commercial Strength - Steel construction gives this universal POS stand durability for use as counter payment terminal in almost any setting.
- Perfect Height - The Pax A35 credit card payment machine stands' ideal height of 4.7" is designed for optimal counter alignment. It provides ample clearance for card insertion and can be adjusted using the tilt feature. Once the perfect tilt angle is set, secure it in place with the included Allen key and wrench to prevent unwanted movement.
- Domestic settlement and foreign exchange: whether a transaction can settle domestically is relevant, but the headline estimate does not quantify the savings PayPak would deliver.
- Merchant and online acceptance: a domestic card has limited value if customers cannot use it at the local merchants or e-commerce sites they rely on.
- International functionality: PayPak-only and co-badged cards are different propositions for customers who need cross-border payments.
- Choice and convenience: a preferred domestic option may preserve customer choice differently from a mandate tied to particular accounts or payments.
- Adoption costs: incentives or compulsory issuance may carry costs; the cited reports do not quantify them.
SBP’s 2025 issuance-versus-usage figures make acceptance and customer utility central to the policy question: a larger share of cards in circulation does not, by itself, show a comparable shift in transactions.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

