
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstalliTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
Marketplace GST TCS is not a substitute for paying the GST you owe on your sales. For qualifying transactions, an e-commerce operator collects tax at source under section 52 and the amount is credited to your electronic cash ledger. You still report your outward supplies and settle your own GST liabilities through the return and payment process. Notified section 9(5) supplies are different: the operator pays tax on those supplies as if it were the supplier.
How marketplace TCS differs from your regular GST payment
Section 52 of the Central Goods and Services Tax Act applies when an e-commerce operator collects consideration for qualifying taxable supplies made through it. The operator collects TCS on the net value of those supplies and reports the collection. The law describes the qualifying base as the “net value of taxable supplies.” Read section 52 of the CGST Act.
Your regular GST payment is the settlement of your own applicable tax liabilities. It is determined through your GST reporting and payment process, not by the marketplace’s TCS deduction. The GST Portal describes paying through a challan and crediting a successful deposit to the Electronic Cash Ledger; the applicable rules govern how liabilities are paid from the ledger. GST Portal payment modes and GST payment rules.
Free tools Windows power users keep installed
One-click scans. No signup required.
| Question | Section 52 TCS | Your regular GST payment |
|---|---|---|
| Who handles the payment? | The e-commerce operator collects TCS on qualifying supplies when it collects the consideration. | You pay your own applicable GST liabilities through the GST Portal payment and ledger process. |
| What does it cover? | A collection tied to the net value of qualifying taxable supplies made through the operator. | Your applicable tax liabilities, as determined by your reporting and circumstances. |
| Where does the money go? | The TCS amount is credited to your Electronic Cash Ledger. | Successful challan deposits are credited to the Electronic Cash Ledger; applicable liabilities are debited under the payment rules. |
| Does it replace your return obligations? | No. TCS collection does not itself report all your outward supplies or settle your tax liabilities. | Payment is one part of your compliance; reporting and payment obligations depend on your circumstances and current rules. |
TCS credit is a cash-ledger credit, not input tax credit in the Electronic Credit Ledger. Keep the two concepts separate when reconciling your GST position.
#1 Best Overall

- LARGE EIGHT-DIGIT DISPLAY – Clear and easy-to-read 8-digit display, perfect for everyday calculations and ensuring accurate results in home or office settings.
- TAX & CURRENCY EXCHANGE FUNCTIONS – Effortlessly handle tax calculations and convert home currency to other currencies for easy financial management.
- GENERAL PURPOSE CALCULATOR – Ideal for a wide range of applications, from basic math to business and personal use, with memory keys for quick storage and recall.
- USER-FRIENDLY KEYBOARD – Easy-to-use layout, featuring square root, percent calculation, and simple functions that make it perfect for everyday tasks.
- COMPACT & PORTABLE DESIGN – Space-saving design that fits easily on any desk or in a briefcase, making it ideal for both home and office use.
What to reconcile before filing
Use three records together: the marketplace settlement statement, your outward-supply figures and filed return, and your GST Portal ledgers. A marketplace payout is not itself a complete record of your GST reporting or final tax payable.
- Match marketplace sales and return adjustments to the supplies you report.
- Check the operator-wise details and corresponding TCS information against your marketplace records.
- Verify that the portal shows the TCS credit in your Electronic Cash Ledger before treating it as available there.
- Reconcile the return and ledger before calculating what remains payable.
Where marketplace supplies appear in GSTR-1
The GST Portal’s GSTR-1 guidance includes Table 14 for supplies through e-commerce operators (ECOs). Table 14 distinguishes section 52 supplies from supplies covered by section 9(5). See the GSTR-1 guide and GSTR-1 creation tutorial.
Rank #2

- Profit margin calculation
- Quick and easy tax calculation
- Square root, sign change, and memory keys
- Attractive metallic design
- 12 digits
Table 14(a): section 52 supplies
Table 14(a) records operator-wise details for section 52 supplies whose taxable value and tax liability have already been reported in other GSTR-1 tables. The GST Portal advisory says Table 14(a) does not itself auto-populate taxable value or tax liability into GSTR-3B. Reporting the operator details there is not, by itself, a payment or a substitute for reporting the underlying supplies. GST Portal advisory dated January 10, 2024.
Table 14(b): section 9(5) supplies
Table 14(b) is for supplies covered by section 9(5), where the e-commerce operator pays the tax as if it were the supplier. The same advisory says values from this table populate the relevant GSTR-3B field. This is a different tax treatment from section 52 TCS, even though both involve marketplace transactions.
Rank #3

- EXTRA-LARGE 12-DIGIT DISPLAY – Clear, easy-to-read screen enhances visibility for fast, accurate data entry—ideal for finance, accounting, and office use.
- COST/SELL/MARGIN KEYS – Quickly calculate profit margins with dedicated keys designed to streamline business and retail calculations.
- TAX CALCULATION FUNCTIONS – Easily add or subtract tax values with built-in tax keys, simplifying invoice and pricing work.
- KICKSTAND DESIGN – Built-in angled display stand offers optimal viewing and reduces neck strain during long sessions.
- SOLAR + BATTERY POWER – Dual power source with solar panel and battery backup ensures reliable performance in any lighting condition.
Why section 9(5) is not marketplace TCS
For supplies notified under section 9(5), the operator—not the underlying supplier—pays the tax as if it were the supplier. Section 52 TCS, by contrast, is an operator’s collection credited to the supplier’s cash ledger; the supplier retains separate reporting and payment responsibilities. The CBIC’s e-commerce and TCS FAQs discuss the operator’s role, while the GST Portal advisory explains the separate GSTR-1 and GSTR-3B treatment.
Depositing money to pay GST
- On the GST Portal, start a payment by creating a challan using the currently available payment options shown on the live portal.
- Complete the payment through the selected mode and confirm that it succeeded.
- Check your Electronic Cash Ledger for the deposit, then apply the ledger balance to the applicable liabilities as provided by the payment rules.
- Reconcile the payment and ledger entries with your return and accounting records.
The GST Portal’s payment options can change, so use the live screen rather than relying on a fixed list of banks or channels. The payment rules identify PMT-06 as the challan for specified payments and set out the cash-ledger process. Portal payment instructions · GST payment rules.
Rank #4

- COMPACT & PORTABLE- Mini desktop size with rubberized keys for fast, comfortable input in office or on-the-go environments.
- BIG DISPLAY & EASY INPUT – 12-Digit LCD Display, large, easy-to-read screen ideal for quick and accurate business or personal calculations.
- ONE-COLOR PRINTING WITH DATE & TIME-Prints in crisp black and automatically includes the date and time—ideal for accurate recordkeeping, receipts, budgets, and accounting tasks.
- TAX & BUSINESS FUNCTIONS- Includes cost/sell/margin, tax calculation, and currency exchange functions for efficient financial decision-making.
- CHECK, CORRECT & RE-PRINT – Review and correct up to 150 steps before printing; use re-print and after-print functions for efficient documentation.
Do not assume a TCS rate from an old reference
Section 52 sets an upper boundary and authorizes the government to notify the applicable TCS rate. CBIC’s sectoral FAQ contains a one-percent formulation for certain intra-state supplies, but that older FAQ does not establish the rate currently notified for a particular tax period. Check the current notification and GST Portal position for the period and transaction before relying on a rate; do not assume every marketplace transaction attracts TCS.
Whether TCS applies, and your final GST balance, depend on the transaction and seller circumstances. This comparison does not determine your registration status, output tax rate, exemption eligibility, return frequency or due date, input tax credit position, or net amount payable.
Quick Recap
Best Value
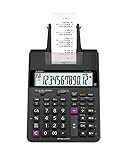
- FAST TWO-COLOR PRINTING – Prints at 2.0 lines per second with dual-color output (black/red) for easy distinction between positive and negative values.
- CHECK, CORRECT & RE-PRINT – Review and correct up to 150 steps before printing; use re-print and after-print functions for efficient documentation.
- TAX & BUSINESS FUNCTIONS – Includes cost/sell/margin, mark-up/mark-down, tax calculation keys, and currency exchange for quick financial operations.
- BIG DISPLAY & EASY INPUT – Features a 12-digit LCD and large, clearly spaced plastic keys for comfortable, accurate data entry.
- UPGRADED DESIGN – New version of the HR-100TM, ideal for taxes, bookkeeping, and accounting with clock/calendar printouts, subtotal & grand total, and percent functions.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

