
Free tools Windows power users keep installed
One-click scans. No signup required.
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
A 0% APR purchase offer lets you spread the cost of a large purchase over several months without interest, but only while you meet the card’s conditions. The safe way to use one is to treat the promotional balance as a loan with a hard deadline: confirm whether the offer is true 0% APR or deferred interest, work out the exact monthly amount that clears the balance before the promotion ends, pay at least the minimum on time every month, and keep other spending off the card until the promotional balance is gone.
Start by checking which kind of 0% offer you have
Many card offers that look identical in an advertisement work very differently once a balance is carried. The Consumer Financial Protection Bureau (CFPB) draws the key line between a true zero-interest promotion and a deferred-interest plan, and your first task is to find out which one you were offered. The wording in the card agreement and the purchase confirmation matters more than the headline.
| Feature | True 0% APR promotion | Deferred-interest plan |
|---|---|---|
| Interest during the promotion | No interest accrues on the promotional purchase during the stated period. | Interest accrues in the background and is waived only if the full promotional balance is paid by the deadline. |
| Balance left at expiration | Interest generally starts on the remaining balance from that point, under CFPB guidance. | Interest can be charged retroactively to the original purchase date on the whole amount, per the CFPB’s description of deferred interest. |
| Typical wording | “0% APR for 12 months” or similar | “No interest if paid in full within 12 months” or similar |
The CFPB’s Regulation Z commentary also sets a limit on how these plans may be advertised. An issuer offering a deferred-interest plan may not disclose a 0% rate as the rate applicable to those transactions if there are any circumstances under which the consumer would owe interest on them during the deferred-interest period. In practice, that means the phrase “no interest if paid in full” is the signal to read the terms closely, not a reassurance.
Recommended Free Tools
Work out the three numbers that control the outcome
Before you buy, write down three things from the card’s disclosures or your statement. Each one changes your plan.
#1 Best Overall
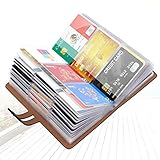
- 【Durable Materials】: Our credit card organizer is made of water-resistant and wear-resistant PU, reinforced with sealed edges and durable PVC credit card sleeves. It is scratch-resistant and water-repellent, resistant to dust and sweat, and easy to clean. The edges of the credit card holder are reinforced to provide the advantages of wrinkle resistance and crack resistance.
- 【RFID Blocking】The credit card holder has an anti-shield lining, which can effectively block the electronic scanning instrument from illegally scanning the credit card in the card holder to protect the security of your RFID chip card.
- 【Easy to Find & Read】The internal translucent anti-magnetic PVC card page makes it easy for you to find and read card information and quickly find the card you need.
- 【Large capacity / Multipurpose】A total of 32 card slots, each card can hold 3 cards. A total of 96 card slots, fully meet your needs for card storage. You can hold your important customer business cards, credit cards, debit cards, ID cards, membership cards, VIP cards, invoices, receipts, etc. to prevent loss and damage.
- This is the best choice to keep your credit card and business card organized and easy to manage. Can be used to store credit cards or business cards that are important but not commonly used.
- The exact promotional expiration date. Use the date printed in the terms, not a rounded “about one year.” Note whether the offer ends on a statement closing date or a calendar date.
- The post-promotion purchase APR. This is the rate that applies to any amount still owed after the promotion ends, or the rate that interest would be measured against if a deferred-interest balance is not cleared.
- The minimum payment method. Check how the minimum is calculated and whether it is enough to finish the promotion. The CFPB warns that a minimum payment is usually not enough to clear a promotional balance before it expires.
Calculate a monthly payment that clears the balance in time
The simplest target is to divide the promotional purchase amount by the number of payments you will actually make before the promotion ends. Because the first statement often closes some weeks after the purchase, you may get one fewer payment than the month count suggests, so count the statements that fall before the deadline.
- Confirm the promotional purchase amount on the statement that posted the transaction. Exclude unrelated charges.
- Count the statement due dates that fall on or before the promotion’s expiration date.
- Divide the promotional balance by that count. For example, a $1,200 purchase with 12 statement payments before the deadline needs $100 per month.
- Set up an automatic payment for that amount or more, and keep the card’s minimum payment as the floor, not the target.
- Recalculate after each statement. If you missed a month or a payment was late, divide the remaining balance by the remaining payments.
Understand the CFPB’s worked examples
The CFPB has published illustrations that show how small remaining balances turn into large costs under deferred interest. They are examples, not predictions about any particular card.
Rank #2

- 【96 Card Pokets】: Our leather credit card holder is a good way to store your pocket-money, bank card, VIP card, name card, train ticket and more. It's the best choice to keep the cards neat and prevent loss.
- 【Blocking Design】: The business card book has a blocking designed lining, can block thieves through scanning technology to steal your identity card information, credit card, bank card and other information, this keeps your vital information in driver license, debit cards and credit cards from being stolen.
- 【Portable and Convenient】: The dimensions of the business id card case: 7.5" x 4.3" x 0.8". The slim profile and light-weighted design make this business card holder easy to carry. Keep your business cards nice, neat and at hand all the time.
- 【Durable Material】: Our credit card organizer is made of water-resistant and wear-resistant PU, reinforced with sealed edges and durable PVC credit card sleeves. It is scratch-resistant and water-repellent, resistant to dust and sweat, and easy to clean. The edges of the credit card holder are reinforced to provide the advantages of wrinkle resistance and crack resistance.
- 【Unique Appearance】: With the elegant and sleek look, book-style card holder can get you more admire and opportunity. It's an ideal gift for your family, friends, clients, associates, or as a company souvenir.
| Example | Purchase and payment assumptions | Outcome shown | Source and date |
|---|---|---|---|
| Small deferred-interest plan | $400 purchase; $25 paid per month for 12 months; 25% rate assumed | $100 unpaid at the end, with $65 of accrued interest added, for $165 owed | CFPB guidance, 2017 |
| Furniture case | $4,500 purchase; $180 unpaid at the end of a two-year term; 31.99% APR assumed | $1,439.55 in deferred interest | CFPB retail-card spotlight, 2024 |
The CFPB’s 2024 spotlight on retail cards also reports that about one fifth of deferred-interest promotional balances had interest retroactively imposed, citing an earlier CFPB report. The spotlight does not give the year of that earlier report, so treat the one-fifth figure as the CFPB’s reported share rather than a current rate. The same spotlight reports an average promotional purchase amount of $637.
Keep the promotional balance separate from new spending
Using the card for everyday purchases while you carry a promotional balance creates two problems. First, on many cards, purchases can accrue interest from the transaction date once you carry a balance, which means the grace period you rely on for normal spending can disappear. Second, a grace period may require you to pay the entire balance, including the promotional balance, by the due date to avoid interest on new purchases. The CFPB’s practical advice is to put new spending on another card or account until the promotional balance is cleared.
Rank #3
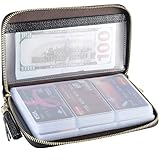
- Material: Genuine Cowhide Leather and PVC card slots.
- Size: 7.48"*3.54"*0.98" (19*9*2.5 CM)
- Large Capacity: The card holder has 60 cards slots and 2 ID Windows. It is enough room for your ID card, credit cards, gift cards and dicounted cards. Small size is perfect to fit in your pockets or handbags.
- RFID Blocking Design: RFID Blocking designed lining keeps your vital information Secure. Be safe and protected from Electronic Pick pocketing.
- Great Gift: Great gift for mother, daughter, grandmother and so on.
If you have more than one balance on the card
When a card carries several balances at different rates, payments above the minimum may be applied to a higher-APR balance first, depending on the allocation rules that apply to your card. That can leave the promotional balance shrinking more slowly than you planned. Check your statement to see how payments were applied, and ask your issuer whether extra payments can be directed to the promotional balance. Even if the issuer agrees, a missed minimum payment still matters, so keep the minimums current.
Compare the full offer, not only the advertised 0%
When you compare cards, the advertised 0% figure is only one line. Look at the qualifying purchase rules, the length of the promotion, the minimum purchase requirement if any, the post-promotion APR, fees, and the payment allocation terms. A longer promotion with a high post-promotion rate can cost more than a shorter one if you do not clear the balance. APR is useful for comparing ongoing borrowing costs, but for a time-limited promotion, the length of the offer and the fees matter as much.
Rank #4

- Material: Genuine leather and PVC card slots.
- Size: 4.72"*3.15"*0.7" (12*8*1.8 CM)
- Large Capacity: The card holder has 26 cards slots. It is enough room for your ID card, credit cards, gift cards and dicounted cards. Small size is perfect to fit in your pockets or handbags.
- RFID Blocking: RFID Blocking designed lining keeps your vital information Secure. Be safe and protected from Electronic Pick pocketing.
- Great Gift Idea: Great gift for mother, daughter, grandmother and so on.
Balance-transfer offers are a separate case. A balance transfer can carry a fee even when the promotional rate is 0%. That fee applies to the transferred balance, not to a purchase, so do not treat it as a purchase cost when you compare options.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Before you buy: a short checklist
- The offer is labeled as true 0% APR, or you have read the deferred-interest wording and know the deadline.
- You have the exact expiration date and post-promotion purchase APR in writing.
- You have calculated a monthly payment that clears the balance before the deadline, and it is set up as an automatic payment.
- You will not put unrelated spending on the card until the promotional balance is cleared.
- You know how your issuer applies payments above the minimum.
What this guidance does and does not cover
The CFPB guidance and Regulation Z commentary cited here describe U.S. credit-card practices. The CFPB guidance on the mechanics is from June 8, 2017, and the retail-card figures are from the 2024 spotlight, so check your own agreement for current terms. Promotional offers, rates, and issuer rules change. The numbers above are illustrations, not guarantees for your card. This article does not give individual financial advice, and it does not compare specific current card offers.
Best Value

- QUICK ACCESS: Unlike traditional leather wallet, this mens slim wallet is equipped with the ejection mechanism. Simply press the side button on the card holder, all cards pop up at a step pattern that makes them very easy & convenient to take out.
- SLIM BODY, LARGE CAPACITY: This mens minimalist wallet holds up to 12+ cards. The aluminium chamber holds 6-8 and the leather flap holds 4-6 (1 ID window included). There are also removable money clips on the back capable of holding 15+ cash.
- CLEAR ID WINDOW: On the inside of the carbon fiber wallet, which has an ID card holder slot, which allows you to swipe the card without removing the card. It can be used to store ID card, work card, driver license, access card, traffic card, etc.
- RFID BLOCKING: This rfid wallet for men embeds a chip in the aluminum card case to block unknown scanning devices from scanning your credit cards, debit cards, and driver's licenses, maximizing the protection of your personal property.
- PERFECT PRESENT IDEA: This leather wallet is packaged in a beautiful premium box and it is great choice for men. It is a perfect credit card wallet for your friend, lover, parent or yourself on special Days.
For the wording the CFPB uses to explain the basic risk, Gail Hillebrand, writing for the CFPB on June 8, 2017, put it this way: “You are still borrowing money: Remember, even if the interest rate is zero or deferred and you get the deferral, you are still borrowing money that you have to repay.”
Quick Recap
The Bottom Line
“”
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

