
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
If interest rates remain elevated, review how much interest-rate, credit, inflation, and liquidity risk your portfolio carries—but do not change your allocation simply because of a rate headline. “Higher for longer” is a scenario, not a certainty. The right mix of stocks, bonds, and cash depends on your time horizon, need for liquidity, and tolerance for losses.
What higher rates can mean for your portfolio
Fixed-rate bonds can lose market value when yields rise
The SEC Office of Investor Education and Advocacy states: “A fundamental principle of bond investing is that market interest rates and bond prices generally move in opposite directions.” When newly issued bonds offer higher yields, existing fixed-rate bonds may become less attractive unless their market prices fall. Longer-maturity bonds and bonds with lower coupon rates generally have greater price sensitivity to yield changes, all else equal.




A bond’s market-price movement before maturity is different from its scheduled interest payments and principal repayment at maturity. An individual bond held to maturity may repay principal as scheduled if its issuer meets its obligations; that does not prevent its market value from fluctuating in the meantime. Bond funds and ETFs do not give an investor the same single-bond maturity repayment: fund shares can fluctuate in value, and the fund’s holdings change over time.
Stocks and cash have different risks
Do not assume that stocks always fall when rates rise. Equity prices can respond to many factors, and the general investor education material cited here does not establish a predictable stock-market direction for a given rate move. Cash equivalents generally have low investment-loss risk, but inflation can erode what their balances can buy. A cash yield available today is not guaranteed to persist.
#1 Best Overall
Use dated rate data as context, not a forecast
The Board of Governors of the Federal Reserve System’s July 2026 Monetary Policy Report said the U.S. federal funds target range had been 3.5%–3.75% since the beginning of 2026, while inflation remained elevated relative to the Federal Open Market Committee’s 2% longer-run objective. The report also described approximate year-to-date increases of 60 basis points in 2-year nominal Treasury yields and 35 basis points in 10-year nominal Treasury yields.
Those are observations reported in July 2026, not October 7, 2026 market quotes or a forecast of the next policy decision. They help explain why investors may review rate exposure, but they do not show that rates will remain high or establish what any individual portfolio should hold.
Rank #2
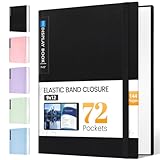
- 72-Pocket Large Capacity Portfolio: The art binder includes 72 bound (non-refillable) top-loading clear sheet protectors, displaying up to144 pages. Fits 9”x12" letter size or smaller. Measures 12 7/8" (L) x 9 11/16" (W) x 1 1/2" (G).
- Elastic Band for Secure Protection:For total peace of mind, a sturdy elastic band keeps your portfolio securely fastened. Your important papers stay put, organized, and protected from damage.
- High Transparency & Tailor-Made Spine Title: Our presentation book with crystal clear PP sheet protectors offers complete transparency for checking through and organizing. You can label and identify your watercolors, sketches, scrapbook, art pieces, sheet music, certificates, and other projects by customizing the reversible spine insert.
- Archival Grade & Heavy Duty Cover: Made from robust yet light weight, polypropylene which is archival quality, acid-free and non-glare, and water-proof. Thickened and sturdy cover won’t easy to crack and keeps your clear sleeves from being damaged.
- Multi-Function: Not only suitable for long-term storage but also for displaying your paintings, photos, artwork, drawing, stencils. Great gift for students, teachers, office workers, secretaries, musicians, painters, etc.
Review your portfolio before changing it
- Write down your target allocation. Identify the intended portions of your portfolio in stocks, bonds, and cash, and compare current holdings with that plan. Allocation is personal; the SEC says it depends on factors such as time horizon and risk tolerance.
- Check liquidity and timing. Note when you may need to spend the money. Funds needed soon may require different liquidity and loss-risk considerations from investments intended for a distant goal.
- Inspect bond exposure. For each bond holding or fund, review maturity or duration, coupon characteristics where relevant, credit quality, and issuer type. Longer-maturity fixed-rate exposure generally has more sensitivity to yield changes, but individual bonds and funds do not all behave alike.
- Check diversification. Look across asset classes, bond maturities, and issuer types. A narrowly focused fund is not necessarily broadly diversified just because it is a mutual fund or ETF.
- Consider inflation and cash needs. Keep liquidity needs in view while recognizing that inflation can reduce cash purchasing power and that current cash returns may change.
- Rebalance only against your plan. If your holdings have drifted from your intended allocation, consider whether bringing them back in line fits your goals, timeframe, and risk tolerance. A rate headline alone is not a rebalancing rule.
Compare choices by the risks that matter to you
No single portfolio choice follows from the possibility of higher rates. When evaluating whether to maintain or adjust an exposure, compare the relevant trade-offs rather than looking for a universal winner.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
| What to compare | Questions to ask |
|---|---|
| Interest-rate sensitivity | How much could the holding’s market value respond to a change in yields? How do maturity and duration affect that sensitivity? |
| Time horizon and liquidity | When might you need the money, and could you tolerate a market-value decline before then? |
| Credit risk and issuer type | Who owes the payments, and how does the issuer’s credit quality affect the risk? |
| Inflation exposure | Could inflation reduce the purchasing power of the income or cash balance? |
| Diversification | Are exposures spread across asset classes, maturities, and issuer types, or concentrated in a narrow area? |
| Risk tolerance | Could you stay with the plan through fluctuations without taking more risk than you can accept? |
When an individual bond and a bond fund differ
An individual bond has stated payment terms and a maturity date; if the issuer meets its obligations and the investor holds it to maturity, principal repayment is scheduled for that date. Selling earlier can produce a gain or loss because the market price may have changed. A bond fund holds a portfolio of bonds and its share price can fluctuate; it does not promise to return an investor’s original purchase price on a single maturity date in the way an individual bond may.
That distinction does not make one format universally better. Consider how you need to access the money, the portfolio’s interest-rate and credit exposure, diversification, and your tolerance for price changes. Product-specific details should be checked in the fund documents or bond terms.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Sources and scope
The SEC’s investor education materials explain general bond-price, allocation, and diversification concepts; they do not prescribe a portfolio for a particular investor. The Federal Reserve figures above come from its July 2026 report and are dated context rather than a live market update. This article is general information, not individualized investment advice.
Quick Recap
Best Value
Rank #4
- SEC: When Interest Rates Go Up, Prices of Fixed-Rate Bonds Fall
- SEC: Beginners’ Guide to Asset Allocation, Diversification, and Rebalancing
- SEC: Investor Bulletin: High-Yield Corporate Bonds
- Federal Reserve: July 2026 Monetary Policy Report
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problems
