
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
Zelle moves money between eligible U.S. bank or credit union accounts using an enrolled email address or U.S. mobile number. You send through a participating institution’s app or online banking, choose the recipient, enter the amount, and confirm. If the recipient is already enrolled, the money typically arrives within minutes; because completed payments generally cannot be reversed, check the recipient and amount before sending.
How a Zelle transfer works
- Open your bank or credit union’s channel. Find Zelle in the participating institution’s mobile app or online banking and follow its enrollment steps. Zelle’s getting-started guidance explains the service’s bank-linked setup.
- Enroll an email address or U.S. mobile number. Link that contact detail to an eligible U.S. checking or savings account. It identifies your Zelle profile; the person sending you money does not need your account number. Both parties need eligible accounts under Zelle’s guidance.
- Select the recipient and enter the amount. Use the email address or U.S. mobile number enrolled by the recipient. Check the contact detail and displayed identity, where available, before proceeding.
- Review and confirm. Verify the recipient and amount in your bank’s transfer screen, then submit. Zelle recommends sending only to people you know and trust.
- The recipient’s linked account receives the money. For someone already enrolled, the transfer typically becomes available within minutes. Your bank or credit union determines actual availability.
Because enrollment is tied to a contact detail, make sure you use the address or number the recipient registered. A mistyped or outdated contact can send money to the wrong profile.
How long Zelle takes—and what happens if the recipient is not enrolled
Recipient already enrolled
Transfers between enrolled consumers typically arrive within minutes. That is not a guarantee for every bank or transaction; check the payment status and your institution’s information if a transfer does not appear as expected.
Recipient not enrolled
Zelle notifies the recipient and prompts them to enroll using the email address or U.S. mobile number you used. The payment remains pending until they do. If they do not enroll within 14 days, Zelle says the payment expires and the funds return to the sender. See Zelle’s guidance for payments to an unenrolled recipient.
#1 Best Overall

- All-in-One NFC & QR Code Multi-Payment Stand: Enable your customers to pay instantly with a simple tap or QR scan. This versatile stand supports Venmo, PayPal, Cash, Zelle, Cash App, and more, providing a professional contactless payment solution for counters, cafés, restaurants, retail stores, and pop-up shops
- No App or Fees – Easy Contactless Payments: Customers can complete payments directly via NFC or QR code without downloading apps, creating accounts, or paying subscription fees. This Scan to Pay sign ensures fast, seamless, and secure transactions, enhancing convenience and customer satisfaction
- No App or Fees – Easy Contactless Payments: Customers can complete payments directly via NFC or QR code without downloading apps, creating accounts, or paying subscription fees. This Scan to Pay sign ensures fast, seamless, and secure transactions, enhancing convenience and customer satisfaction
- Acrylic Desktop Stand: Crafted from high-quality acrylic, this NFC QR code payment stand is compact, self-standing, and perfect for counters, desks, or reception areas. Its sturdy tabletop design ensures visibility and professional presentation while customers tap or scan to pay effortlessly
- Acrylic Desktop Stand: Crafted from high-quality acrylic, this NFC QR code payment stand is compact, self-standing, and perfect for counters, desks, or reception areas. Its sturdy tabletop design ensures visibility and professional presentation while customers tap or scan to pay effortlessly
Can you cancel a Zelle payment?
A payment to an enrolled recipient generally cannot be reversed once completed. You can cancel only while the recipient has not enrolled. Check the payment’s status in your bank’s app or online banking to see whether cancellation is available; if it is not, contact your financial institution for guidance.
If money is missing or you suspect a transfer was unauthorized, contact your bank or credit union promptly. Zelle says qualifying imposter scams may be eligible for reimbursement, but not every scam loss qualifies. Zelle’s cancellation guidance explains the limits.
Rank #2

- ALL-IN-ONE DESIGN: Single high-visibility QR code accepts Venmo, Cash App, PayPal, and Zelle on a branded customer page
- PREMIUM CONSTRUCTION: Made from 3/8-inch thick high-impact plastic with precision-embossed text and logos, measuring 7.5" × 4" × 4"
- SMART FEATURES: Built-in business card dispenser, Venmo Code Assist for first-time payers, a secure dashboard for scan and payment tracking
- QUICK SETUP: One-minute activation process - simply scan QR code, add payment methods, business information, and customize settings
- CUSTOMIZED & HANDCRAFTED: Personalize your sign with your business name on top and custom text on the bottom — each piece is handcrafted for a professional, branded look
Is Zelle safe for purchases?
Zelle does not offer purchase protection if an item bought with the service never arrives or is not as described. That makes it a poor fit for paying an unknown seller when you need protection if delivery or condition becomes disputed. Use it for people you know and trust, not as a substitute for a marketplace payment method with purchase protection. Zelle describes this limitation in its FAQ about unenrolled recipients.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Fees, transfer limits, and account eligibility
Fees
Fees depend on your financial institution, so check its terms rather than assuming a transfer is free. In a Q1 2026 survey of financial institutions offering Zelle, Zelle reported that 99.40% of consumer checking and savings accounts linked to Zelle did not charge a fee to send, receive, or request money. That network survey figure does not establish the fee for your own account. Zelle’s fee FAQ provides its fee guidance.
Rank #3

- ONE TAP, MULTIPLE WAYS TO GET PAID – Give customers one simple place to access your payment options. Add Cash App, Venmo, PayPal, Zelle, card checkout links, ACH, wire transfer, Bitcoin, cryptocurrencies and custom payment methods.
- NFC TAP + QR CODE – Customers can tap the sticker with a compatible NFC smartphone or scan the QR code to open your KeeperTag Pay page. No KeeperTag app is required for the person paying.
- UPDATE ANYTIME — NO NEW STICKER NEEDED – Change usernames, payment links, banking instructions or crypto wallet addresses from your KeeperTag account while keeping the same physical NFC & QR sticker.
- BUILT FOR SMALL BUSINESS & EVERYDAY PAYMENTS – Ideal for counters, salons, food trucks, pop-up shops, markets, service professionals, creators, drivers, events, tips and other places where customers need an easy way to access payment information.
- NO BATTERY & EASY TO ACTIVATE – Passive NFC technology requires no charging or batteries. Activate your KeeperTag, add your preferred payment methods and place the 4 x 4 inch sticker where customers can easily tap or scan. KeeperTag provides payment links and information; payments are completed through the selected third-party service.
Limits
There is no universal transfer limit in Zelle’s consumer guidance. Your bank or credit union sets the limits that apply to your account; ask the institution for your daily or other applicable limits. See Zelle’s transfer-limit FAQ.
Eligibility
Consumers access Zelle through participating U.S. banks and credit unions and need an eligible checking or savings account. Participating institutions set their own account rules and enrollment details, so verify availability and eligibility with yours. Zelle’s getting-started page covers access through financial institutions.
Quick Recap
Rank #4
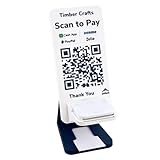
- ALL-IN-ONE DESIGN: Combines a Square card reader holder and a single QR code for Venmo, Cash App, PayPal, and Zelle in one professional point-of-sale display
- PREMIUM CONSTRUCTION: Made from 3/8-inch thick high-impact plastic with precision-embossed text and logos, measuring 10" × 6" × 4"
- SMART FEATURES: Built-in business card dispenser and USB cord pathway for reader power, plus secure dashboard for payment tracking
- QUICK SETUP: One-minute activation process - simply scan QR code, add payment methods, business information, and customize settings
- CUSTOMIZED & HANDCRAFTED: Personalize your sign with your business name on top and custom text on the bottom — each piece is handcrafted for a professional, branded look
Before you send
- Confirm the recipient’s enrolled email address or U.S. mobile number with them.
- Review the displayed recipient identity, if shown, and verify the amount before confirming.
- Use Zelle for people you know and trust; it does not provide purchase protection for a transaction that goes wrong.
- Check your bank or credit union’s fee, account eligibility, transfer limits, and payment status.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

