
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
Neither a gold loan nor a personal loan is automatically cheaper or safer. In India, a gold loan is secured by eligible gold you pledge; a personal loan is unsecured and depends on the lender’s assessment of your creditworthiness and repayment capacity. Compare written offers for the same amount and repayment period, including every mandatory charge and each payment due. A lower quoted rate alone does not settle the choice: with a gold loan, missed repayment can put your jewellery at risk.
Which is cheaper, a gold loan or a personal loan?
The cheaper option is the one with the lower total rupee cost for your specific amount, term, eligibility and repayment schedule. There is no defensible universal winner: lender pricing and fees vary, and current matched offers for the same borrower and loan terms are not established here.
Ask each lender for a written offer showing the annualized interest rate, every mandatory charge, the net amount disbursed, the amount and date of each payment, and the total amount payable. Compare the same principal and repayment date. For a gold loan, include appraisal and processing charges, as well as any applicable safekeeping charge. Central Bank of India’s Cent Gold Loan Scheme, for example, lists appraisal fees separately from processing charges; it is one lender’s scheme, not a market average.
Free tools Windows power users keep installed
One-click scans. No signup required.
Compare the complete offer, not the headline rate
| What to compare | Gold loan | Personal loan |
|---|---|---|
| Collateral | Eligible gold jewellery, ornaments or coins are pledged. | No collateral is pledged; approval depends on the lender’s assessment of creditworthiness and repayment capacity. |
| Price | Lender-specific interest and charges; valuation and loan-to-value terms affect how much you can borrow. | Lender- and borrower-specific pricing. |
| Repayment | Can be a lump sum at maturity or another lender-specific schedule. Confirm the written offer. | Confirm the actual installment schedule and any prepayment terms in the offer. |
| Amount available | Depends on acceptable gold, purity, net weight, valuation, loan-to-value terms and lender policy. | Depends on the lender’s underwriting and your assessed repayment capacity. |
| If you do not pay | The lender may auction pledged gold under the agreement and applicable rules; a shortfall may still be recoverable under the agreement. | The debt remains due and may lead to collection and credit consequences under the agreement and applicable law. |
Do not compare a maximum advertised loan amount with the amount you will actually receive. For a gold loan, ask how the lender determined the gold’s net weight, purity and value, and what amount it will disburse after applying its terms. For either loan, ask for the total rupees payable and all conditions that could change it.
#1 Best Overall
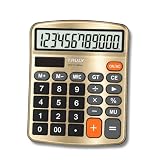
- 「Large 12-Digit Anti-Glare Display」Easy-to-read numbers with a wide viewing angle for clear visibility under office lighting or sunlight, helping reduce eye strain during everyday calculations.
- 「Big, Responsive Buttons」Well-spaced keys provide a comfortable, responsive feel for fast and accurate input—ideal for everyday desk, office, home, and school use.
- 「Premium Brushed Metal Face」Brushed anodized aluminum metal face gives this desk calculator a solid, professional feel and a refined metallic finish designed for everyday use.
- 「Dual Solar & Battery Power」Solar power with pre-installed battery backup keeps the calculator ready across different lighting conditions, with automatic power-off to help conserve energy.
- 「Essential Business Functions」ncludes GT, MU, double-zero (00), backspace, memory, percentage, and standard 4-function calculations for office work, accounting, retail, home, and everyday tasks.
Is a gold loan safer than a personal loan?
It depends on what risk you mean. A gold loan puts pledged jewellery at risk if you fail to repay as agreed. A personal loan avoids that collateral risk, but it does not erase the debt: missed payments can still have collection and credit consequences under the contract and applicable law.
If the jewellery is irreplaceable, has family significance, or you are unsure you can meet the repayment schedule, a lower rate is not by itself a good reason to pledge it. Read the default, notice and recovery terms before signing either agreement.
Rank #2
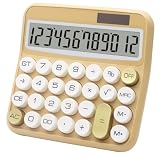
- Large LCD Display Screen: Our white gold calculator is equipped with a large LCD display screen and a 12 digit display screen, which allows clear viewing of calculations and readings from any angle, making it very convenient and comfortable. The calculator display is also designed with a 15 ° tilt to achieve optimal visibility and stability, effectively reducing reading fatigue.
- Computer Keyboard Design: This desk calculator is made of ABS high strength engineering plastics, light weight but durable. It can withstand the impact of falling on the height of the desktop for several times.Imitating the design of a computer keyboard, the big button calculator large keys are easy to press with fingers.
- Bottom Anti Slip: The cute calculator comes with 4 anti slip pad edges, providing additional friction and stability on various surfaces, keeping the office calculator stable on any surface, ensuring that you won't slip while using this office accessory for quick calculations.
- Dual Power Calculator: Electric digital white gold calculator has dual electric drive, light energy and 1 * AAA battery (not included). This desktop calculator can switch power modes according to the environment, making it more durable and convenient. As long as you use solar panels in a well lit environment, they will completely power the calculator.
- Widely Applicable: This basic calculator is suitable for schools, homes, offices, shops, etc. It is the perfect tool to quickly meet your daily computing needs in various environments. This white gold office supplies is also an ideal choice for students, teachers, colleagues, and anyone who needs a reliable calculator.
What happens to your gold if you cannot repay?
Under the loan agreement and applicable rules, the lender may auction pledged gold after default. The Reserve Bank of India’s Lending Against Gold and Silver Collateral Directions, 2025 set requirements concerning valuation, lender policies, custody and auctions. They provide protections, not a guarantee that you will retain your gold after failing to repay.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →The directions require a lender to return any auction surplus within seven working days after it receives the full auction proceeds. A lender may recover a shortfall according to the agreement. The Central Bank of India scheme separately states that it releases collateral within a maximum of seven working days after full repayment or settlement; that is a scheme-specific published term, not a general release deadline for every lender.
Rank #3

- Computer Keys Design:Super comfortable touch feel
- Large LCD Display:12 digits make it more useful for large calculations
- Dual Power: it's powered by one AA battery and solar panel. Kindly note the package contain one AA battery. The solar only can serve as auxiliary power. Highly recommended to put an AA battery for a clearer display.
- Product Size: 7.2 x 6.2 x 1.8 in.
- Exquisite Appearance:Champaign gold color panel and metal overlay, perfect for office daily uses
The RBI’s supervisory circular reported deficiencies at select entities, including valuation without the customer present and lack of transparency during auctions. Those findings do not establish that every lender or transaction has these problems, but they make it sensible to observe the appraisal, keep the valuation and loan documents, and understand the lender’s notice and auction process. The RBI directions say branches should normally lend against pledged collateral only where they have an appropriate secured storage facility.
Can a gold loan’s repayment schedule create a cash-flow problem?
Yes. A bullet loan can require principal and interest together at maturity, so a loan that looks manageable based on its interest cost may still demand a large lump sum on one date. Confirm whether the offer is bullet repayment or installments, the exact due dates, and what happens if you miss a payment.
Rank #4

- Gold Desk Accessories: This calculator is designed for office, business, home, school and many occasions
- Easy to Read: Large 10-digit display, 30° bend body for easy viewing
- Product Size: 7.2 x 6.2 x 1.8 in
- Slim Design, elegant look, portable for office, home
- On and off buttons, profit margin, clear entry, percentage, and auto power-off
For context, Central Bank of India’s Cent Gold Loan Scheme page describes a 12-month demand loan with bullet repayment. That is an example of one lender’s published product, not a description of every gold loan. Its page lists a retail loan-to-value range of 68%–78%; this is scheme-specific, not a universal RBI limit. The page says the applicable interest rate should be checked through its linked rate information, so those terms alone do not establish the scheme’s total cost.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →How is pledged gold valued, and how much can you borrow?
The amount available is not simply the jewellery’s retail or sentimental value. The lender assesses eligible gold, purity and net weight, then applies its valuation method and loan-to-value terms. Ask for the calculation and check that the deductions for stones or other materials are clear.
Best Value

- Extra large 12-digit angled display.
- Loan Wizard.
- Automatic Tax Keys.
- Selectable decimal setting.
- Input any three loan variables to compute the fourth.
Central Bank of India’s scheme page says it calculates net gold weight after deductions for stones and other materials, and describes a valuation based on the lower of a preceding 30-day average reference price or a prior-day closing reference price, subject to the applicable margin and loan-to-value terms. These are that scheme’s published methods; confirm the method and figures applicable to your application.
What RBI rules matter for gold loans in India?
The RBI issued its Lending Against Gold and Silver Collateral Directions, 2025 on June 6, 2025, and updated the document on September 29, 2025. It says regulated entities were to comply no later than April 1, 2026. The directions cover commercial banks, specified cooperative banks and NBFCs, and address loans for consumption or income generation against eligible gold or silver jewellery, ornaments or coins.
The directions require lender credit policies to address matters including borrower and portfolio limits, maximum loan-to-value terms, action if those terms are breached, valuation and purity standards. For bullet loans, the loan-to-value calculation considers the total amount due at maturity. These are requirements for covered lenders; they do not replace the need to read the specific loan agreement or guarantee a particular loan amount.
When should you choose each loan for a short-term need?
A gold loan may fit if
- You have eligible gold and are willing to put it at risk under the agreement.
- The written offer’s total cost is lower for the same borrowing amount and repayment date.
- You can meet the actual schedule, including any lump sum due at maturity.
A personal loan may fit if
- You do not want to pledge jewellery, especially if it is personally important.
- The lender approves an amount and schedule that suit your need and cash flow.
- The total cost is manageable, even if the quoted interest rate is higher than a gold-loan offer.
These are decision criteria, not individualized financial advice. If repayment is uncertain, do not treat either loan as low-risk merely because it can provide short-term cash.
Quick Recap
Questions to ask before signing
- For the same amount and repayment date, what is the total rupee amount I will pay?
- What is the annualized interest rate, and which mandatory fees or charges are additional?
- Is repayment by installments or a lump sum, and what exact amount is due on each date?
- What happens if I miss a due date, and how do notice and recovery work?
- For a gold loan, how were my gold’s purity, net weight and value determined?
- When and how will pledged gold be returned after repayment or settlement?
- How important is it to keep this jewellery in the family?
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

