
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Scan for outdated or missing drivers - takes under a minute3Clear out junk files and repair common Windows errorsiTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
Travel Insurance Direct (TID) advertises its Annual Multi Trip policy for multiple domestic and overseas trips during a 12-month period, with a maximum of 35 days per trip. Its headline benefits include unlimited overseas medical expenses, $2,000 in cancellation costs, $12,000 for luggage and personal effects, $2.5 million in personal liability and $6,000 for rental-vehicle insurance excess. Those are policy limits, not guarantees of claim payment. Whether the cover suits you depends on the terms in the PDS and certificate for your purchase, as well as your itinerary, medical circumstances and selected options.
There is an important date qualification: TID flags a change in policy information for policies purchased on or after 15 September 2026. The applicable updated wording is not established here. Anyone buying on or after that date should read the current PDS and certificate before relying on a benefit or assuming an exclusion does—or does not—apply.


What does Travel Insurance Direct Annual Multi Trip cover?
TID’s product summary presents the following headline benefits. They describe stated limits; the full policy wording determines eligibility, exclusions, sub-limits and how a claim is assessed.
| Benefit | Published headline limit |
|---|---|
| Overseas medical expenses | Unlimited |
| Cancellation costs | $2,000, with an option to increase |
| Personal liability | $2.5 million |
| Luggage and personal effects | $12,000 |
| Rental-vehicle insurance excess | $6,000 |
These figures come from TID’s current product summary, accessed in 2026. They should not be read as the amount payable for every event: conditions, exclusions and item-specific sub-limits can affect the outcome. In particular, a total baggage limit does not establish the amount payable for an individual item. Check the benefits table and full PDS for any sub-limits relevant to what you plan to take.
#1 Best Overall
How long can each trip be?
The specific Annual Multi Trip product page states a maximum of 35 days per trip. That is the relevant published duration for this named plan; do not substitute a duration shown on a general multi-trip page, which describes selectable limits across multi-trip cover more broadly.
TID’s general multi-trip information describes a journey as starting and ending at the traveller’s home in Australia and reaching a destination at least 250 km from home. Because the specific plan’s governing terms are in its applicable PDS, confirm how those journey rules apply to your intended travel and what happens if a trip exceeds the permitted duration.
Is annual multi-trip travel insurance worth it?
It may be worth considering if you expect several trips within one 12-month policy period and each fits the plan’s trip-duration and journey rules. A single annual policy can be a practical alternative to arranging cover separately for each trip, but the headline benefits alone cannot establish that it is better value or suitable for you.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Compare the cover against your actual travel
Get a quote based on your trips and compare it with suitable alternatives using the same criteria:
Rank #3
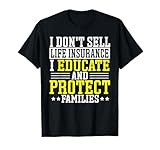
- Life insurance clothes that says: I don't sell life insurance, I educate and protect families.
- Life insurance clothes ideal for any insurance sales agent, medicare broker or salesperson who wants to show off his got life insurance vibe.
- Lightweight, Classic fit, Double-needle sleeve and bottom hem
- Maximum days covered per trip and any home-distance or journey-start rules.
- Overseas medical and evacuation benefits, including relevant conditions and exclusions.
- Cancellation limit and the price and terms for increasing it.
- Total baggage limit and sub-limits for the particular items you will carry.
- Rental-car excess benefit and the circumstances in which it applies.
- How the insurer assesses existing medical conditions, activities and cruises.
- Exclusions that matter to your destinations and planned activities.
- The premium for your actual trips, rather than an assumed saving based on the word “annual.”
CHOICE lists selected characteristics of the policy, including the 35-day trip duration and some item and delay limits. Treat such comparisons as a starting point: the PDS applicable to your purchase is the controlling document for contractual terms.
Medical conditions, activities and optional cover
Pre-existing medical conditions
TID says pre-existing medical cover may be available on application, subject to approval and payment of an applicable premium. Do not assume a condition is covered simply because you disclose it or buy the policy. Follow the insurer’s assessment process and check the decision, any extra premium and the resulting terms shown in your quote and certificate.
Rank #4
- Reveal leaving audiences astounded
- Amazing Magic Trick That is Easy to Perform
- High grade material for years of use
- Magic Makers made
Activities, snow sports, cruises and item limits
TID’s general multi-trip information lists possible paid options such as adventure activities, snow sports, cruises and increased item limits. This does not establish that every activity or trip is automatically covered, or that an option applies unless selected and accepted. Confirm the exact activity, dates and cover shown in your quote and certificate, then check the corresponding PDS terms.
What to verify in the PDS and certificate
The product and benefits pages are summaries, not a substitute for the policy wording. Before purchasing, match the following details to your plans in the current PDS, quote and certificate:
Best Value

- World'S Best Insurance Underwriter Ever
- Celebrate insurance agents, brokers, medicare advisors, and sales agents with this! Perfect for agency workers who appreciate helping clients find the right insurance policies. Show pride in your role with this.
- Dual wall insulated: keeps beverages hot or cold
- Stainless Steel, BPA Free
- Leak proof lid with clear slider
- Policy version: Identify the wording that applies to your purchase date. TID flags a change for policies purchased on or after 15 September 2026; verify the updated PDS rather than relying on earlier summaries.
- Trip boundaries: Check the maximum duration, the definition of a journey, and any applicable home-distance and return-home requirements.
- Benefits and sub-limits: Review limits for medical costs, cancellation, baggage, individual items and rental-vehicle excess, along with any relevant conditions.
- Medical and activity decisions: Confirm the outcome of any condition assessment and whether selected activities, snow sports or a cruise are included.
- Exclusions and claims requirements: Read the clauses that apply to your circumstances and understand what documentation or steps a claim may require.
- Purchase record: Keep the certificate and the wording supplied for your policy so you can refer to the terms that actually apply.
The precise insurer or issuer, detailed eligibility tests and post-change exclusions are not established by the product summaries described here. Do not infer those details from the headline benefit list.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

