
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
Summerland Bank no longer distributes CGU home insurance, so the available information does not establish that new customers can buy a current “Home Buildings and Contents Plus” policy through the bank. The linked policy document is CGU’s First Choice Home Insurance Product Disclosure Statement (PDS), not confirmation of a current Summerland “Plus” tier. Existing policyholders should check their policy schedule and contact CGU for assistance.
Is Summerland Bank Home Buildings and Contents Plus still available?
Summerland Bank says, “Summerland Bank no longer distributes CGU Insurance products.” Its insurance page directs existing home and contents policyholders to CGU for help with their policy and claims. That means this should be treated as a legacy or potentially outdated offer, not as a policy confirmed to be open to new applicants. Summerland Bank’s insurance page lists 1300 038 397 for existing-policy assistance and 13 24 80 for claims; confirm contact details on the bank’s page before relying on them.
The document still linked from the bank’s website is CGU’s First Choice Home Insurance Product Disclosure Statement. It explains CGU cover options, but does not establish that “Home Buildings and Contents Plus” is a current Summerland product tier. The PDS edition date is not confirmed in the accessible copy, so it should not be treated as proof of the terms currently applying to any policy.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minutePC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11What does the linked CGU policy document describe?
The PDS describes two cover types: Listed Events and Accidental Damage. A policy can cover buildings, contents, or both, and optional covers may be available. The selected cover and applicable excess are recorded in the policyholder’s schedule, so the schedule—not a general product label—is the key reference for an existing customer.
#1 Best Overall

- All-in-One Document Organizer – Designed to keep all your important papers neatly organized in one place, from passports and birth certificates to legal documents and medical records.
- Bound Expanding File Design – Features a sturdy bound construction with multiple expanding pockets, allowing you to store and separate documents by category for easy access.
- Secure Storage for Valuables – Perfect for safeguarding sensitive documents such as passports, birth certificates, social security cards, wills, deeds, and insurance policies.
- Home Records Management – Ideal for organizing household paperwork including tax returns, warranty information, utility bills, appliance manuals, and other essential family records.
- Compact & Space-Saving – Expands to hold a large volume of papers yet compresses for compact storage on bookshelves, in filing cabinets, or inside home safes.
Listed Events
Listed Events cover applies to loss or damage caused by incidents named in the wording, subject to the policy’s conditions and exclusions. The listed events include fire or explosion, earthquake or tsunami, impact, lightning, riots or civil commotion, storm, flood, rainwater or wind, theft or attempted theft, vandalism or malicious acts, and water or liquid damage.
Accidental Damage
Accidental Damage extends cover to accidental loss or damage, subject to the wording. It is not unrestricted cover: the PDS sets out conditions and exclusions, and some incidents have specific rules. The policy schedule identifies whether this cover was selected.
Rank #2

- All Materials Fireproof:This document bag is made entirely of flame-retardant materials from the outside to the inside. The double-layer design of fiberglass, aramid fiber, and aluminum foil provides multiple layers of fire protection for your important documents and valuables.
- 100% Fireproof and Water-resistant:The upgraded fireproof document bag not only uses fire-resistant and heat-insulating materials but can also withstand extremely high temperatures.Meantime, the Sealed zippers are totally waterproof which can survive the spray of firefighter's hose on full blast, provides 360° security seal and maximum protection for your documents
- Upgraded Waterproof Zippers & 2-Pocket Design & Large Capacity: Two pockets, two zips for added security and convenience. Let your files be easily classified and stored with our fire proof bag. Large size of 15”x 11.5” allows you to better keep and classify your most standard and legal documents files, passport, birth certificate, marriage certificate, contract and any other documents, cash, letters, photos and other valuables
- Zipper Closure Protection Design: The high-quality fireproof and waterproof zipper enhances storage security and carrying safety. Made with 1-piece construction and no bottom seam, our money bags are strong and reliable. The dual-layer design provides extra protection and convenient storage. The zipper features a strap for smoother use and easier carrying.
- After-Sales Service: If you have any questions or concerns, please feel free to contact us. Our customer service team will provide you with a solution within 24 hours. We’re happy to help.It also makes an ideal gift for men and women for holidays, Thanksgiving, Christmas, New Year, birthdays, and more
Buildings, contents, or both
The PDS allows buildings-only, contents-only, or combined insurance. Contents cover away from home is described for Australia under Listed Events, and for Australia and New Zealand under Accidental Damage, subject to the policy wording. Do not assume either scope applies to a particular customer without checking their schedule and applicable PDS.
What conditions and limits deserve close attention?
Event names alone do not establish whether a claim is covered. The PDS includes waiting periods, cause-specific requirements, and exclusions. For example, it describes a 14-day waiting period for flood in specified circumstances and a 48-hour waiting period in some bushfire, grassfire, or named-cyclone situations. It also addresses construction openings, structural defects, and faulty workmanship. These are examples, not a complete summary of the wording.
Rank #3

- 【Effortless Document Organization】 Keep your life in order with the Life Book Document Organizer. Easily sort and store important documents—such as certificates, contracts, bills, and personal records—so you can find what you need quickly and stay stress-free.
- 【Versatile Multi-Compartment Storage】 Featuring multiple compartments and pockets, this organizer is perfect for a variety of files, from personal paperwork to business documents. Every item has its designated place, helping you stay tidy and organized.
- 【Durable & Professional Design】 Made from high-quality materials, the organizer delivers lasting durability with a stylish appearance. Manage your files in a professional manner at home or work, and enjoy reliable protection for sensitive documents.
- 【Ideal for Home, Office & Travel】 Whether you’re working from home, managing a busy office, or attending meetings, the portable Life Book Document Organizer is a fantastic companion. Lightweight yet roomy, it’s ideal for everyday tasks and business trips.
- 【Perfect Gift for Organization】 A thoughtful gift for students, professionals, and anyone seeking better organization in life. Ideal for graduations, new job celebrations, business occasions, or simply as a practical gift to help friends and family simplify their paperwork.
The PDS gives a total limit of $2,000 for contents left in the open air at home for specified listed-event causes, including storm, flood, rainwater, wind, theft, or attempted theft, with stated exceptions. This is not a universal limit for all contents claims. It also states a maximum of $20,000,000 for all liability claims under the policy, including legal costs, and an additional $250 excess for specified earthquake claims under Listed Events. These are terms in the linked PDS; they should not be presented as current Summerland “Plus” benefits unless the policyholder’s applicable schedule and wording confirm them.
The exclusions include loss or damage resulting from earth movement, erosion, rust, corrosion, gradual deterioration, depreciation, wear and tear, and rats, mice, or insects. The complete exclusions and exceptions are broader than these examples. For a claim or coverage decision, use the wording and schedule that apply to the individual policy.
Rank #4

- Crafted of archival quality polypropylene plastic. Front is crystal clear; back is a solid color.
- Crafted of archival quality polypropylene plastic. Front is crystal clear; back is a solid color.
- Overall size: 4" x 9".
- Inside capacity of large pocket: 3 3/4" x 8 3/4".
- Inside capacity of small pocket: 3 3/4" x 2 1/8".
Is it possible to assess the price or value?
No current quote, current Summerland offer, customer satisfaction score, or independent product rating is established by the available policy information. Without a current offer and a quote based on the same property and household details, there is no sound basis for calling this policy good value or comparing its price with alternatives.
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Clear out junk files and repair common Windows errors3Fix the driver behind crashes, sound loss and screen glitchesIf comparing home insurance options, evaluate them using the same details and check the premium alongside the building and contents sums insured, basic and event-specific excesses, listed-event and accidental-damage scope, flood terms and waiting periods, temporary accommodation, valuables limits, exclusions, claims settlement approach, and whether the policy is currently available through the named distributor.
Best Value
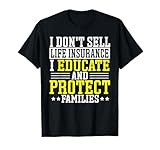
- Life insurance clothes that says: I don't sell life insurance, I educate and protect families.
- Life insurance clothes ideal for any insurance sales agent, medicare broker or salesperson who wants to show off his got life insurance vibe.
- Lightweight, Classic fit, Double-needle sleeve and bottom hem
What should an existing policyholder do?
- Read the current policy schedule. Confirm whether the policy covers buildings, contents, or both; which cover type was selected; and which excesses apply.
- Use the PDS that applies to that policy. The document linked by Summerland is CGU First Choice, but its edition date is not confirmed in the accessible copy. Check the policy documents supplied for the individual policy rather than assuming the linked document is current.
- Contact CGU about assistance or a claim. Summerland directs existing policyholders to CGU. Its page lists 1300 038 397 for assistance and 13 24 80 for claims; verify the numbers on the current bank page.
Verdict
Summerland Bank Home Buildings and Contents Plus cannot be assessed as a currently available offer on the information established here. Summerland says it no longer distributes CGU insurance, while its linked PDS describes CGU First Choice cover rather than confirming a current Summerland “Plus” product. Existing policyholders should rely on their schedule and applicable wording; prospective customers should confirm availability directly before treating the legacy product name as an option.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

