
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Repair Windows errors before they cause bigger problems3Fix the driver behind crashes, sound loss and screen glitchesiTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
Short answer: Micron’s fiscal 2026 results show a powerful recovery led by memory pricing and data-center demand associated with artificial intelligence (AI), but they do not prove that today’s growth or margins will persist. Memory remains a cyclical business: supply additions, average selling prices, customer inventories, manufacturing execution and PC, smartphone, automobile and server demand can quickly change earnings. Micron’s own filings also show meaningful concentration, with more than half of fiscal 2026 revenue from its ten largest customers and about 60% from the data-center end market. Those facts explain both the bull case and the investment risks; they do not, by themselves, establish whether MU shares are cheap, expensive or suitable for any investor.
What Micron sells and why the stock is cyclical
Micron Technology makes memory and storage components rather than finished AI applications. Its portfolio includes DRAM, high-bandwidth memory (HBM), NAND flash and solid-state drives used in servers, PCs, smartphones, vehicles, networking equipment and other devices. Demand for these components is measured in bits and gigabytes, while manufacturers continually add capacity and improve process technology. That combination creates a pronounced cycle.
When device makers and cloud operators need more memory than suppliers can produce, prices and operating margins can rise sharply. Suppliers then invest in cleanrooms, wafer equipment and packaging. New output, a slowdown in end-device sales or excess customer inventories can reverse the balance. Because a large portion of manufacturing cost is fixed, a decline in average selling prices can reduce profit much faster than revenue falls. A strong year therefore should be read as a point in the cycle, not as a permanent earnings baseline.
What fiscal 2026 actually delivered
Micron’s fiscal year ended September 3, 2026. The company reported $133.19 billion of fiscal 2026 revenue and $54.23 billion in fiscal fourth-quarter revenue. These are nominal U.S.-dollar figures reported by Micron for that fiscal period, not estimates or a run-rate forecast.
#1 Best Overall

- [Color] PCB color may vary (black or green) depending on production batch. Quality and performance remain consistent across all Timetec products.
- DDR3L / DDR3 1600MHz PC3L-12800 / PC3-12800 240-Pin Unbuffered Non-ECC 1.35V / 1.5V CL11 Dual Rank 2Rx8 based 512x8
- Module Size: 16GB KIT(2x8GB Modules) Package: 2x8GB ; JEDEC standard 1.35V, this is a dual voltage piece and can operate at 1.35V or 1.5V
- For DDR3 Desktop Compatible with Intel and AMD CPU, Not for Laptop
- Guaranteed Lifetime warranty from Purchase Date and Free technical support based on United States
| Company measure | Fiscal 2024 | Fiscal 2025 | Fiscal 2026 | What it indicates |
|---|---|---|---|---|
| Core Data Center Business Unit revenue | $4.98 billion | $7.23 billion | $37.59 billion | Rapid expansion of Micron’s broader data-center memory and storage business |
| Cloud Memory Business Unit revenue | $3.79 billion | $13.52 billion | $43.09 billion | Strong cloud-related growth during the reported upturn |
| Total company revenue | Not stated in the cited figures | Not stated in the cited figures | $133.19 billion | Full-year company result |
| Fourth-quarter total revenue | Not stated | Not stated | $54.23 billion | Fiscal Q4 2026 result |
Source for the segment and full-year figures: Micron Technology, Inc., Form 10-K for the fiscal year ended September 3, 2026; fourth-quarter figure: Micron’s fiscal Q4 and full-year 2026 release dated September 30, 2026.
The segment figures are not interchangeable with total company revenue: business-unit definitions and internal allocations differ from consolidated reporting. They are useful for showing where growth was concentrated, not for adding up Micron’s income statement.
How the memory cycle can turn
Supply and demand move on different clocks
Micron warns that worldwide memory and storage demand may weaken while suppliers are still bringing on capacity. A fab, cleanroom expansion or advanced packaging line takes years to plan and qualify, so companies can overshoot demand. Conversely, a sudden demand surge can leave suppliers unable to add output quickly enough. Either mismatch affects utilization, pricing and cash needs.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Average selling prices often matter more than unit growth
DRAM and NAND are highly competitive products. A supplier can ship more bits and still earn less if market prices fall faster than costs improve. In an upswing, constrained supply can lift prices and mix toward premium products such as HBM. In a downturn, price erosion can spread across product generations and customers, pressuring gross margin even when volumes remain substantial.
Customer inventories can delay the next order
Device manufacturers and cloud customers may build inventory when shortages are feared. Once they hold enough stock, they can reduce purchases for several quarters without a comparable collapse in end-user consumption. Micron identifies customer inventory corrections, demand-forecasting errors and customer credit conditions as factors that can make its results volatile.
Rank #2

- Office Gaming Mini PC - UPGRADED GMKtec Nucbox M5 Ultra Series is equipped with the powerful AMD Ryzen 7 7730U processor, 8 Cores/16 Threads, Base 2.00GHz (Power Saving Quiet Mode) with Turbo Boost up to 4.50GHz (Performance Mode) in BIOS settings, Based on the ZEN 3+ architecture, this small but powerful mini pc delivers satisfying results in productivity, office work, and gaming. 35% Performance increase over AMD Ryzen 5 7430U/ Ryzen 7 5700U, 5600U, 5560U, 5500U.
- 16GB DDR4 RAM & 256GB PCIe SSD - Installed with DDR4 16GB RAM (1x16GB), the Nucbox M5 Ultra mini pc support expansion to 64GB RAM. Featured with 256GB M.2 2280 PCIe 3.0 SSD, support dual slot expansion to 4TB SSD. (Upgrades not included)
- DUAL NIC LAN 2.5G RJ45 - Fast Network Speeds: Enjoy up to 2500Mbps data transmission speed without worrying about lagging. Ideal for working, gaming, and surfing the internet. Great for Untangle, Pfsense or as a server office PC.
- Mini Desktop Computer with 4K Triple Screen Display - Nucbox M5 Ultra integrates AMD Radeon Graphics 8 Cores 2000 MHz GPU to deliver powerful graphics processing power to easily handle the demands of complex design software, 4K@60Hz UHD video editing, and playback. It can connect to 3 display screens simultaneously.
- Fast Internet WiFi 6E + BT5.2 Connection - GMKtec Mini PC with WiFi-6E Wireless, have 2.5G/5G/6G triple band, more faster and lower latency. Bluetooth 5.2 allowing you more quickly to connect other wireless devices (headset, mouse, keyboard, etc.) Interface features 2*USB3.2 ports, 2*USB2.0 ports, 1*HDMI 2.0 port(4K@60Hz), 1*USB-C port(PD/DP/DATA), 1*DP Port, 1*Audio 3.5mm (HP&MIC), 1*DC Power Port.
End-market demand is not uniform
PC, smartphone, automobile and conventional server demand each have different replacement cycles and economic sensitivities. A rebound in one market cannot automatically offset weakness in another, especially when product qualification and packaging capacity are specialized. Micron’s filings describe these downturns as recurring possibilities, not as an assertion that a particular market will weaken next.
How much of Micron’s growth is tied to AI?
AI infrastructure is an important current driver, especially for data-center memory. Micron says earlier Cloud Memory growth reflected higher DRAM bit shipments and average selling prices as AI demand accelerated for HBM, high-capacity DIMMs and low-power server DRAM. Its data-center offerings include DDR5, HBM, LPDDR5, registered DIMMs (RDIMMs), data-center SSDs and NAND.
Free tools Windows power users keep installed
One-click scans. No signup required.
The reported business-unit numbers show the scale of that exposure: Cloud Memory revenue rose from $3.79 billion in fiscal 2024 to $13.52 billion in fiscal 2025 and $43.09 billion in fiscal 2026. Core Data Center revenue rose from $4.98 billion to $7.23 billion and then $37.59 billion over the same years. Micron does not report that every dollar in those units is AI revenue, and these units do not represent all of the company’s products. The defensible conclusion is that AI and data-center demand are major growth engines, not that Micron’s entire future depends exclusively on AI.
In fiscal Q3 2026 investor materials, CEO Sanjay Mehrotra said: “Micron’s record fiscal Q3 financial results and even stronger outlook for Q4 reflect the strategic value of memory in the AI era.” That is management’s characterization of the opportunity. It is not independent evidence that AI demand, pricing or margins will remain at the same level.
Why HBM is strategically important
HBM stacks memory close to advanced processors and requires demanding packaging, testing and yield control. If accelerator shipments and model training expand, HBM content per system can rise, creating a higher-value mix than some conventional memory products. High-capacity DIMMs and server DRAM can benefit from the same trend as operators increase memory per server.
Rank #3
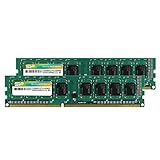
- Efficient performance: A lower voltage of 1.35 V is applied to reduce 20% power, enabling to effectively decrease hardware power consumption.
- System upgrade: With our high quality memory module, ideal for virtualization, cloud computing and multitasks handling, 100% factory-tested for stability, durability and compatibility.
- Durability Armed: 100% factory-tested to make sure the high stability, durability and compatibility.
- Compatibility is imperative: Compatible with major DDR3L / DDR3 motherboards.
- 【NOTE】The DDR3L UDIMM is backed by a lifetime warranty to promise complete services and technical support.
Higher-value products do not remove cyclicality. They still depend on customer qualification, packaging capacity, manufacturing yields, utility availability and the pace at which cloud and systems companies deploy equipment. A product can be strategically important while its pricing eventually faces competition and additional supply.
Recommended Free Tools
Why the AI thesis can disappoint
Micron’s filing says the long-term trajectory of emerging AI demand is uncertain and may fluctuate. Spending can be delayed by power constraints, networking bottlenecks, product launches, financing conditions or a reassessment of expected returns. If customers slow deployments, cancel or defer orders, or reduce inventories after a build-out, memory demand and prices can weaken even while AI remains a large technology trend.
Customer and end-market concentration
More than half of Micron’s fiscal 2026 revenue came from its ten largest customers, and approximately 60% came from the data-center end market, according to the 2026 Form 10-K. Concentration can improve planning when large customers provide visibility, but it also increases the effect of a single customer’s design choice, qualification decision, inventory correction, credit problem or bargaining pressure.
Data-center concentration also means that the company’s results can become more sensitive to a smaller set of capital-spending programs than a diversified consumer mix would be. The percentage is a fiscal 2026 snapshot; it should not be projected unchanged into every future year.
Bull case versus risk case
| Question | Potentially favorable outcome | What can go wrong |
|---|---|---|
| AI and data-center demand | Accelerator deployments increase HBM, high-capacity DIMM, server DRAM and SSD content per system. | Cloud customers delay projects, reduce orders after an inventory build or discover that expected AI returns do not justify planned capacity. |
| Product mix and pricing | Premium HBM and other high-value products support stronger average selling prices and margins. | New capacity, competing products, qualification delays or weaker bit demand cause price declines that outweigh mix benefits. |
| Customer commitments | Longer-term planning and qualifications improve utilization and help Micron fund specialized capacity. | Orders may be deferred, changed or canceled; concentration leaves less flexibility if a major customer’s plan shifts. |
| Capacity and manufacturing | Successful equipment installation, utilities, yields and advanced packaging convert demand into profitable shipments. | Yield problems, equipment shortages, construction delays, supplier disruptions or power constraints raise cost and postpone revenue. |
| Stock outcome | Earnings and cash flow exceed the expectations already reflected in MU’s share price. | The business grows but the stock underperforms because valuation assumptions, margins or cycle duration were too optimistic. |
Neither column is a forecast. It is a framework for testing which assumptions an investor is making and what evidence would invalidate them.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Rank #4

- RYZEN 7 H 255 CPU - The Ryzen 7 H 255 is a chip from the Hawk Point family and is an upgraded version of the older Ryzen 7 8745H and has 8 cores (16 threads thanks to SMT support) that run at up to 4.9 GHz, together with the powerful Radeon 780M iGPU. Unlike Zen 3, Zen 4 offers AVX512 support along with other improvements such as larger caches/registers/buffers across the board.
- GAMING PC - The Radeon 780M (12 CUs / 768 shaders, up to 2,600 MHz) can drive multiple displays simultaneously with a resolution of up to 8K. Hardware encoding and hardware decoding of the most common video codecs (AV1, AVC, HEVC) is also no problem; playing the latest games on FSR settings without issues.
- WHY CHOOSE DDR5 5600MHz DUAL CHANNEL (2×16GB): With a 5600MHz clock—a 17% frequency uplift over 4800MHz—this kit delivers massive bandwidth gains that elevate real-world performance. Gamers enjoy higher minimum FPS and less stutter in open-world and sim titles for a smoother competitive experience. Video editors and 3D creators benefit from faster 4K/8K timeline scrubbing, quicker renders in DaVinci Resolve and Premiere, and swifter asset loading. For AI/LLM workloads, the superior throughput reduces I/O bottlenecks, cuts token generation latency, and accelerates model fine-tuning by keeping processing cores fed with data—so you wait less and create more.
- 32GB DDR5 RAM + 512GB SSD - The K12 mini computer is equipped with Dual 16GB (Total 32GB) SO-DIMM DDR5 5600MHz memory sticks. 512GB PCIE 4.0 SSD Drive with 3x M.2 2280 Expansion slots. Each slot capable of reading up to 8TB. (24TB MAX)
- QUAD SCREEN 4K DISPLAY SUPPORT - K12 Mini PC support 4-screen 4K/8K output via HDMI 2.1 (8K@60Hz), DisplayPort 1.4 (4K@60Hz), and USB Type-C Transfer speed (supporting PD3.0/DP1.4/DATA). Ideal for gaming, video editing, and multitasking, it provides expansive and crisp multi-display support.
Risks Micron explicitly discloses
Demand, pricing and oversupply
Micron states that lower worldwide demand, excess industry supply or inaccurate forecasts could reduce shipments and average selling prices materially. Memory markets can deteriorate quickly because suppliers’ products are broadly substitutable and customers can postpone purchases. The filing discusses prior downturns to illustrate the mechanism, not to predict a date for the next one.
Manufacturing, equipment and utilities
Memory production depends on high yields, reliable utilities, specialized equipment and a large network of suppliers. A disruption at a fab, a shortage of equipment, delayed installation, a defect excursion or inadequate power and water can reduce output or increase costs. Expanding capacity for HBM and other advanced products adds qualification and packaging steps that must work together.
Customer, credit and relationship risk
Large customers can exert pricing pressure and may experience their own financial stress. A customer’s inventory correction or credit issue can affect shipments and receivables. Product design wins also require qualification; losing a socket or failing a qualification can have effects that last beyond one quarter.
Geopolitical and trade restrictions
Micron identifies geopolitical tensions, export controls, tariffs and other trade restrictions as potential interruptions to sales, supply chains and manufacturing plans. Rules can change by jurisdiction, and compliance may limit where products, equipment or technology can be shipped.
Capital intensity and execution
Adding capacity requires substantial capital before revenue arrives. If demand weakens after investment commitments are made, depreciation and operating costs can remain while utilization falls. If Micron underinvests, it may miss a shortage; if it overinvests, oversupply can pressure returns. This timing problem is central to understanding a memory manufacturer.
Best Value

- Boosts System Performance: 32GB DDR5 RAM laptop memory kit (2x16GB) that operates at 5600MHz, 5200MHz, or 4800MHz to improve multitasking and system responsiveness for smoother performance
- Accelerated gaming performance: Every millisecond gained in fast-paced gameplay counts—power through heavy workloads and benefit from versatile downclocking and higher frame rates
- Optimized DDR5 compatibility: Best for 12th Gen Intel Core and AMD Ryzen 7000 Series processors — Intel XMP 3.0 and AMD EXPO also supported on the same RAM module
- Trusted Micron Quality: Backed by 42 years of memory expertise, this DDR5 RAM is rigorously tested at both component and module levels, ensuring top performance and reliability
- ECC Type = Non-ECC, Form Factor = SODIMM, Pin Count = 262-Pin, PC Speed = PC5-44800, Voltage = 1.1V, Rank And Configuration = 1Rx8
How to interpret the next company outlook
Micron’s September 30, 2026 fiscal Q4 release gave fiscal Q1 2027 revenue guidance of $61.5 billion, plus or minus $1.5 billion. This is management’s forward-looking range for the quarter, not a reported result, a guarantee or a valuation estimate. Actual revenue can differ because of shipment timing, customer decisions, pricing, foreign-exchange movements, manufacturing yields and other factors.
The same release discussed product sampling, shipments and qualification developments. Treat those items as company statements about progress. Sampling does not equal mass production, and a qualification milestone does not guarantee a specific revenue amount or margin. Compare future reported results with the range and examine whether changes came from volume, price, mix or costs.
What these disclosures can—and cannot—tell you about MU stock
Revenue growth alone cannot establish fair value or expected return. A stock price reflects expectations about future earnings, margins, capital spending, cycle duration and risk. Even excellent operating results may already be anticipated by investors; conversely, a temporary downturn may create an opportunity if long-term cash generation remains intact. The cited company disclosures do not provide a complete valuation model, independent price target or personalized suitability assessment.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →Questions to put into a valuation model
- What portion of near-term revenue and margin depends on HBM, high-capacity DIMMs or other AI-linked products?
- How quickly could average selling prices fall if industry supply expands faster than demand?
- What capital expenditure, depreciation and working-capital needs accompany planned capacity?
- How much concentration can the business absorb if a major customer changes its inventory or architecture?
- What earnings multiple or cash-flow yield is already implied by the current share price?
Answering those questions requires dated market prices, financial statements and assumptions beyond the company’s revenue release. A reader should not infer a buy, sell or hold decision from the fiscal 2026 figures alone.
A practical checklist for following Micron
- Separate results from guidance. Mark fiscal Q4 2026 revenue as historical and the $61.5 billion ± $1.5 billion Q1 2027 figure as an outlook.
- Track price, volume and mix separately. Higher bit shipments with falling prices can produce a very different earnings outcome from moderate volume growth with stable pricing.
- Watch customer inventories and concentration. Read comments about the ten largest customers, data-center spending and qualification schedules for signs of dependence or diversification.
- Check execution indicators. Follow HBM and server-memory yields, packaging capacity, equipment delivery, utilities and capital-spending commitments.
- Stress-test the cycle. Model weaker PC, smartphone, automobile, server and AI demand rather than assuming all end markets rise together.
- Compare the business with the share price. Decide whether current expectations already assume strong margins and prolonged AI growth; do not substitute revenue growth for valuation work.
Bottom line
Micron’s fiscal 2026 numbers document a remarkable upturn, with $133.19 billion of company revenue, sharply higher Cloud Memory and Core Data Center revenue, and substantial data-center exposure. AI demand for HBM and other server memory is a credible current growth driver. The same disclosures show why MU remains a cyclical investment: pricing can fall, supply can overshoot, customers can correct inventories, manufacturing can miss targets and concentration can magnify a change in spending. Use the results and Q1 2027 guidance as dated evidence, then perform separate valuation and risk analysis before reaching an investment conclusion.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

