
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
Organize GST records so an auditor or lawyer can trace any return figure back to the original transaction, supporting document, accounting entry, payment, and tax calculation. Use one controlled archive for each GSTIN and financial year, retain records for at least 72 months from the due date of the relevant annual return, and place any records connected with an appeal, revision, proceeding, or investigation under a preservation hold until the later statutory endpoint. Keep readable, restorable electronic records and preserve the original system context needed to prove them.
What a defensible GST record system must achieve
For Indian GST, the objective is not merely to keep copies of sales invoices. A defensible system lets a reviewer move in both directions:
- From a filed return, tax ledger, or financial-statement figure to the invoices, credit or debit notes, delivery evidence, payment, stock movement, and tax calculation behind it.
- From an individual source document to the accounting entry, return table, e-way bill or other movement record, and proof that the transaction was reported correctly.
The Central Goods and Services Tax Act, 2017 (CGST Act) and CGST Rules, 2017 cover inward and outward supplies, bills of supply, delivery challans, credit and debit notes, vouchers, e-way bills, stock, advances, and tax and input-tax-credit accounts, as applicable. Your archive should therefore be a linked record set, not an invoice-only folder.
This is practical recordkeeping guidance. State or Union Territory GST enactments, notifications, a specific notice, and the facts of a dispute can add requirements. Check the current consolidated law and obtain professional advice for a live audit, investigation, appeal, or court case.
#1 Best Overall

- Stable & sturdy construction: Expanding file folder is made from durable wipe-clean polypropylene. Acid-free and high-quality for using trustingly. Waterproof & sturdy enough to keep the file organizer from collapsing. The accordion folder's cord closure and adjustable flap provide additional security. Built-in file separation layers are flexible to ensure the files don't wrinkle.
- Handy organization & Easy lookup: Expandable file folder has 24 pockets designed for keeping our paperwork organized. Accurately classified storage in the specific color slot and labeled with tabs, so it is easier to find the papers what is needed.
- Plentiful storage: Product Size: 13'' L x 9.25'' H. Each pocket fits well for all A4/Letter size paper. Excellent scalability. The accordion file folder can be stretched pretty far, more than 24 inches. 24 pockets allow you to store more than 4000 sheets of paper documents.
- Portable & stylish: Classic lightweight folder organizer can be compressed to a minimum thickness of about 2 inches, so it can be held up great for traveling to and from all different locations for work. Fits perfectly when completely closed in the file cabinet. The dividing sections of the rainbow file folders come in six bright colors, stylish and beautiful. Versatile document organizer for home, office, school, and travel scenarios, compact and light.
- Expandable desktop folder: Folders can be expanded to different widths as the number of files you put into increases. Stand on its own on the desk and not easy to tip over when pulled out to maximum capacity and filled. Each pocket is completely sealed at the bottom to keep small objects do not move.
Retention periods: calculate from the annual-return deadline
CGST Act section 36 states the general period as 72 months from the due date for furnishing the annual return for the year to which the accounts and records relate. The clock does not start on the invoice date and is not automatically six years from the end of the financial year. The statutory wording is: “retain them until the expiry of seventy-two months from the due date of furnishing of annual return for the year pertaining to such accounts and records.”
Records connected with proceedings or investigation
If you are a party to an appeal, revision, other proceeding, or an investigation for an offence under Chapter XIX, retain records pertaining to that subject matter until one year after final disposal or the ordinary statutory period, whichever is later. A proceeding-specific hold can therefore extend well beyond the normal 72-month date.
Build a retention register
Maintain a simple register with the GSTIN, financial year, annual-return due date, ordinary destruction date, affected proceedings, final-disposal date, and revised destruction date. Record the person who approved a hold or release. Do not calculate a deletion date from an invoice date alone.
Free tools Windows power users keep installed
One-click scans. No signup required.
| Situation | Retention endpoint | Action |
|---|---|---|
| Ordinary GST records | 72 months from the due date of the relevant annual return | Calculate and document the date in the retention register. |
| Appeal, revision, other proceeding, or Chapter XIX investigation | One year after final disposal or the ordinary period, whichever is later | Flag the subject matter and suspend routine deletion. |
| Potential dispute not yet formalized | Not a substitute for a statutory calculation | Ask counsel whether a litigation hold is appropriate and define its scope. |
Set up the archive by GSTIN and financial year
Create a top-level electronic and, where needed, paper location for each GSTIN and financial year. This prevents records for different registrations or years from being mixed and makes a notice response faster. Keep records for each business place accessible in the manner required by the rules.
Recommended hierarchy
- GSTIN – use the complete registration number as the first identifier.
- Financial year – use an unambiguous format such as
FY2025-26. - Return period – use the month or quarter and return type.
- Record class – separate outward supplies, inward supplies, notes, movement, payments, stock, refunds, reverse charge, and reconciliations.
- Transaction or batch index – link documents that belong to the same transaction or return batch.
A practical structure might look like:
GSTIN-27XXXXXXXXXX1Z5/FY2025-26/2025-04-GSTR-1/01-Outward-Invoices
GSTIN-27XXXXXXXXXX1Z5/FY2025-26/2025-04-GSTR-1/02-Credit-Debit-Notes
GSTIN-27XXXXXXXXXX1Z5/FY2025-26/2025-04-GSTR-3B/03-Reconciliation
GSTIN-27XXXXXXXXXX1Z5/FY2025-26/04-Inward-Supplies
GSTIN-27XXXXXXXXXX1Z5/FY2025-26/05-E-Way-Bills-and-Delivery-Challans
GSTIN-27XXXXXXXXXX1Z5/FY2025-26/06-Payments-and-Receipts
GSTIN-27XXXXXXXXXX1Z5/FY2025-26/07-Stock-and-Movement
GSTIN-27XXXXXXXXXX1Z5/FY2025-26/08-Refunds-Reverse-Charge
GSTIN-27XXXXXXXXXX1Z5/FY2025-26/09-Filed-Returns-and-Acknowledgements
GSTIN-27XXXXXXXXXX1Z5/FY2025-26/10-Notices-and-Proceedings
The exact folder names are optional. Consistency, indexing, access control, and the ability to restore and interpret the records matter more than the labels.
Use a transaction index that proves the links
Keep a spreadsheet or database index with one row per invoice, note, or other material transaction. Use a stable identifier that does not change when a file is moved.
Minimum index fields
- GSTIN, financial year, return period, and record type.
- Invoice, note, challan, or voucher number and date.
- Supplier or customer GSTIN, legal name, place of supply, and tax category where relevant.
- Taxable value, tax rate, each tax component, total value, and currency if applicable.
- Accounting voucher or ledger reference.
- Payment or receipt reference and date.
- E-way bill, delivery challan, transport, or stock-movement reference.
- Return type, table or line reference, filing date, and acknowledgement number.
- File path or document identifier for every supporting record.
- Correction, cancellation, amendment, or dispute status.
Use a naming convention such as GSTIN_FY_Period_DocumentType_Number_Date. Preserve the supplier’s original invoice number inside the index even when you assign an internal identifier. Never overwrite a corrected document; retain the original, the replacement, and a note explaining the change.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minuteRank #2

- Size: 13 x 10 x 0.7 inches. Fits A4 and letter-size paper, standard documents and filing needs.
- User-Friendly Features: Included sticker labels allow you to easily distinguish between different categories of files, maintaining neatness and enhancing productivity!
- Sleek and Portable: Designed to slip seamlessly into backpacks, laptop bags, or file cabinets, our lightweight folder keeps your documents tidy and accessible wherever you go.
- Built to Last: Crafted from polypropylene, our folders resist tears and deformation while remaining flexible. The secure snap closure offers easy access while keeping your papers securely in place.
- Versatile Utility: This folder isn't limited to organizing course papers for college students; it's perfect for storing business tax documents, recipes, important receipts, and more!
File every GST record class, not just sales invoices
Organize each class so an auditor can see why it exists and how it affected a return.
Outward supplies
Keep tax invoices, bills of supply, export or special-supply support where applicable, amendments, cancellations, and customer purchase-order or contract evidence that explains the supply. Link each item to the sales ledger and the outward-supply return line.
Inward supplies and input tax credit
Retain supplier invoices, debit notes, receipt or service-completion evidence, purchase orders, goods-received records, and the working paper supporting input-tax-credit eligibility and apportionment. Link the document to the purchase ledger and the return period in which credit was claimed, reversed, or reclaimed.
Credit and debit notes
Store the original invoice reference, reason, taxable and tax amounts, approval, customer or supplier communication, and the return in which the adjustment was reported. Keep evidence for price revisions, returns, discounts, or other commercial explanations.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchDelivery challans, e-way bills, and movement evidence
Group movement records with the related invoice or stock transfer. Preserve vehicle or transporter details, dispatch and receipt dates, warehouse or job-work documentation, and proof that explains differences between invoice, dispatch, and receipt dates.
Advances, vouchers, payments, and receipts
Keep advance receipts, payment vouchers, bank references, cash records where applicable, and subsequent adjustment documents. A payment record should identify the invoice or account it settles; a bank statement alone may not explain the GST treatment.
Stock and production records
Retain opening and closing stock, inward and outward movement, production or consumption records, wastage or shortage explanations, and warehouse reconciliations. Link material variances to accounting and GST adjustments.
Rank #3

- Expanding file folder in Black with flap and cord closure for organizing and securing 8.5 x 11-inch letter-size documents
- Holds up to 260 sheets; 13 pockets for easy subdividing; each pocket expands to 7/8-inch
- Archival quality, acid free, and PVC free
- Waterproof and tear resistant
- Made of durable poly material
Refunds and reverse charge
Maintain refund applications, statements, acknowledgements, sanction or deficiency communications, export or payment evidence where relevant, and the calculation supporting the claim. For reverse charge, keep the contract or invoice, tax calculation, payment entry, and corresponding credit or reversal working.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Place reconciliations beside the records they explain
For each return period, preserve the filed return, acknowledgement, general-ledger extract, tax-liability calculation, input-tax-credit reconciliation, amendments, and explanations for exceptions in one period folder. The working paper should identify the source reports and the person who prepared and reviewed it.
Three useful reconciliation views
- Sales ledger to outward return: explain timing differences, exempt or non-GST supplies, credit notes, cancellations, and amendments.
- Purchase ledger to input-tax-credit claim: explain blocked, ineligible, missing, reversed, or subsequently reclaimed credit.
- Tax ledger to payment and return: tie liability, credit utilization, cash payment, interest, late fee, and closing balances to the filed return and challans.
Keep exception reports rather than deleting unmatched items. Add a disposition column showing whether an exception was corrected, carried forward, or supported by a documented explanation.
Make electronic records restorable and readable
CGST electronic-record provisions require proper electronic backup that can be restored within a reasonable period after destruction caused by accident or natural causes. A backup that cannot be opened, decoded, or connected to the accounting record is not a useful archive.
Backup design
- Maintain at least one backup separated from the primary system and protect it against unauthorized alteration.
- Test restoration on a schedule and record the date, sample restored files, result, and person who tested it.
- Keep exports in readable formats and preserve the application or report layout needed to interpret them.
- Retain data dictionaries, code explanations, record counts, and field definitions where the system uses abbreviations or coded values.
- Preserve the audit-trail and source-document links showing how a ledger entry was created or changed.
- Control deletion, overwriting, and version changes through documented permissions.
The rules refer to producing duly authenticated records in hard copy or readable electronic form. They also refer to audit-trail inter-linkages, including the source document, financial accounts, record layout, data dictionary, explanations for codes, record counts, and sample documents on demand. Design your exports so these elements can be supplied without reconstructing the system from memory.
Paper copies and scanning
Paper can be useful for signed agreements, delivery acknowledgements, or documents that arrived physically, but scanning does not automatically replace the original for every legal purpose. Keep originals when retention duties, authenticity, a notice, or counsel requires them. An expanding file-folder organizer is an optional aid for paper copies; it does not provide electronic backup, restoration, or audit-trail capability.
Prepare for electronic-record proof in litigation
The Bharatiya Sakshya Adhiniyam, 2023 (BSA) is the current central evidence statute relevant to electronic-record proof. Sections 61–63 address electronic or digital records and their proof. Section 63 sets conditions for computer outputs and contemplates a certificate accompanying the electronic record when it is tendered under that provision.
Rank #4
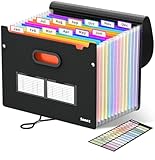
- Superior Durability: Featuring strong 100C thickened cover and reinforced edges, surpassing competitors in durability. Made from PVC-free, acid-free materials, ensuring secure organization of bills and documents while delivering unparalleled durability and reliability
- Deeper Pockets & Unobstructed Tabs: In response to a common issue in accordion folders where papers cover index labels, we've increased pocket height by 0.8 inches (2 cm). This unique enhancement ensures your labels remain visible—a feature unmatched by competitors
- Ample Capacity Monthly Bills Organizer: Our expandable monthly bill organizer can extend up to 14 inches, accommodating over 1500 sheets files while standing stable. With 12 pockets, it's perfect for storing tax records, bills, receipts, invoices and important family files for over a year
- Sticky Labels & 3 Loops Bungee Closure: Colorful monthly tabs and labels help you locate the target object at a glance and manage monthly tasks with ease. The elastic band closure with three loops expands generously to accommodate all your storage needs
- Unlock Versatile Organization: Whether at home, in the office, or on the go, it offers flexible organization for invoices, medical finance records, and identification documents, ensuring efficiency wherever you need it
Do not assume that a PDF export, screenshot, or spreadsheet is automatically sufficient in every proceeding. The applicable procedure depends on the kind of record, how it was generated, the proceeding, and the statutory conditions. Preserve the original system record, metadata and audit trail where available, the export, and the context needed to explain who created it and how it was kept. Ask litigation counsel to determine whether a section 63 certificate or another evidentiary step is required.
The BSA states a general preference for primary evidence and identifies circumstances in which secondary evidence may be given. Do not destroy originals merely because a scan exists.
Separate ordinary archives from a litigation or investigation hold
When you receive a notice, become aware of an appeal or revision, or reasonably anticipate a dispute, create a proceedings folder linked to the affected GSTIN, periods, and transaction identifiers.
- Record the matter name, authority or court, notice date, response deadline, and subject periods.
- Identify custodians, systems, mailboxes, accounting databases, paper locations, and outside service providers holding relevant records.
- Issue a written preservation instruction that suspends routine deletion, overwriting, and backup rotation for the defined subject matter.
- Copy notices, audit requests, replies, submissions, acknowledgements, meeting notes, and correspondence into the proceedings folder.
- Keep a log of what was collected, from where, by whom, when, and in what format.
- Release the hold only after counsel confirms that the matter is finally disposed of and the later applicable retention endpoint has been calculated.
A hold should be proportionate: preserve the records connected with the matter, but do not silently alter unrelated archives or create duplicate versions that cannot be explained.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Know the statutory audit timeline
For an audit under CGST Act section 65, the Act provides for notice at least 15 working days before the audit is conducted. The audit ordinarily must be completed within three months from commencement. The Commissioner may extend that period by up to six further months for recorded reasons. After the audit concludes, the officer must inform the registered person of findings, rights and obligations, and reasons within 30 days.
These are statutory process provisions; a specific notice, later amendment, or related proceeding may affect what happens in practice. Read the notice carefully and calendar every response and production date.
Assemble a response pack
- Registration details, organizational chart, and list of business places relevant to the period.
- Filed returns, acknowledgements, payment challans, and amendment history.
- Trial balance, ledgers, tax accounts, and the return-to-ledger reconciliation.
- Indexed source documents and the files that prove delivery, receipt, payment, stock, and tax treatment.
- Written explanations for exceptions, unusual transactions, exemptions, deductions, refunds, and input-tax-credit adjustments.
- A document-production log showing what was supplied, when, in what format, and under whose authority.
Provide only what is requested, but preserve the complete underlying record set. Keep a copy of every submission exactly as delivered.
Best Value

- LASTS ALL YEAR. GUARANTEED! Guarantee is valid for one year from purchase or delivery date, whichever is longer. Does not cover misuse.
- Scan, study and organize your notes with the Five Star Study App. The clear front pocket on the file makes any paper compatible with the Five Star Study App, so you can access your notes, handouts and more from any device.
- Get organized! 6 tabs let you see what's filed and where. They also help you with prioritization and organization.
- Durable plastic outer shell with secure zipper closure helps protect those important papers, while reinforced gussets help prevent sides from tearing
- Holds letter size 8-1/2" x 11" sheets. Available in Black.
Choose storage methods by control, not convenience
| Approach | Strengths | Risks to control | Minimum safeguards |
|---|---|---|---|
| Paper archive | Visible originals and easy handling of signed documents. | Slow search, physical damage, duplicate copies, and weak remote access. | Indexed boxes, controlled access, environmental protection, and retention holds. |
| Electronic archive | Fast retrieval, indexing, sharing, and linkage to ledgers and returns. | Corruption, accidental deletion, unreadable exports, and unauthorized changes. | Restorable backups, access controls, readable exports, audit trails, and periodic restore tests. |
| Managed storage service | May provide centralized access, backup operations, and retention controls. | Dependence on export capability, provider access, and contract terms. | Test exports and restoration, define ownership and access, preserve audit-trail links, and maintain an independent copy where appropriate. |
| Hybrid archive | Retains originals while using electronic indexing for speed. | Mismatch between paper and electronic versions. | Assign one identifier, record the original location, and reconcile scanned and physical sets. |
No storage method is endorsed by the CGST Act or Rules. Select the method that can produce complete, authenticated, readable records and restore them within a reasonable period.
Control access, changes, and document authenticity
- Give staff the minimum access needed for their role and review permissions when they change jobs.
- Use separate preparation and review responsibilities for returns and reconciliations.
- Record who approved manual journal entries, invoice cancellations, credit notes, and tax adjustments.
- Keep immutable or otherwise protected audit logs where the system supports them.
- Use consistent time settings and document any migration between accounting systems.
- Preserve original file hashes or equivalent integrity checks when your counsel or system policy requires them.
- Never edit a filed return or source invoice in place; create an amendment or explanatory record.
Common failures and how to correct them
Deleting by invoice age
Failure: Files are deleted six years after the invoice date. Correction: Recalculate from the relevant annual-return due date and check for proceedings or investigation holds.
Keeping only PDFs
Failure: A PDF is retained without the ledger, source link, metadata, or system explanation. Correction: Preserve the source record, readable export, record layout, code explanations, audit trail, and reconciliation.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Unmatched return totals
Failure: The return is filed, but no working paper explains differences from the sales or purchase ledger. Correction: Keep period-specific reconciliations with an exception and resolution log.
Broken links after migration
Failure: An accounting-system change leaves old document paths unusable. Correction: Export linked documents, map old identifiers to new ones, test sample retrieval, and preserve the migration record.
Routine backup rotation destroys relevant evidence
Failure: A notice arrives after the relevant backup has been overwritten. Correction: Issue a hold immediately, preserve affected backups, and document the preservation steps.
Paper and electronic versions conflict
Failure: A scan differs from the signed original or no one can identify the authoritative copy. Correction: Assign one document identifier, retain the original location, record the scan date and operator, and obtain advice before discarding anything.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Quick Recap
A practical implementation checklist
- List every GSTIN, business place, financial year, accounting system, and paper archive.
- Calculate the 72-month endpoint for each year from the annual-return due date.
- Identify appeals, revisions, proceedings, investigations, notices, and reasonably anticipated disputes.
- Create the GSTIN/year hierarchy and a proceedings folder linked to affected periods.
- Inventory outward and inward supplies, notes, bills of supply, challans, e-way bills, vouchers, stock, advances, payments, refunds, reverse charge, and tax accounts.
- Assign stable identifiers and build the transaction index.
- Place each period’s filed returns, acknowledgements, ledgers, reconciliations, and exception explanations together.
- Configure backups, access permissions, audit trails, readable exports, and restoration testing.
- Preserve record layouts, data dictionaries, code explanations, record counts, and source-document links.
- Train staff not to overwrite originals and to escalate notices or potential disputes immediately.
- Test retrieval by selecting a return line and tracing it to the source document, then reverse-trace a source document to the return.
- Review the retention register at least annually and document any hold release only after the later applicable endpoint is confirmed.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

