
Free tools Windows power users keep installed
One-click scans. No signup required.
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
At its 57th meeting on 8 October 2026, the GST Council recommended changes that could make export treatment clearer for certain Indian testing, repair, research and clinical-trial services, and broaden some refund calculations. The proposals are not yet a change in force: the place-of-supply amendment and refund measures depend on legal implementation. Even if implemented, a recipient-location place of supply would not by itself guarantee zero-rating or a refund.
What the Council recommended for testing, R&D and clinical trials
The central proposal is to omit section 13(3)(a) of the Integrated Goods and Services Tax (IGST) Act, 2017. That provision currently places certain services where they are performed when goods are made physically available to the service provider. The Council’s FAQ identifies testing, repair, R&D and clinical trials as examples.
If the recommendation is implemented as described, these services would instead use the default rule in section 13(2): the place of supply would be the location of the service recipient. For a recipient abroad, that could remove the specific place-of-supply obstacle to export or zero-rated treatment that arises when the performance location is in India.
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Clear out junk files and repair common Windows errors3Fix the driver behind crashes, sound loss and screen glitches| Question | Current treatment described in the Council FAQ | Recommended treatment, if implemented |
|---|---|---|
| Does the service require goods to be made physically available to the Indian provider? | For covered services, section 13(3)(a) places the supply where the service is performed. | Omit section 13(3)(a) for the affected services and apply section 13(2)’s recipient-location default. |
| What does that mean if the customer is abroad? | The place of supply may be in India even when the recipient is abroad and payment is received in foreign exchange. | The place of supply would be the recipient’s location, subject to the enacted amendment and applicable facts. |
| Does that alone make the supply zero-rated or refundable? | No. The place-of-supply rule is one part of the analysis. | No. Other applicable export-of-service and zero-rating requirements, as well as refund rules, still matter. |
The Council’s FAQ describes the existing-rule concern this way: “For services requiring goods to be made physically available to the supplier in India for the provision of service (e.g., testing, repair, R&D, clinical trials), place of supply is considered as the location of performance of services, i.e. in India as per provisions of section 13(3)(a) of the IGST Act, 2017, denying export/zero-rating benefit even though the recipient is abroad and payment is received in foreign exchange.” This is the FAQ’s account of the current treatment and the reason for the recommendation, not confirmation that a new rule has commenced.
#1 Best Overall

- High Accuracy and Precision: Each pipette is calibrated in accordance with ISO8655 and each micro pipette is supplied with an individual test certificate.
- Wide Tip Compatibility: It is compatible with most universal tip brands covering full volume range
- Humanization: ergonomic design, lightweight plunger force can reduce repetitive strain injury. The digital display can clearly read the volume setting. Tip ejector for easy and fast needle tip replacement.
- Easy to calibrate: Each pipette is fully calibrated before shipment. It's easy to calibrate for the users with the tools and instruction supplied.
- 1 Year Guarantee and Satisfied Service: we are manufacturer which has more than 20 years experience in the field of lab products. . Any quality problem, we will provide free replacement
Which pharma and research work may be affected
The practical question is whether the service falls within the provision targeted by the recommendation, including whether goods are made physically available to the provider. The FAQ’s examples cover testing, repair, R&D and clinical trials. An earlier GST Council agenda recorded a request associated with the Association of Biotechnology Led Enterprises concerning Indian pharma R&D for foreign clients; examples included integrated drug discovery and development, toxicology, analytical testing, bioequivalence and bioavailability studies, and clinical trials. That older agenda is background to the issue, not proof of the 2026 legal position or evidence that the earlier request was adopted.
Refund processing: proposed automation and timing
The Council also recommended a phased move toward more system-based refunds. The measures described for Phase 1 and Phase 2 are proposals, and eligibility remains subject to the applicable conditions, system risk evaluation and legal implementation.
Rank #2
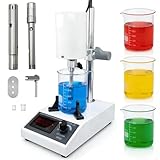
- [Versatile Applications]: The Protytan Adjustable High Speed Homogenizer is suitable for homogenizing animal and plant tissues, cell dispersion, and emulsification. Widely used in biochemical, pharmaceutical, agricultural, and food industries, this tool is essential for research and industrial applications
- [Compact & Durable Design]: This lab homogenizer features a compact design (11.81 9.84 15.75 in, 15.43 pounds) and is built with durable 304 stainless steel homogenizing blades. It is engineered to withstand rigorous use in labs and industrial settings, providing long-lasting reliability
- [Efficient Performance]: Equipped with two homogenizing knives (18000 RPM and 20000 RPM), this high-speed homogenizer can break down cell membranes and emulsify organic compounds efficiently. It handles both animal and plant tissues with precision for optimal results
- [Adjustable Speeds & Digital Display]: With a wide speed range of 2000-20000 RPM, the Protytan homogenizer offers adjustable speeds for different tasks. The digital speed display allows for easy monitoring and precise adjustments during operation
- [Easy Maintenance]: Designed for easy cleaning and maintenance, simply rinse the homogenizing cutter with clean water after each use. Replaceable polyfluoroethylene parts ensure the homogenizer stays in optimal condition for long-term performance
| Proposal | What the recommendation says | Practical qualification |
|---|---|---|
| Excess electronic cash-ledger balance | Automatic full refund of the excess balance in Phase 1. | Applies to eligible balances under the implemented process. |
| Acknowledgement or deficiency memo | Reduce the period from 15 days to 10 days in Phase 1. | This is a recommended processing period, not a statement that the shorter period is already operative. |
| Provisional refund for zero-rated and inverted-duty-structure claims | Risk-based automatic provisional sanction of 90% of eligible claims in Phase 1. | The 90% is a proposed provisional share for eligible claims, subject to system risk identification and evaluation; it is not an unconditional advance for every claimant. |
| Full sanction for eligible zero-rated claims | Phase 2 contemplates more automated acknowledgement and full refund sanction after adjustment of pending dues and risk evaluation. | Full sanction remains subject to eligibility, dues adjustment and risk evaluation. |
Which input tax credits could enter refund calculations
The recommendations would expand specified credit categories used in calculating certain refunds. They do not make every input-service or capital-goods credit refundable, and the proposed start dates and apportionment period are material.
| Refund route and credit | Recommended treatment | Proposed timing and qualification |
|---|---|---|
| Inverted-duty-structure refund: input-service ITC | Include eligible input-service input tax credit in the calculation. | Proposed only for credits availed on or after 1 November 2026. |
| Zero-rated and inverted-duty refunds: eligible capital-goods ITC | Include eligible capital-goods input tax credit, apportioned over 60 months. | Proposed from 1 April 2027; eligibility and apportionment would be governed by the implemented rules. |
Do not treat a higher input-service tax as the inverted-duty test
The Council FAQ clarifies that input-service tax being higher than output tax does not, by itself, establish an inverted-duty structure. The relevant comparison remains the tax rate on inputs against the rate on output supplies. Businesses should not infer eligibility for an inverted-duty refund from the rate on services alone.
Rank #3

- Single cup, six tubes, single cup single, single operation; automatic timed shutdown.
- [Automatic Function]: automatic detection, automatic diagnosis, automatic alarm. With the function of setting timing, automatic timing and timing reset, MPU is used to automatically control the temperature, time and frequency of the engine room. The instrument automatically controls the temperature of the water bath to 370 ° C. The preset temperature can be reset at any time. Reduce manual intervention and improve experimental consistency. Using single-chip microcomputer as the core computer control technology, intelligent control of water bath temperature, working time two performance parameters
- [Operation Flexibility] : The instrument automatically sets the lifting time of the basket to 15 minutes, and can also be reset arbitrarily: the lifting movement of the basket can be started or stopped by pressing the lifting key. When the test time reaches the set value, the hanging basket automatically stops in the position, which is convenient for loading the hanging basket and beaker;
- [High-precision Control] : the stepper motor can be accurately controlled to 31 times/min to ensure the accuracy of the test; Intelligent panel to make the operation easier; Temperature control accuracy: ±0.3℃; Time control accuracy: ±0.5min; High precision digital electronic sensor; Ensure the high precision and accuracy of the water bath temperature, without calibration; Electronic temperature sensors can display and monitor the temperature of water baths and beakers
- [Convenient Timing Function]: 3-digit digital display time, the smallest unit of timing time within 1 hour is displayed in seconds, convenient for recording and scientific research. The preset duration ranges from 1 to 900 minutes.
Other export measures in the recommendations
The meeting also recommended changes concerning the definition of export of services in relation to distinct establishments, clarification of permitted payment in foreign exchange or Indian rupees, and an SEZ/FTWZ rule for certain supplies to overseas buyers. These are separate export-facilitation proposals. They should not be read as part of, or as substitutes for, the specific section 13 place-of-supply change affecting services such as testing, R&D and clinical trials.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.What businesses should verify before claiming export treatment or a refund
- Confirm the legal status. The 57th-meeting press release dated 8 October 2026 records Council recommendations. Check the enacted amendment, notification, circular or other applicable legal instrument before treating a proposed rule or date as effective.
- Classify the service and facts. Identify the service performed, whether goods are made physically available to the Indian provider, and where the recipient is located. Do not assume every research or laboratory service falls within the same treatment.
- Test the complete export and zero-rating conditions. A recipient abroad and foreign-exchange payment do not make the place-of-supply proposal a standalone guarantee of export status, zero-rating or refund entitlement.
- Choose the relevant refund route. Distinguish a zero-rated supply refund from an inverted-duty-structure refund; the credit categories and proposed timing differ.
- Check credit dates and apportionment. For the proposed expanded calculations, verify when input-service credit was availed and apply the proposed 60-month spread for eligible capital-goods credit only if and when the relevant provision is implemented.
The Council’s FAQ says its answers are for educational and guidance purposes and have no legal validity; final notifications, circulars and amendments govern implementation. The Council’s recommendations therefore describe the intended policy direction, while the operative legal text and its commencement determine what a taxpayer can actually claim.
Quick Recap
Best Value

- Range: 0.00~ 1.00aw; Accuracy: ±0 .02aw; Resolution: 0.01
- It is a portable water activity meter, which can measure the water activity of solid (powder, granular, block), liquid and pasty samples.
- Widely used in food processing, feed production, chemical and pharmaceutical, scientific research, experiments and other occasions.
- Note: It is not suitable for frozen items and volatile components liquid etc.
Rank #4
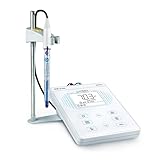
- Equipped with Swiss LabSen 823 pH/Temp. Electrode with Protelyte electrolyte and 3 ceramic junctions
- 1-3 points of auto. calibration with self-diagnosis and electrode condition display
- Max/Min reading mode allows you to quickly analyze measurement during a period of time
- Comes with a simple electrode holder for up to 2 electrodes and pre-mixed calibration solutions (pH4/7/10, 50ml for each)
- 50 sets of data storage; IP54 spill-proof and dust-proof
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

