
Free tools Windows power users keep installed
One-click scans. No signup required.
iTechGuides is reader-supported. When you buy through links on our site, we may earn an affiliate commission. As an Amazon Associate I earn from qualifying purchases. Learn more
A cryptocurrency accounting system is the combined set of accounting policies, controls, transaction records, valuation methods, reconciliations and software that an organization uses to account for crypto-asset activity and to produce financial statements or tax reports. Software is only one part of it. A tool can organize transaction data, but it cannot choose the accounting policy or replace a review of the underlying records.
What the term covers
No single official definition or standard product carries the name “cryptocurrency accounting system.” The definition above is a practical synthesis of what U.S. accounting and tax requirements expect a crypto recordkeeping process to do. It is not a formal definition issued by a standard setter, so treat it as an explanation of the concept rather than a term defined in a rulebook.


The phrase bundles three jobs that are easy to confuse. Each has different rules and produces a different output.
The three jobs a system performs
| Job | Core question | Governing rules | Typical output |
|---|---|---|---|
| Financial reporting | How are crypto assets classified and measured in the entity’s financial statements? | The applicable accounting framework (for U.S. entities, U.S. GAAP) | Carrying values, fair value gains and losses, footnote disclosures |
| Tax accounting | What taxable events occurred, and what are the proceeds, basis, income and supporting records? | The tax rules of the relevant jurisdiction (for U.S. taxpayers, federal tax law and IRS guidance) | Gain or loss calculations, income reporting, tax schedules |
| Operational recordkeeping | Do wallet, exchange, custodian, payroll and payment records agree with each other? | Internal policies, controls and the reporting obligations above | Reconciled transaction ledger, exception reports, audit trail |
A system that handles only one of these jobs will usually fail at the others. For example, a fair value figure used for financial statements does not tell you the tax basis of a specific coin, and a tax report built from incomplete exchange exports will not reconcile to the general ledger.
Financial reporting under U.S. GAAP
The accounting treatment depends on both the framework and the asset. Under U.S. GAAP, FASB Accounting Standards Update (ASU) 2023-08 introduced fair value measurement for crypto assets that fall within the standard’s scope. It does not make every digital asset subject to that model. Whether a given holding is in scope depends on the criteria in the standard itself, so classify each asset type against those criteria before choosing a measurement method.
What ASU 2023-08 requires
FASB issued ASU 2023-08 on December 13, 2023. For crypto assets within its scope, an entity measures them at fair value in each reporting period, and changes in fair value are recognized in net income. In FASB’s issuance announcement, FASB Chair Richard R. Jones said: “The new standard responds to feedback from stakeholders of all backgrounds who indicated that improving the accounting for and disclosure of crypto assets should be a top priority for the Board.”
KPMG’s 2026 handbook summarizes the effective date as fiscal years beginning after December 15, 2024, including interim periods within those years. For a calendar-year company, that means the standard applies from the annual period beginning January 1, 2025. Check the effective-date section of the standard for any transition details that apply to your entity.
Recommended Free Tools
Rank #2

- Easy To Track Your Finances: HAUTOCO accounting ledger book keeps you on top of your expenses and income! Help you keep your money organized, spend well, and set and achieve financial goals
- Premium Material: The A5 accounting ledger book has a total of 120 pages and 2040 lines of entries. It is made of 100gsm thick paper to reduce ink leakage; it is equipped with a waterproof and sturdy PP cover to protect the inner pages
- Practical Design: Compact 8.3 x 6.2'' expense tracker notebook is easy to carry and features information pages, 2025 calendar, yearly financial goals page, and PVC pocket for storing important tickets and loose items
- Manage Your Finances Effectively: Undated accounting books with number, date, description, account, payment or deposit amount, and total balance. You will be able to easily analyze your financial activities and quickly prepare accurate financial statements
- Ideal For Small Business or Personal Use: An accounting log journal can track your business or personal financial status. With a clear record of transactions, you can find unnecessary expenses or fraudulent charges
The pre-2023 model still matters for history
Before ASU 2023-08, many crypto holdings under U.S. GAAP were generally treated as indefinite-lived intangible assets, measured at cost less impairment. A 2022 joint FASB-IASB staff paper described that practice and the reasoning behind it, including the observation that many cryptocurrencies did not meet the definitions of cash, cash equivalents, financial assets or inventory. Use that material to understand older comparative periods or prior-year statements. It is not the current rule for assets within ASU 2023-08’s scope.
Active FASB work on crypto transfers
The rules are still moving. FASB’s project page, last updated July 8, 2026, reports ongoing work on crypto transfers. That work covers wrapped or receipt tokens and clarification of when control of an asset has transferred, which determines derecognition. The page also reports April 15, 2026 deliberations on expanding the scope for certain tokens and on an example disclosure for significant wrapped tokens, while derecognition guidance remained a future consideration. Confirm the current status on FASB’s site before relying on any of these items, because the project may have changed since that update.
Tax accounting under U.S. federal rules
For U.S. federal tax purposes, the IRS treats digital assets as property rather than currency. Its definition covers digital representations of value recorded on a cryptographically secured distributed ledger or similar technology, and it names cryptocurrencies, stablecoins and NFTs as examples. Because the tax question is separate from the financial reporting question, a GAAP carrying value and a tax basis are not interchangeable. A system should record both and reconcile the difference.
Rank #3

- EFFORTLESSLY MANAGE YOUR FINANCES: Dive into the world of efficient financial management with this accounting ledger book. It's your gateway to tracking payments, deposits, and balances, fostering excellent bookkeeping habits to reach your financial aspirations.
- UNLEASH THE POWER OF UNDATED TRACKING: With an undated accounting book ledger, you're equipped to chronicle every expenditure, regardless of when it occurs. Ample space awaits to meticulously document each transaction, detailing numbers, dates, descriptions, accounts, payment or deposit amounts, and overall balances.
- EMPOWER FINANCIAL SUCCESS: Harness the potential of this accounting log book to analyze your financial endeavors effortlessly. Prepare precise financial statements in no time, allowing you to scrutinize spending and income regularly. Identify and eliminate unnecessary expenses, paving the way for enhanced financial performance and success.
- EXEMPLARY QUALITY: Our accounting ledger book boasts premium quality, crafted from 100gsm paper that minimizes ink leakage, fraying, and shading concerns. The robust and flexible cover shields the pages, while the metal lay-flat twin-wire binding ensures durability and sustained usage.
- VERSATILE UTILITY: Embrace the flexibility of our undated accounting book, enabling you to commence your financial journey anytime, anywhere. Its compact size of 8.6x5.9 inches ensures portability, fitting snugly into any bag for easy access whenever you need it most.
Information the IRS expects for each disposal
For a disposed asset, the IRS identifies several items as relevant: the type of asset, the transaction date and time, the number of units, the fair market value at the time of the transaction, and the basis. The IRS digital assets page says basis generally starts with the U.S.-dollar cost and that acquisition date and time, units and fair market value are part of the basis information. A record that lacks any of these fields makes the gain or loss calculation hard to support.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problemsUnit identification and FIFO
The IRS FAQ says a taxpayer may specifically identify units if the identification and basis can be substantiated. Acceptable approaches include unit identifiers or sufficiently detailed records. When units are not specifically identified, the FAQ applies first-in, first-out (FIFO). The FAQ states that it generally applies to transactions completed before January 1, 2025. For transactions after that date, check the current IRS guidance before choosing a method, and make sure your system can record the identification method you use.
Broker reporting on Form 1099-DA is phased
The IRS describes broker reporting on Form 1099-DA in two stages:
| Reporting element | Applies to | Start date (per IRS) |
|---|---|---|
| Gross proceeds | Certain broker transactions | January 1, 2025 |
| Basis | Certain broker transactions | January 1, 2026 |
The requirements apply to brokers that take possession of customer assets. They do not extend to commonly known decentralized or non-custodial brokers that do not take possession. A taxpayer who used a self-custody wallet or a decentralized protocol may therefore receive no 1099-DA at all, and must rely on its own records. Do not assume that a 1099-DA from one platform captures every transaction in your wallet.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.What the system must capture
A workable record set should be able to preserve and reconcile the following:
- Identifiers: wallet addresses, exchange and custodian account references, and transaction hashes or IDs, with a flag for on-chain versus off-chain activity.
- Asset and event: asset identity, quantity, date and time of each transaction, and the event type, such as acquisition, sale, exchange, payment, transfer, reward or other receipt.
- Valuation: the U.S.-dollar fair market value at the relevant event, plus the source or method used to support that value.
- Cost and proceeds: acquisition cost, adjusted basis, fees, and the proceeds or value received.
- Unit identification: the method used to match units to sales, where it matters for tax.
- Reconciliation and review trail: evidence that reported totals tie back to underlying transactions, and a record of who reviewed unusual items and why.
The last item is a practical control rather than a requirement stated in IRS guidance. The IRS pages describe what records must support, but they do not prescribe specific software controls or endorse any product.
Best Value
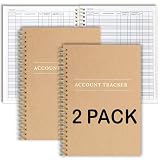
- PERFECT FOR RECORD KEEPING: The 2 Pack account ledger books are versatile and can be used to track finances, budgets, expenses, and other business or personal records. They are perfect for individuals, entrepreneurs, or small business owners who need a reliable and efficient way to keep track of their finances. With 100 pages, customers can record transactions over an extended period, making it a handy tool for financial planning and organization.
- COMPACT AND LIGHTWEIGHT: The account ledger books are compact and lightweight with each book weighing 7 ounces and measuring 8.5 x 6.25 inch, making them easy to carry around. You can take them with them in a bag or briefcase, making them ideal for on-the-go use. This feature ensures that you can access your records at any time, whether you are at work or on the move.
- DURABLE KRAFT COVER: The kraft cover is a distinguishing feature of these account ledger books. It provides a durable layer of protection that can withstand daily wear and tear, making it suitable for long-term use. Additionally, the classic, rustic appearance of the cover gives it a timeless and professional look that can fit in any setting.
- PREMIUM QUALITY: Elegant style with the words ''Account Tracker'' embossed in fancy Gold Foils. The gold coil ring binding is a practical design feature that enhances the functionality of the account ledger books. It allows pages to turn smoothly and easily, making it effortless to flip through the book while keeping pages in place. The ring binding also ensures that pages won't fall out, preventing the loss of vital information.
Evaluating software for the job
Sources do not compare vendors, and this article does not recommend one. If you are selecting a tool, test each candidate against these criteria in order:
- Framework and jurisdiction: Does it support the financial reporting framework and the tax jurisdiction you need?
- Coverage: Can it import the chains, assets, exchanges, custodians and off-chain transactions you actually use?
- Record quality: Does it keep timestamps, units, basis, valuation evidence, fees and source transaction IDs?
- Reconciliation: Can staff investigate unmatched transactions, correct classifications and preserve an audit trail?
- Outputs: Does it produce the entries, tax calculations or broker reconciliations you need?
- Human review: Can an accountant or tax preparer inspect assumptions and resolve uncertain transfers, rewards and asset classifications?
These criteria follow from the record and reporting requirements above. Confirm supported assets, integrations, pricing, security and geographic availability directly with any provider, since these details change.
Limits of this explanation
This article covers U.S. GAAP and U.S. federal tax rules. It does not establish the treatment of a particular token under IFRS, nor the rules of other countries, and both can differ materially. If you report under another framework or in another jurisdiction, apply the same three-job structure, but confirm the rules with a local adviser.
Also note that FASB’s crypto-transfer work and the Form 1099-DA rollout are both still in progress. The dates above reflect the sources as they stood at the times noted.
Quick Recap
“
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.

